
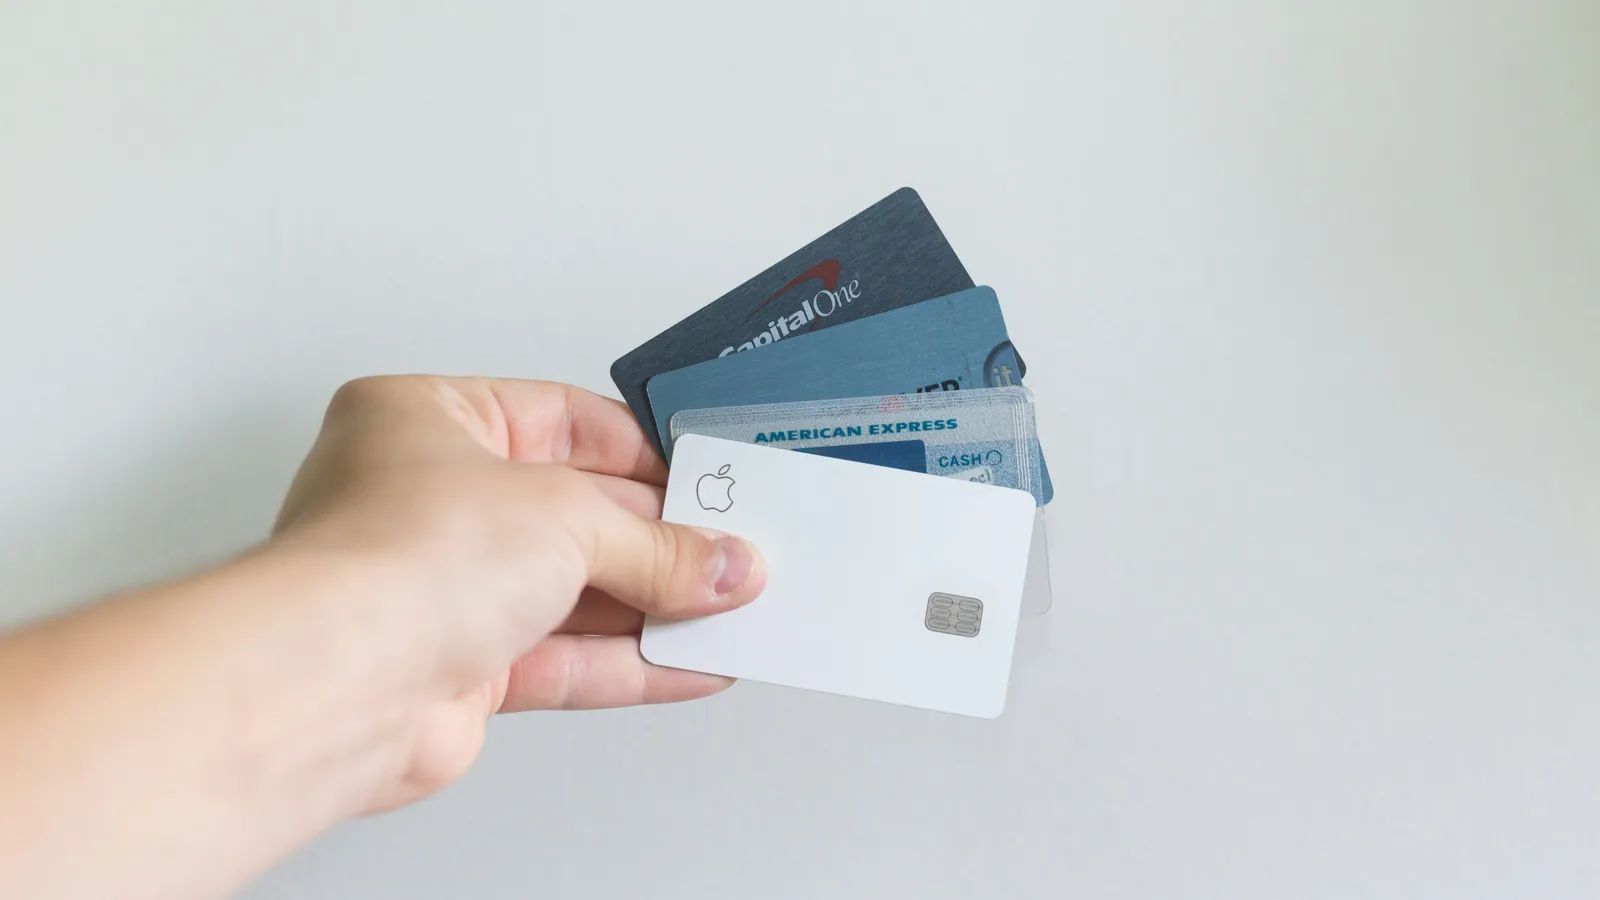
Keeping track of a large card collection can turn into a part-time job, particularly when each card carries its own offers, statement credits and expiring perks. A writer for The Points Guy says they hold 27 cards and rely on a service called CardPointers to manage them. The piece, published on The Points Guy [1], argues that the tool has returned several hundred dollars in savings and is worth paying for, and it arrives as holiday travel planning and Black Friday shopping reach their peak. ([1])
How the app handles offers across cards
The writer describes CardPointers as an app and browser extension that adds card offers automatically rather than requiring manual activation. CardPointers+ automatically adds all of my Chase, Citi, Capital One, Bank of America, and Amex offers to my cards. That matters most for people who hold several issuers’ cards at once, since each bank typically has its own offer page.
The writer says the most useful feature is the automatic enrollment itself. On one occasion, the browser extension added 841 new merchant offers to eligible Citi cards during a single session. The app also flags statement credits, suggests which card to use at a given store and sends location-based reminders for nearby offers. Notably, the writer says a user can shop as usual and still benefit, which is the core of the pitch.
Some of the savings described are modest, and others are larger. The writer cites a $5 credit on a $10 Burger King purchase, a $75 credit following a stay at a Grand Hyatt resort in Hawaii on an American Express card, and a $200 credit that surfaced while shopping for an Oura ring during a Black Friday sale. Taken together, the writer estimates the app has saved several hundred dollars this year alone.
What the savings claims do and do not show
The company says most users save more than $750 a year, a figure that appears in the article but has not been independently audited. The writer’s own account is anecdotal and reflects one heavy user with a large card portfolio. Results will likely differ for someone with two or three cards and few active offers.
Reviews on the App Store point in a similar direction. One reviewer said they would rate the app itself around 4 to 4.5 stars, while another described the auto-add feature as a source of a lot of value for online shopping and sometimes in store as well. These comments are individual opinions, but they suggest the appeal is consistent among users who already juggle multiple cards.
Free version versus paid membership
The free version lets users add and track their cards, but with a key limit. Users can track only one card of each brand, which may be enough for someone with a single Amex and a single Chase card but restrictive for a larger collection. The paid tier, CardPointers+, unlocks the full feature set, including the automatic offer additions, bonus reminders, annual fee reminders and offer tracking.
Pricing depends on the plan and timing. An annual membership normally costs $100, but the sale brings it down to just $50 for the year. Or, if you’d rather pay once and be done with it, you can grab a lifetime membership for $150 instead of the usual $300.
| Plan | Usual price | Black Friday sale price |
|---|---|---|
| Annual CardPointers+ | $100 per year | $50 per year |
| Lifetime CardPointers+ | $300 | $150 |
The writer notes that a special link from The Points Guy also offers 50 percent off, and says they plan to buy a lifetime membership. Readers should confirm the current terms on the CardPointers site before purchasing, since promotions have changed frequently. Earlier 50 percent sales in 2026 have already expired.
Related Stories From Travelbinger
Timing, deadlines and what to weigh first
The current discount is time-limited. From now through November 30, 2026, you can score a 50% discount on an annual or lifetime CardPointers+ membership. Buyers who want to test the service before committing can start with the free version, which still shows whether the app recognizes their cards and offers.
Anyone considering the paid plan should weigh the cost against the number of cards and benefits they actively track. A household with several premium cards, multiple annual credits and frequent store-based offers is the group most likely to recover the fee. Someone with one or two cards may find the free tier sufficient, and the lifetime option only makes sense for a user who expects to keep using the app for years.
The writer’s experience suggests that the real value lies in the small credits that would otherwise go unnoticed. Whether those credits add up to hundreds of dollars will depend on each person’s card portfolio and spending habits, so the decision rests on that math rather than on a headline number.