Most people spend decades building their retirement nest egg, pinching pennies and maxing out their 401(k) contributions, dreaming of the day they can finally exhale. Honestly, it’s one of the most important financial decisions most of us will ever make. The problem? A lot of people forget that where you retire matters just as much as how much you save.
Two retirees with the same savings can face very different outcomes depending on state taxes, housing costs, healthcare access, and everyday expenses. Some states will stretch your savings beautifully over 30 years. Others will chew through them in a decade or less. The six states below are the ones you really need to think hard about before packing your bags.
1. Hawaii: Paradise Has a Price Tag Few Can Afford
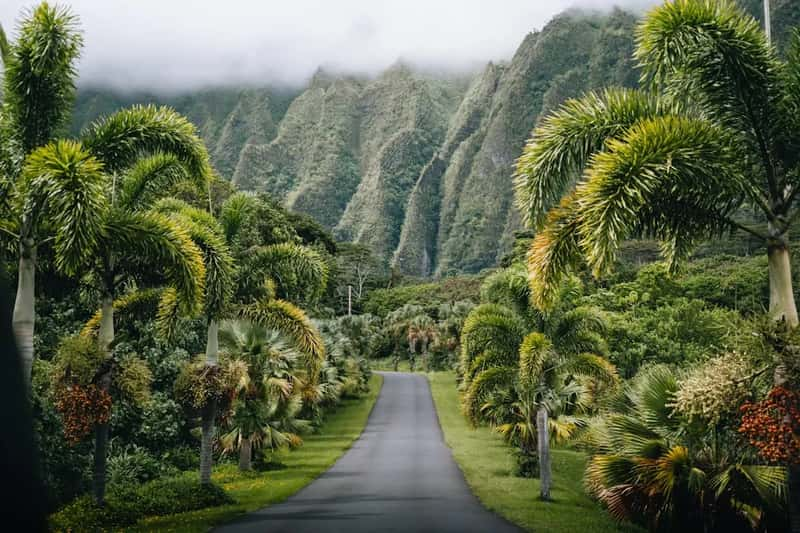
Let’s start with the most dramatic case, because the numbers are almost hard to believe. In Hawaii, retirees need about $2.2 million to stop working at 65 and cover essential living expenses for 25 years, including housing, groceries, transportation, utilities, and healthcare costs. That figure, from a January 2026 CNBC analysis based on Bureau of Labor Statistics data, covers only the basics. No cruises, no grandkids’ birthday gifts, no spontaneous dinners out.
Hawaii ranks as the most expensive state to retire, with average annual expenditures reaching $129,296, driven largely by steep prices for housing, groceries, and healthcare. Think about it this way: spending at that rate is like running a small business just to keep the lights on. Hawaii requires the largest monthly savings contribution at $7,458 per month just to retire comfortably there, according to GOBankingRates 2026 research.
Hawaii has a state income tax rate that caps out at 11%, one of the highest in the U.S. And while Hawaii boasts the lowest property tax in the country with an effective rate of 0.32%, it offers little relief from the overall tax burden. The math is brutal, and for most retirees with typical savings, that paradise lifestyle can evaporate financially within a decade.
2. California: The Golden State That Drains Golden Years
With affordability being a main factor, California was ranked near the bottom and named among the worst states for retirement according to a 2025 analysis, as it also has the highest income tax rate in the U.S. That top rate sits at 13.3%, the steepest of any state in the nation, according to the Tax Foundation. For retirees drawing from IRAs, pensions, or investment accounts, that tax bill doesn’t go away just because you stopped working.
Retirement income is fully taxed in California, with an exception for Social Security benefits, and high taxes, lofty housing costs, and high sales taxes make it a financially challenging place for retirees. California ranks worst for housing, with median home prices well over $700,000, making it financially impossible for many retirees to buy or maintain property. That’s not a typo. The median home in California costs more than most people save in a lifetime for retirement.
California requires the second-highest monthly retirement savings in the country at $5,804 per month, according to the latest GOBankingRates 2026 data. In fact, roughly one in ten seniors is currently living in poverty in California, a sobering sign that the dream and the reality diverge sharply here. Sunshine and ocean views are wonderful, but they don’t pay the rent.
3. New York: The Empire State Taxes You on Your Way Out Too
New York has the heaviest tax burden of any state and faces issues with expensive housing and overall affordability, with many retirees finding it hard to maintain financial security, especially outside of major metro areas. Here’s the thing: even if you move away from Manhattan to upstate New York, the tax environment follows you statewide. You don’t escape it by avoiding the city.
Retirement in New York is expected to last just over 16 years on average, and for those 16 years, the average retiree needs to save $1.41 million, the second-highest requirement among all states. New York suffers from very high cost-of-living, with the expected funds needed to retire comfortably estimated at over $1.3 million, while goods and services are 10% more expensive than national prices.
New York’s annual property taxes based on median home values come in at approximately $6,303, one of the highest in the country. The Tax Foundation reports that New York ranks among the states with the highest overall tax burden, alongside Hawaii, Vermont, Massachusetts, Minnesota, Washington, Maryland, Connecticut, California, and New Jersey. For retirees on fixed incomes, that combination of high property taxes, income taxes, and living costs is a slow but relentless drain.
4. Massachusetts: High Costs, High Taxes, and a Tightening Squeeze
Massachusetts taxes most retirement income and imposes an estate tax, with the estate tax exemption at $2 million for 2025 and estate taxes that can jump as high as 16% in the Bay State. Most retirees don’t think of estate taxes until it’s too late to plan around them. In Massachusetts, that oversight can cost a family hundreds of thousands of dollars in inherited wealth that simply disappears.
The average retiree in Massachusetts will need an annual income of $83,135 per year, and with an average retirement age of 66 and life expectancy of 79.9 years, the required savings come to about $1.16 million. Massachusetts also requires the third-highest monthly savings contribution in the country at $5,293 per month, making it extremely difficult for average earners to adequately prepare. Even people who saved diligently throughout their careers can find the math simply doesn’t work out.
Massachusetts ranks among the highest states for annual property taxes based on median home values, with homeowners paying approximately $5,584 per year. Additionally, Massachusetts tightened its circuit breaker tax credit for seniors in 2025, reducing the maximum credit from $1,200 to $1,000. Small changes like that might seem minor in isolation, but stacked together, they signal a direction of travel that is not friendly to retirees’ wallets.
5. New Jersey: Ranked the Worst State to Retire Two Years Running
New Jersey is the worst state to retire due to its high cost of living and top personal income tax rate, as well as poor aging health overall, and this is the second year in a row that New Jersey came in last. That’s according to CareScout’s 2026 ranking using data from the U.S. Census Bureau, the CDC, and the Tax Foundation. Consistently finishing last is a warning you shouldn’t ignore.
New Jersey has the highest property tax rates in the country, with an effective real estate tax rate of 2.33% that results in annual property taxes of approximately $9,345 for a home valued at $401,400. That’s nearly ten thousand dollars a year just to stay in your own home. The median New Jersey homeowner pays $9,358 annually in property taxes, according to Census Bureau data, making it the single worst state in the nation for property tax burden on retirees.
New Jersey’s average annual retirement income needed for a comfortable life is $77,684, with annual expenses for someone 65 or older at $64,736, and with an average retirement expected to last about 15.5 years, those looking to retire comfortably in New Jersey would need to have about $1.20 million saved. That’s a massive bar for the average American to clear. Inflation, rising housing and healthcare costs, and tightening benefit programs have squeezed savings in New Jersey, and about one-third of retirees in 2025 are cutting back on essentials like groceries and medical care just to make ends meet.
6. Connecticut: The Nutmeg State Squeezes Retirees from Every Direction
While Connecticut has a higher life expectancy than many other states, it is a financial burden to many retirees. The Nutmeg State is one of the few that taxes nearly all forms of retirement income and also has very high property taxes, with the median yearly property tax exceeding $6,000. That’s a double squeeze: you pay on income coming in, and you pay heavily just to stay in your home.
With yearly expenses averaging $66,543 per year for retirees, Connecticut’s average annual income requirement is $79,852, and with the average retirement lasting about 15.6 years, the average retiree needs approximately $1.25 million saved to live comfortably. Connecticut is also the only state in the country that charges a gift tax on assets residents give away while still alive. That last point is one most financial advisors mention almost in disbelief: you cannot even give money to your children without the state reaching into your pocket.
California, Connecticut, Massachusetts, New Jersey, New York, Rhode Island, Montana, and Vermont are among the worst states to retire in for taxes, factoring in tax rates on retirement income and property tax bills. Connecticut fits right in among that group. Connecticut currently uses a graduated estate tax with rates up to 12% in 2025, which means your estate faces a final tax hit even after you’re gone. For retirees hoping to pass something on to the next generation, that’s a painful reality check.
The Bigger Picture: Why Location Is a Retirement Decision, Not an Afterthought
Where you choose to retire can make a big difference in how far your money goes, especially since roughly two-thirds of non-retired adults say their retirement savings aren’t on track. The sobering part? Most people plan meticulously for how much to save, then spend almost no time planning for where to spend it. That’s a bit like training hard for a marathon and then showing up at the wrong starting line.
A recent AARP study found that 20% of adults ages 50 and older have no retirement savings at all, and 61% are worried they will not have enough money to support themselves in retirement. Against that backdrop, choosing to retire in a high-cost state isn’t just a luxury decision. It could mean the difference between financial stability and running out of money in your late seventies. On average, someone turning 65 today can expect to live nearly two more decades, according to the Centers for Disease Control and Prevention, making decisions about where and how to retire more consequential than ever.
The U.S. retirement system is already coming under immense strain, with Social Security program fund reserves expected to be depleted by 2035. Choosing a high-cost state in that environment is like playing retirement on hard mode. The contrast between places like Oklahoma and Hawaii is stark, with retirees in Hawaii requiring approximately $1.5 million more in savings than retirees in Oklahoma. That gap is not a rounding error. It is a retirement.
The numbers don’t lie: six of the most popular, most talked-about retirement destinations in America can quietly drain a lifetime of savings within ten years. If you’re planning your golden years, run the numbers hard before you fall in love with a zip code. What would you have guessed costs more: a decade in California or two decades in Mississippi? The answer might change everything.