Most people assume retirees travel cheap simply because they have more free time. That’s only half the story. The real secret isn’t the extra hours in the calendar – it’s a stack of small, almost boring financial habits retirees quietly build after decades of watching prices move.
Working travelers are stuck booking around a two-week vacation window, so they pay whatever the calendar demands that week. Retirees play a completely different game, and once you see how it works, you’ll wonder why nobody taught you this sooner.
The Real Reason Retirees Never Fly on a Friday
Retirees treat flexible dates like a financial weapon, not a lifestyle perk. Airfares and accommodations can often run 20% to 40% cheaper outside peak windows. That’s not a rounding error – that’s the difference between a $400 flight and a $650 one for the exact same seat.
Working people book around PTO, which almost always lands on weekends and holidays, the most expensive travel windows on the calendar. Retirees do the opposite on purpose. They use tools like Google Flights or Skyscanner to track fares and set alerts, then simply wait for the number to drop before they commit.
Retirees Chase “Shoulder Season” Like a Secret Weapon
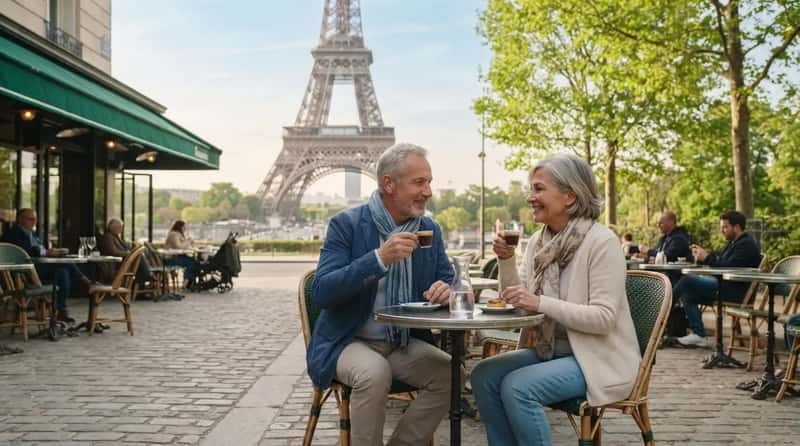
Ask any retiree about “shoulder season” and they’ll light up like you just said a magic word. On flexible schedules, traveling in these in-between windows can save hundreds or even thousands of dollars compared to peak tourist season. Working travelers rarely get this option because school breaks and summer PTO trap them into peak pricing year after year.
Traveling to France in springtime, for instance, means avoiding both peak summer crowds and harsh winter cold, landing on mild weather, thinner crowds, and lower prices all at once. Retirees aren’t smarter travelers. They’re just not fighting the entire country for a hotel room every single July.
The $80 Pass Most Working Americans Have Never Heard Of
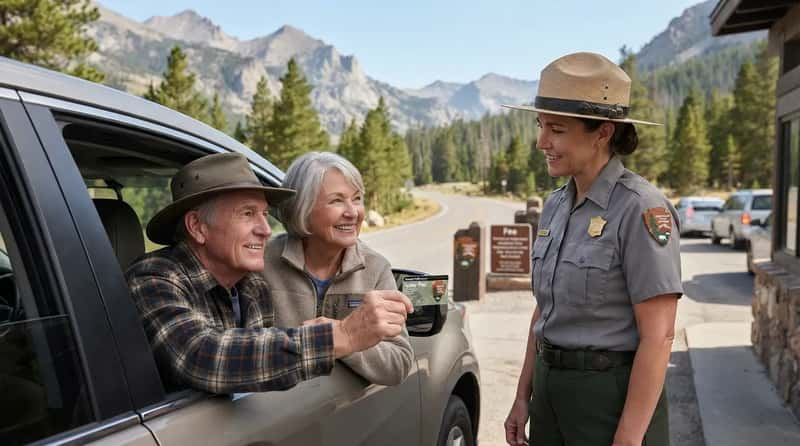
Here’s a number that stuns people who haven’t retired yet: the Senior Lifetime Pass – a one-time entry to every site in the national park system – costs only $80, and it’s available to U.S. citizens and permanent residents age 62 and older. One payment, and national parks are covered for the rest of that person’s life.
There’s also a cheaper annual version, a Senior Annual Pass for $20 a year, for retirees who aren’t ready to commit to the lifetime rate. Most working adults pay full entrance fees at every single park, every single visit, simply because nobody ever mentioned this pass exists.
Fast Facts
- Senior Lifetime Pass: $80 one-time fee, good for life
- Senior Annual Pass: $20, renews every 12 months
- Standard America the Beautiful Annual Pass, all ages: $80 per year
- Grand Canyon and Yosemite entrance fees run $35 per vehicle without a pass
- A single Senior Pass covers entry at more than 2,000 federal recreation sites
Why Retirees Still Ask for a Senior Discount Even Though Most Airlines Quietly Killed Them
This one causes actual arguments in comment sections, and for good reason. Senior airfare discounts are less common than they used to be, but some still exist. Retirees know the trick is to stop expecting an automatic discount and start asking directly instead.
Airlines like American, Delta, and United may offer select senior fares for travelers 65 and up on specific routes, but they’re rarely advertised publicly. The move retirees swear by is calling and simply saying “senior” or “AARP member” out loud, a step most working travelers never think to try because they’ve never had a reason to.
The Hotel and Rental Car Discounts Nobody Mentions at Checkout
This is where the savings get almost embarrassing for anyone who’s never asked. Marriott offers 15% off for guests 62 and up, and Best Western knocks off 5% or more for AARP members and seniors 55 and older. Working travelers booking the exact same room, on the exact same night, are often paying full retail without knowing a discount was one click away.
Rental cars follow the same pattern. Avis AARP members save up to 30% off base rates, while Budget AARP members save up to 35% off, plus extras like free upgrades. Nobody prompts you at the counter. You have to know to ask.
Quick Compare
- Marriott: 15% off for guests 62 and up
- Best Western: 5% or more off for AARP members and seniors 55+
- Avis: up to 30% off base rates for AARP members
- Budget: up to 35% off plus free upgrades for AARP members
Retirees Know Their Health Insurance Stops at the Border – Working Travelers Rarely Think About It
This is the one that trips up even seasoned travelers, and it’s the lesson retirees learn the hard way once they start crossing borders regularly. Medicare generally does not cover overseas care, except in a few limited border situations. An estimated 44% of Americans over 50 expect to travel internationally in 2025, yet most never budget for what happens if something goes wrong abroad.
Working-age travelers with employer health plans often assume coverage just “follows” them overseas. It doesn’t, and retirees have found that out the expensive way more than once. That’s why so many retirees now treat travel medical insurance as a non-negotiable line item, not an optional add-on, before booking anything international.
The Amtrak and Cruise Trick That Turns Slow Travel Into Cheap Travel
Retirees treat “slow” travel as a cost hack, not a compromise. Seniors 65 and up get 10% off most Amtrak fares, and 50% off on cross-border routes into Canada. Working travelers chasing the fastest, most direct option almost never see numbers like that.
Cruises follow a similar quiet pattern. On repositioning cruises, when a ship relocates from one region to another, senior fares tend to be especially competitive during off-season windows. These aren’t secret sailings. They’re just timed around the exact stretches working travelers can never get approved for time off.
Why Retirees Book Group Trips Working People Wouldn’t Consider
Here’s a controversial one: plenty of retirees now argue solo or couple-only travel is actually the most expensive way to see the world. They lean into group travel instead, coordinating with neighbors, fellow residents, or friends to unlock group rates individual travelers simply can’t access alone.
Working travelers, locked into rigid vacation windows, rarely have the flexibility to coordinate a group trip months out around someone else’s calendar. Retirees do, and it consistently shows up as lower per-person pricing on tours, cruises, and rail vacations that reward numbers over solo bookings.
Why It Stands Out
- Group block bookings often unlock lower per-person tour and cruise rates that solo or couple travelers can’t touch
- Splitting double-occupancy rooms across a group can help dodge the dreaded single-supplement fee entirely
- Bigger groups get more leverage negotiating private transfers, guided excursions, and multi-day rentals
- Retiree travel clubs can lock in off-peak departure dates that hold group rates even lower
The One Habit That Separates Retirees From Everyone Else: Patience With Prices
If there’s a single mindset shift that explains most of this, it’s patience, not luck, not connections, just time. Retirees track a price for weeks, sometimes months, before booking, waiting for the exact window when hotels and cruise lines get eager to fill unsold space during slower travel periods.
Working travelers, boxed in by limited PTO, often have to book on a deadline no matter what the price says. Retirees never have that deadline, so the price almost always comes to them instead of the other way around. It’s the single biggest, least glamorous advantage in retirement travel.
None of this comes down to one secret code or a hidden app. It’s a stack of small, unglamorous habits: flexible dates, shoulder seasons, a direct question at checkout, and the patience to wait a price out. Working schedules simply don’t allow for most of it. The gap isn’t really about age. It’s about who’s allowed to wait for the price to move – and who has to pay whatever the calendar demands.