Most people assume travel after 60 just costs more: more for comfort, more for coverage, more for peace of mind. In reality, a surprising number of those costs are discounted, optional or flat-out waived once you know the rule behind them. U.S. citizens and permanent residents who are 62 or older can buy a lifetime pass to national parks and other federal recreation sites for $80, and Europe’s new entry authorization is free for applicants over 70.1 2
Here’s the twist. The most expensive item on this list isn’t a fee anyone charges you. It’s one dollar figure tucked inside a common Medicare supplement benefit that sounds like overseas protection, and a single serious emergency can swallow all of it. It waits at #1, and it changes how everything before it looks.
#20 – The $78 PreCheck Fee Paid Just for Shoes
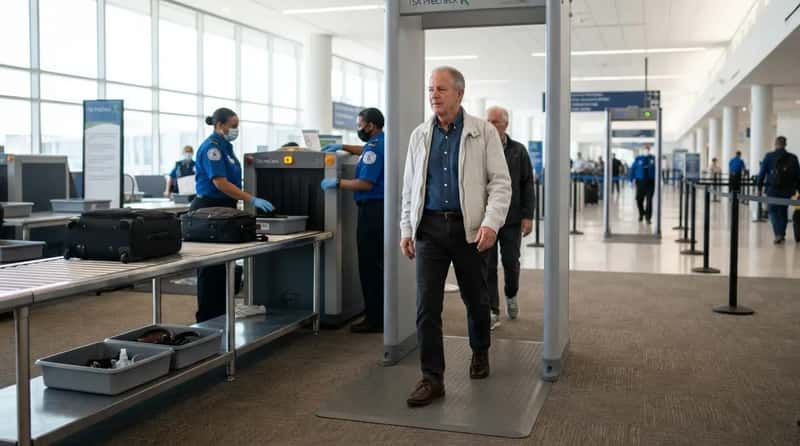
Plenty of travelers bought PreCheck mainly so their shoes could stay on, and that reason ended in the summer of 2025. TSA dropped its shoe-removal rule, so everyone, not just children and passengers 75 and older, can now keep shoes on at the checkpoint.3 Enrollment still runs roughly $78 to $85 for a five-year membership, depending on the enrollment provider.
What you’re paying for now is the rest of the lane: belts, light jackets, laptops and liquids stay in place. If you fly once or twice a year, skip the fee. If you fly monthly, the lane can still earn its keep.
Turn 75, though, and the screening rules change without any fee at all.
#19 – The Airport Screening Perk That Costs Nothing at 75
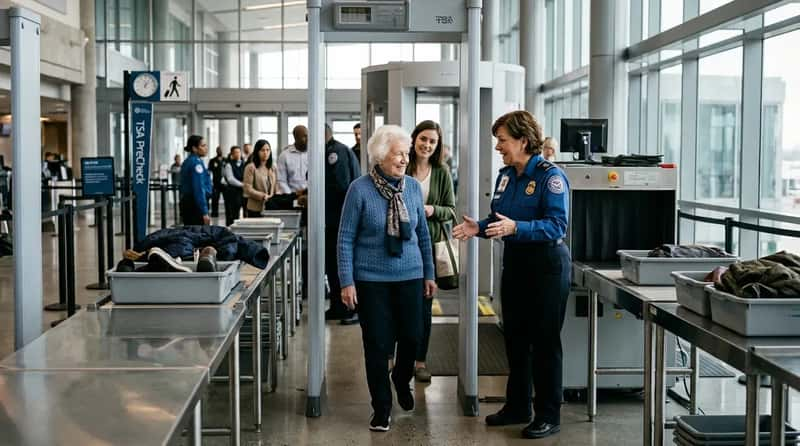
The birthday that matters at the checkpoint is 75, not 65 or 70. TSA gives passengers 75 and older expedited screening at the security checkpoint. There’s no application, no background check and no fee.
If the officer doesn’t offer it, say you’re 75 or older and ask for modified screening. The perk has limits, because if you alarm during screening, you may still have to remove your shoes or accept a pat-down. Even so, it’s a free benefit that plenty of 75-year-olds never think to ask for.
Getting through security is the easy part. The long walk to the gate is where some travelers still reach for their wallets.
#18 – Tipping Pressure at the Wheelchair Escort
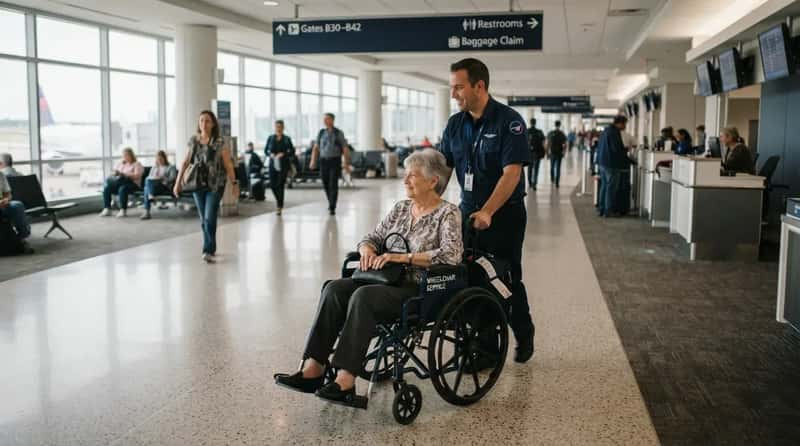
An attendant offers a ride to the gate, and you’re left wondering whether the service has a price. On flights to, from and within the U.S., airlines can’t charge you for wheelchair assistance under federal accessibility rules. The service itself is free.
A tip for the attendant is a kindness, not a fee. You also don’t need to be unable to walk to use it, because the terminal can be a long way from curb to gate. Request the help when you book, not at the curb, so it’s already on your reservation when you arrive.
Once you’re off the plane, the next savings are on city streets, where federal rules point toward a half-price fare.
#17 – Full Fare on the City Bus and Train
Transit agencies that take federal funding are generally required to offer half fare to riders 65 and older outside rush hour. That’s federal policy, but each city sets its own paperwork. Off-peak, riders 65 and up often pay half.
Some systems accept a Medicare card or driver’s license. Others want a local senior ID, and a few limit the discount to residents. Check the agency’s website before you land, and compare half-fare single rides against a day pass before you buy either. Rush hour is usually excluded, so a 5 p.m. commute may still cost full price.
Intercity trains have an age tier too, though it’s smaller than half off.
#16 – The Senior Fare Amtrak Riders Forget to Select
Ten percent isn’t a number that makes anyone cancel their plans, but it adds up over a round trip. Amtrak has long offered a discounted fare for riders 65 and older, generally around 10 percent on many routes. The tier starts at 65, not 62, so it arrives three years later than the park pass.
Choose the senior traveler type when you book, and carry photo ID. Discounts don’t always stack with promotional fares, so price the trip both ways. Whichever comes out lower wins, and on a cheap sale fare the senior discount may be worth nothing.
At a Glance: The Birthdays That Unlock Savings
- 62: eligible for the $80 lifetime national parks pass
- 65: Amtrak’s senior fare and off-peak half-fare transit
- 70: Europe’s entry authorization fee is waived (see #8)
- 75: TSA expedited screening at the checkpoint
Cards are the next place where a quiet 3 percent leak opens, and the fix has nothing to do with age.
#15 – The 3 Percent Added to Every Foreign Swipe
On $3,000 of hotels, meals and tickets abroad, a 3 percent foreign transaction fee adds $90. Many cards charge roughly that on purchases processed outside the U.S., while some charge nothing. Carry a card with no foreign transaction fee.
It’s the cheapest fix on this list, because it costs nothing but the time to read your card’s fee schedule. The fee can also show up on online purchases from foreign merchants, so the savings don’t stop at the airport.
Even with the right card, the terminal may offer a choice that looks friendly and isn’t.
#14 – The “Pay in Dollars” Button That Costs You
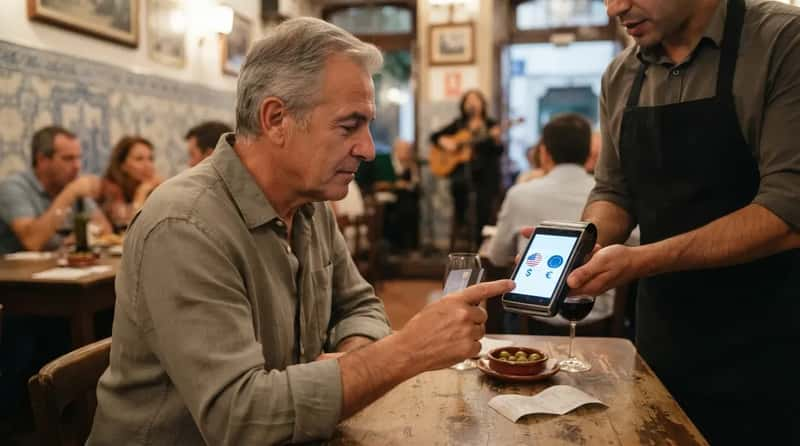
You’re at a restaurant in Lisbon, the card reader asks whether you’d like to pay in dollars or euros, and dollars looks easier. That prompt is called dynamic currency conversion. The merchant’s side sets the exchange rate, and it tends to be less favorable than your card network’s.
Always choose the local currency. That applies at hotels, shops and ATMs, even when a friendly clerk says the dollar option is simpler. A no-fee card from #15 only works in your favor if you let your own card do the converting.
Cash has its own version of this problem, and it starts at the arrival hall.
#13 – The Airport Currency Counter
The exchange counter right after customs is convenient, which is why it can get away with a weaker rate. Counters in airports typically give you less for your dollars than a bank ATM in town. Carry only enough cash for the taxi and a tip, and withdraw the rest locally.
Use an ATM attached to a bank, take out a larger amount less often so you pay fewer withdrawal fees, and decline the machine’s offer to convert the amount into dollars. Your own bank may charge a fee too, so a card that refunds ATM fees can pay for itself in a single trip.
Back on U.S. soil, the best deal on this list comes with a trap on the order form.
#12 – The Mail-Order Fee Tacked Onto an $80 Pass
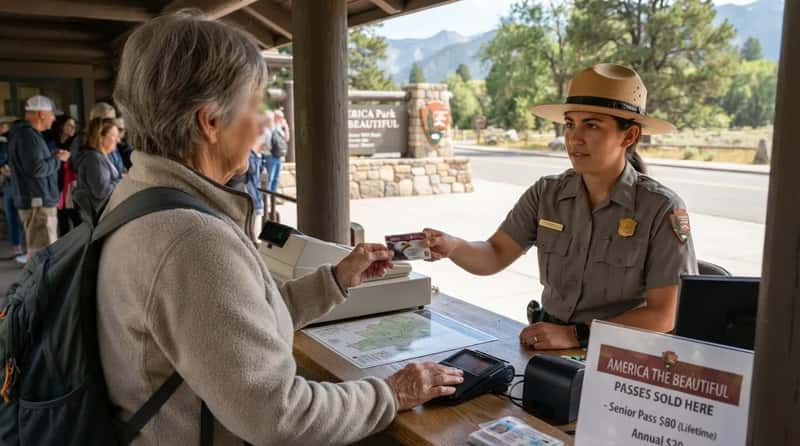
The Senior Pass is already a bargain, which makes this fee easy to overlook. Ordering a physical card online or by mail adds a processing charge on top of the pass price.4 Buying in person at a federal recreation site that sells passes avoids it.
In person it’s $80 for lifetime and $20 for annual.1 You’ll need documentation of age and residency or citizenship, so bring a driver’s license or passport. A digital version is also available through Recreation.gov, which suits anyone who’d rather keep the pass on a phone.
Before you buy the lifetime version, there’s a rule that lets you pay for it in $20 slices.
#11 – Paying $80 at Once When $20 Will Do
A senior who isn’t sure the parks will become a habit can start small. Each annual pass you turn in knocks $20 off the $80 lifetime price, even if it has expired, and four annual passes get you the lifetime pass for free. So the annual route costs the same $80 over four years, with no commitment up front.
Four $20 annual passes trade in for a lifetime pass. That makes the annual pass a free trial. Buy the lifetime pass outright only if you already know you’ll keep visiting, since the trade-in only pays off if you stay with it.
Once you hold the card, the gate attendant’s math matters, because the rules turn on the vehicle.
#10 – Per-Person Gate Fees for the Whole Back Seat
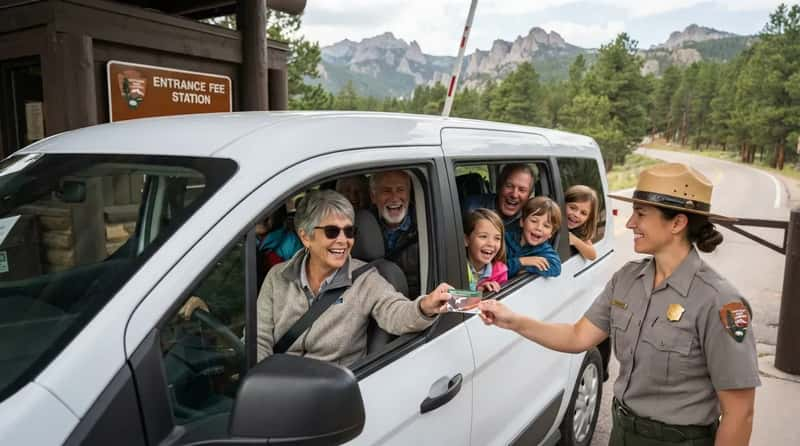
The pass is issued to one person, but the entrance booth treats the car as covered. At parks that charge per vehicle, the pass covers the pass holder and everyone in their private vehicle. That means grandchildren, friends and a neighbor along for the ride all get in on your card.
At sites that charge per person, the pass typically admits the pass holder plus up to three additional adults, and children under 16 are free at national parks anyway. One pass can cover every passenger in your private vehicle. Policies differ by site, so ask at the booth if you’re hosting a full van.
Quick Compare: Two Ways the Gate Counts Heads
- Per-vehicle sites: you plus everyone in your private vehicle
- Per-person sites: you plus up to three additional adults
- Kids under 16: free at national parks either way
The card also reaches past the entrance booth, into the campground.
#9 – Half-Price Campsites and Boat Launches
The entrance fee gets the attention, but the Senior Pass can also lower what you pay once you’re inside. It may provide a 50 percent discount on some amenity fees for services like camping, swimming and boat launches.4 The word to watch is “some,” because not every campground participates.
Ask at reservation time, or at the fee station, whether the discount applies. Some federal camping and boat-launch fees drop by half. If you camp for a week, that can matter more than the entrance fee.
Another free pass awaits across the Atlantic, with a catch: the form is mandatory.
#8 – Europe’s New Entry Fee, Waived After 70
Europe’s ETIAS travel authorization is a 20-euro charge for most adults. The fee was raised from 7 euros, but applicants who are under 18 or over 70 are exempt, though they still need an approved authorization. Over 70 means no fee, but you must still apply.2 5
The system isn’t running yet, and its launch date has slipped before, so watch for an official start date. Once it’s live, one authorization is tied to your passport and lasts up to three years, which covers multiple trips.
The next group isn’t a fee at all. It’s a bill that arrives from a foreign hospital.
#7 – The Assumption That Medicare Follows You Abroad
Your Medicare card works at every hospital back home, and it’s natural to expect that to carry over. It doesn’t. Original Medicare generally does not cover care outside the U.S., apart from a few narrow border exceptions.6 7 A broken hip in Rome is a bill you pay yourself unless another policy steps in.
Original Medicare generally pays nothing for care abroad. That’s the reason the next four items exist. Before a trip, find out which of your policies, if any, answers the question, and don’t leave it until you’re in an emergency room.
Worth Knowing: Who Actually Answers the Question
- Original Medicare: generally nothing outside the U.S., with narrow border exceptions
- Medicare Advantage: your plan’s own rules decide
- Medigap: depends on the plan letter
- Travel policy: check the evacuation benefit and medical limit
If you’re on a Medicare Advantage plan, the answer lives in a different document.
#6 – The Advantage Plan Clause Worth Reading
Medicare Advantage plans are private plans, and each writes its own rules. Some may cover emergencies abroad. Whether yours does depends on your plan, not on Medicare.
Your plan’s own paperwork decides, not Medicare. Look for the Evidence of Coverage booklet and check its section on emergency care outside the U.S. Pay attention to whether you’d have to pay first and file for reimbursement, since that can mean putting a large bill on a credit card.
If you have a Medigap policy instead, one letter in its name decides whether you get a foreign benefit at all.
#5 – Six Medigap Letters That Cover Emergencies Abroad
Medigap Plans C, D, F, G, M and N include a foreign travel emergency benefit, and Plans A, B, K and L do not. Covered emergency care is paid at 80 percent after a $250 deductible, up to $50,000 lifetime.8 Check which letter is on your policy before you book.
If you hold Plan C or F, you’re among a closing group: those plans are open only to people who first became eligible for Medicare before January 1, 2020. Plan G, which new enrollees can buy, carries the same benefit. If a friend says “my Medigap covers me overseas,” ask which plan letter, because the answer isn’t the same for all of them.
Having the right letter still leaves you with a share of every bill, and the math is less friendly than “80 percent” sounds.
#4 – The $2,200 Left From a $10,000 ER Bill
Run the numbers on a hospital bill abroad. On a $10,000 emergency room bill, you would pay the first $250, then 20 percent of the remaining $9,750, or $1,950. Add the two and you’re out $2,200 even with the benefit in place.
The deductible works in your favor over several trips: it resets once a year, not once a trip, so three international trips in the same calendar year cost you the $250 only once. Plan for $2,200 out of pocket on a $10,000 bill. Ask the hospital for an itemized bill and your records before you leave, since a claim usually needs them.
The benefit also runs on a clock, and it’s measured from the day you leave home.
#3 – The 60-Day Clock That Starts at Takeoff
A three-month trip is where this one bites. Medigap’s foreign benefit applies to emergency care that begins during the first 60 days of your trip.8 If you’re a snowbird abroad, on a long cruise, or visiting family for a season, an emergency in week ten may fall outside it.
Care that begins after day 60 of a trip falls outside the benefit. For trips longer than two months, a separate policy that starts on the day you leave is the safer fit. This is also where the deductible from #4 and the clock work differently, since the deductible resets yearly while the 60 days start fresh with each trip.
Quick Compare: What Resets and What Never Does
- $250 deductible: resets once each calendar year
- 60-day window: starts fresh with every trip
- $50,000 cap: a lifetime limit that never resets
Even inside the 60 days, the benefit pays for treatment, not the flight home, and that second bill can be larger.
#2 – The Flight Home Medigap Won’t Pay For
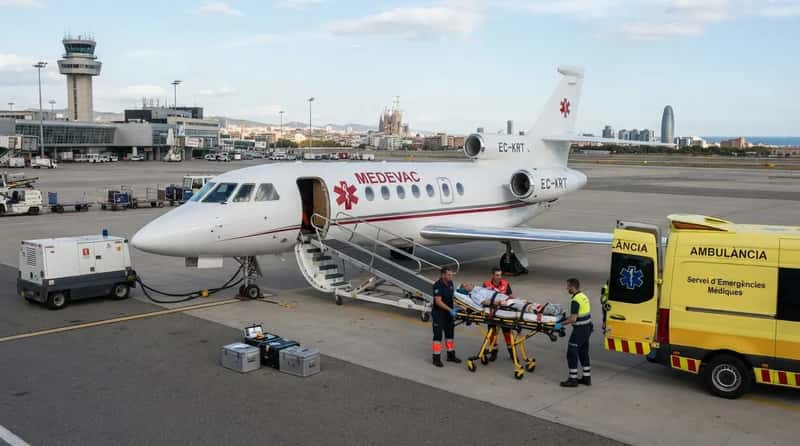
Suppose you have a stroke in Barcelona and your family wants you back in a U.S. hospital. Medigap’s foreign travel benefit pays for emergency medical care itself, not transport back to the United States.6 8 Medical flights can run to tens of thousands of dollars.
Standalone travel policies can fill that gap. Many include emergency evacuation and per-trip medical limits that can reach into the six figures, depending on the policy. Look for “emergency evacuation” and the medical limit on any travel policy before you buy. For anyone who leaves the country more than once, Medigap works best as a backstop, with a separate policy doing the heavy lifting.
One number inside the Medigap benefit never resets, no matter how careful you are.
#1 – The $50,000 Cap That Follows You for Life
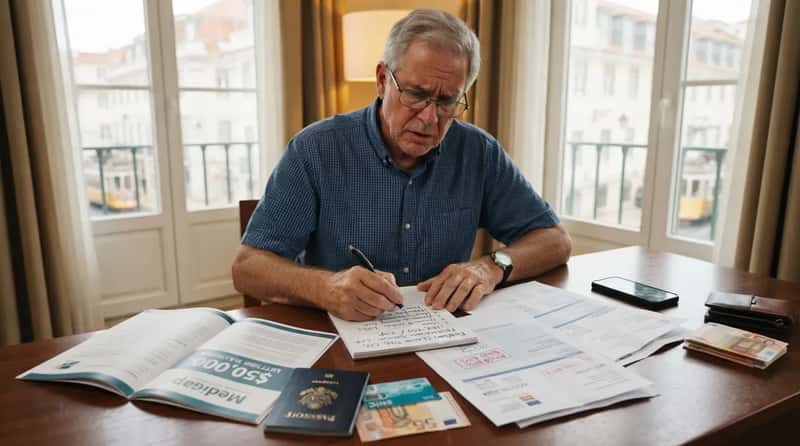
It’s easy to read $50,000 as a per-trip limit, and it isn’t. Coverage is capped at a $50,000 lifetime maximum, combined across every trip you ever take. Once you reach it, your Medigap plan won’t pay for any further foreign emergencies for the rest of your life under that policy.
Because the plan pays 80 percent, the cap is reached sooner than the number suggests. A single emergency bill of about $62,750 would use all of it: the $250 deductible, plus $62,500 in covered charges at 80 percent. A serious illness or injury abroad can easily exceed that. The $50,000 is a lifetime limit, not a per-trip limit.
Most of these expenses were never unavoidable. They were left on the table because nobody asked the right question at the right desk. The park pass, the half fare, the free authorization and the no-fee card all take a few minutes to claim, while the medical items take one phone call to your insurer.
The small savings are worth having. The medical rules are worth more, since that’s where a single gap can cost more than every discount here combined.
So the next time a trip gets booked, the best money move might be the quietest one: reading the fine print before the suitcase comes out.
- NPS Entrance Passes: https://www.nps.gov/planyourvisit/passes.htm
- ETIAS Official FAQ: https://travel-europe.europa.eu/etias/faq
- AARP TSA Shoe Policy: https://www.aarp.org/travel/travel-tips/tsa-shoe-policy/
- NPS America the Beautiful Passes: https://www.nps.gov/band/planyourvisit/america-the-beautiful-pass-series.htm
- AARP ETIAS Fee Guide: https://www.aarp.org/travel/travel-tips/etias-application-and-payment-information/
- Medicare Travel Outside U.S.: https://www.medicare.gov/coverage/travel-outside-the-u.s.
- NCOA Medicare Abroad: https://www.ncoa.org/article/does-medicare-cover-you-anywhere/
- Medigap Foreign Travel Benefits: https://www.medicarefaq.com/blog/understanding-medigaps-foreign-travel-benefits-whats-really-covered/