Most Americans dream of a retirement free from financial stress, yet the reality is far more complicated than just hitting a savings number. The average amount of savings required to retire comfortably in the United States is $904,452, and among all 50 states, the savings required to retire comfortably ranges between $617,661 and $1.84 million. That means where you retire matters just as much as how much you’ve saved. For Americans sitting on $500,000 in retirement savings, choosing the right state isn’t just smart planning – it could be the difference between comfort and running out of money entirely.
1. Mississippi – The Most Budget-Friendly State in the Nation
Mississippi has the lowest average retirement income required to live comfortably of any state, at $53,710 per year, with annual expenses coming out to only $44,758 per year. Those numbers are remarkably lean compared to the national picture, and they mean $500,000 can stretch considerably further here than almost anywhere else. $1 million would last the longest in Mississippi at around 22 years, and the Magnolia State also ranked as Bankrate’s fifth best state to retire due to its affordability and weather.
Mississippi rises to the top as one of the most economically retirement-friendly states, with its low cost of living, affordable healthcare, and budget-friendly housing making it an ideal choice for retirees looking to stretch their dollars. On the healthcare side, assisted living in Mississippi can cost less than $55,000 per year, a fraction of what retirees pay in expensive coastal states. Mississippi does not tax pension income at all, which adds another meaningful layer of protection for retirees living on a fixed income.
2. Oklahoma – Rock-Bottom Housing and a Shrinking Tax Burden
With average annual expenses coming out to only $45,016 for someone 65 years or older, the average retirement income required in Oklahoma is $54,019, and someone looking to retire in Oklahoma would need to save for about 13.4 years of retirement, coming out to roughly $723,859 in savings. That’s a relatively modest total, which means $500,000 paired with Social Security income can go a very long way. The contrast between Oklahoma and Hawaii is stark – retirees in Hawaii require approximately $1.5 million more than in Oklahoma, with housing costs in Oklahoma City running 43.1% below the national average.
Retirees on a budget often find some of the best value in Oklahoma, where average annual retirement costs remain around $50,000 annually, with the state benefiting from significantly lower housing prices, modest property taxes, and minimal day-to-day expenses. Kansas approved legislation eliminating state income tax on Social Security for all income levels starting with the 2024 tax year – and Oklahoma has followed a similar affordable trend. For retirees who are low on savings or want a lower cost of living, Oklahoma is consistently flagged as one of the top states to consider.
3. Alabama – Southern Charm With Serious Tax Advantages
For the average retiree in Alabama to live comfortably, they will need an income of $55,258 per year. That keeps Alabama firmly in the most affordable tier of states for retirement. Cities such as Birmingham, AL are among the best places for renters to retire, with quality hospitals and doctors, plenty of green space, and retiree-friendly amenities. The combination of low daily costs and strong community infrastructure makes Alabama a quietly compelling choice for retirees managing modest nest eggs.
Alabama does not tax pension income at all, which is a significant financial advantage for retirees drawing from defined-benefit plans or other pension sources. Alabama also remains among the states with the lowest effective property tax rates in the country, sitting at roughly 0.3 to 0.4 percent. For retirees who own their home outright, that combination of low property taxes and zero pension taxation can preserve thousands of dollars annually that would otherwise go to the state government.
4. Kansas – Grocery Tax Gone, Social Security Tax Gone
The Motley Fool’s analysis ranked Kansas among the most affordable states for retirees based on overall cost of living scores. Recent legislative changes have made it even more attractive. The state previously taxed groceries but began phasing out the tax in 2023 and eliminated it entirely in 2025 – a real-world savings that benefits retirees on fixed incomes every single week. Kansas now exempts all Social Security income from state taxes, and public pension income is also exempt.
The median effective property tax rate in Kansas is 1.25%, which is higher than the national median, but when taking into account the relatively low property values in Kansas, taxes paid are not especially high, with the typical Kansas homeowner paying $2,983 annually in property taxes. That keeps actual out-of-pocket housing costs manageable. Seniors who own and live in their home in Kansas may also be eligible for a number of tax relief programs, including the homestead refund. These layered benefits make Kansas a state where $500,000, combined with Social Security, can realistically provide a comfortable lifestyle for decades.
5. Missouri – Full Social Security Exemption and Below-Average Property Taxes
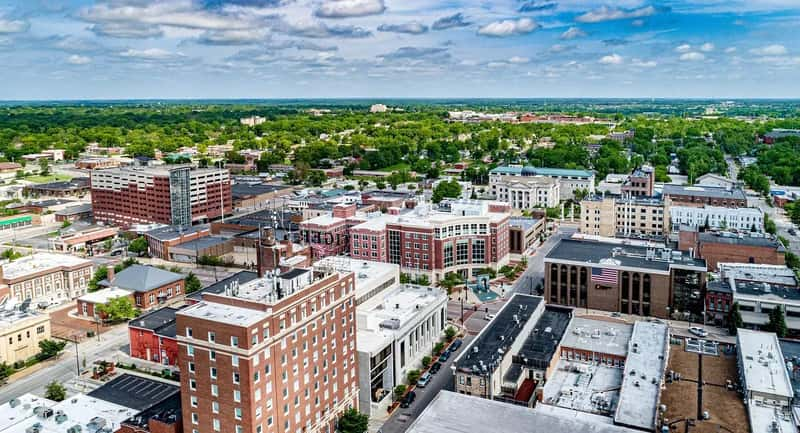
Missouri has the fourth-lowest average annual retirement income required to live comfortably at $54,701 per year, only a few hundred dollars higher than Arkansas and Oklahoma, with the average retirement age at 63 years and a life expectancy of 77.1 years – meaning about 14.1 years of retirement requiring roughly $771,281 in savings. Missouri’s low cost profile makes it one of the more underrated retirement destinations in the Midwest. Its four major cities – Kansas City, St. Louis, Springfield, and Columbia – all offer medical centers, cultural amenities, and accessible public services at a fraction of the cost found in coastal metros.
Beginning in 2024, Missouri completely eliminated its taxes on Social Security benefits, a major win for retirees whose income relies heavily on those monthly checks. Social Security benefits in Missouri are now fully exempt from taxes, and while the state has combined state and local sales tax rates higher than the national average, property taxes remain below the national average. For 2025, the state also allows those with public pension income to deduct up to $48,000, further lightening the tax load for many retirees.
6. Tennessee – No Income Tax, Low Housing, and a Thriving Retirement Scene
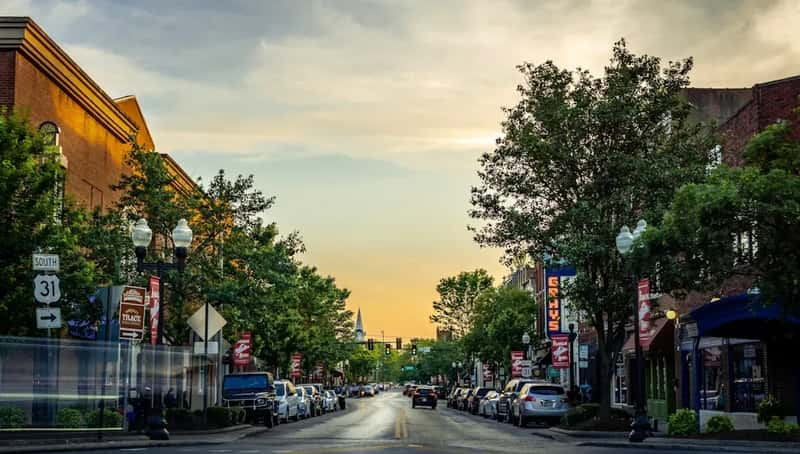
With yearly expenses amounting to about $45,894 per year, Tennessee’s average retirement income is $55,072, with the average person retiring at 64 years old and average life expectancy at 76 years – meaning to live comfortably through these roughly 12 years of retirement, one should plan to save at least $660,870. That target is reachable for many Americans, and $500,000 paired with regular Social Security payments gets retirees very close to covering the gap. Tennessee has no income tax, meaning Social Security benefits, retirement account withdrawals, and other income face no state income tax burden whatsoever.
Tennessee is a prime example of an affordable retirement destination – Nashville offers no state income tax plus a median home price of about $386,000, well below prices in major coastal cities, while still providing access to city-level amenities. The Motley Fool’s analysis ranked Tennessee as the most affordable state for retirees based on overall cost of living scores, putting it at the very top of the budget-friendly retirement list. Tennessee also does not tax pension income at all, meaning retirees with any pension component to their income keep their full benefit without state deductions cutting into it each year.