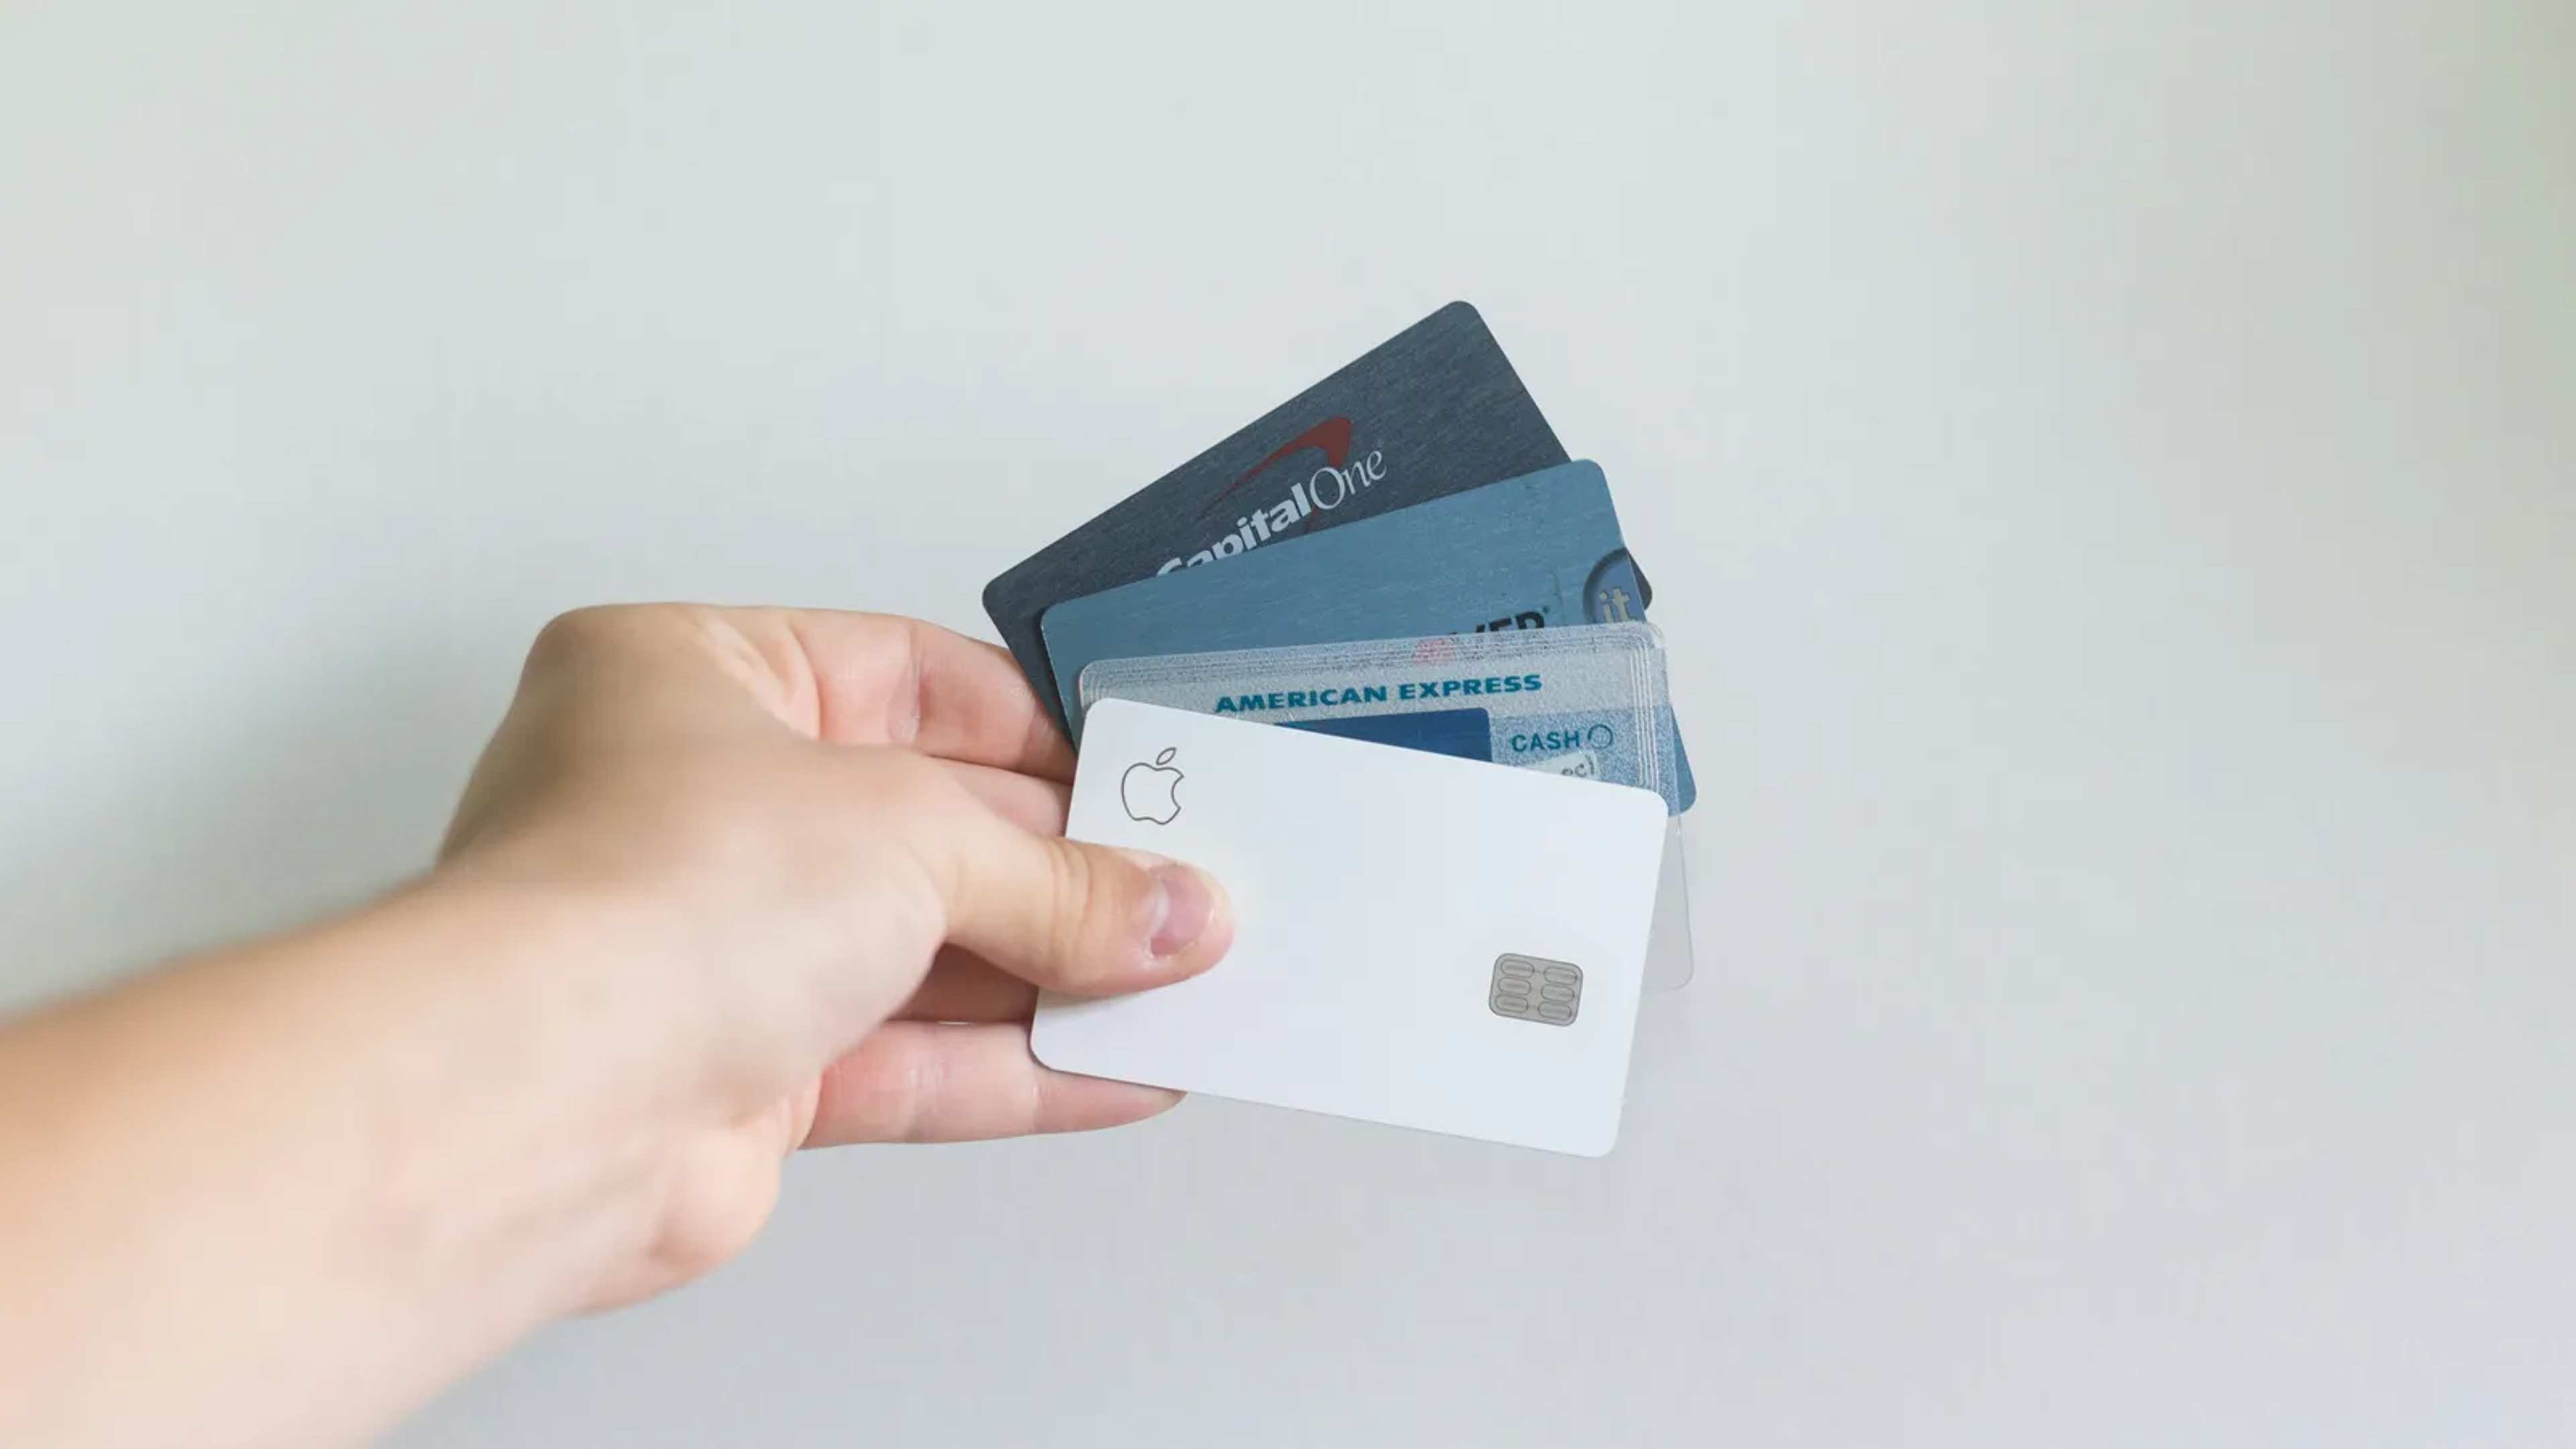
Many travelers reach the point where an annual fee on a rewards card no longer seems justified. Closing the account appears straightforward, yet issuers often allow a different step that keeps the relationship intact. Downgrading or product-changing a card can reduce or eliminate the fee while preserving account history and rewards access. The choice carries direct consequences for credit scores and future bonus eligibility.
The Core Distinction That Affects Long-Term Outcomes
Downgrading moves a card to another product within the same rewards family, typically one with a lower or zero annual fee. The account remains open on credit reports, so the length of credit history stays unchanged. Product changes go further by switching to an entirely different rewards currency, still without closing the account. Canceling, by contrast, ends the relationship permanently and can shorten average account age.
Issuers treat these moves as internal adjustments rather than new applications. This distinction matters because it avoids the hard inquiry and new account reporting that accompany fresh cards. Travelers who fly or stay with one loyalty program frequently find downgrades sufficient to retain miles or points earning without the original cost.
How the Options Compare in Practice
| Option | Annual Fee Result | Credit History | Rewards Continuity | Future Bonus Risk |
|---|---|---|---|---|
| Downgrade | Lower or zero | Preserved | Same family | Usually low |
| Product change | Lower or zero | Preserved | New currency | Moderate |
| Cancel | Eliminated | Shortened | Lost unless transferred | Variable |
The table illustrates why many cardholders explore the first two routes before closing an account. Banks such as Bank of America and Citi have supported product changes across different rewards programs, while airline issuers commonly allow downgrades within their own families.
Timing and Eligibility Constraints
Issuers generally discourage changes or closures within the first twelve months of card ownership. Early action can affect introductory bonus terms and may trigger questions during retention calls. Some programs impose limits on the total number of cards a customer may hold, making closure necessary before new applications if the maximum has already been reached.
American Express policies add another layer: prior ownership of a product, even after a change, can restrict eligibility for new welcome offers. Travelers planning multiple cards in a single year therefore weigh these rules before requesting any adjustment.
Protecting Points, Perks, and Credit Standing
Points already transferred to a loyalty program remain safe regardless of the card decision. Points still sitting in the issuer’s program can disappear if no other card earns the same currency. Benefits such as lounge access or companion certificates require careful review, because downgrading may remove them even when the annual fee drops.
Credit scores reflect both the age of accounts and the mix of credit types. Keeping an older travel card open through a downgrade maintains that history. Closing the card removes the positive payment record and can lower the average age of accounts across all credit lines.
Next Steps for Cardholders Facing Renewal
Review the specific downgrade or product-change options listed on the issuer’s website or by calling customer service. Prepare a short list of acceptable retention offers in advance. Confirm that any remaining balance is paid before the change takes effect, then monitor the account for thirty days to catch any unexpected charges.
Each annual cycle brings the same decision point. Travelers who treat downgrading and product changes as standard tools rather than last resorts often maintain stronger credit profiles and continued access to rewards without repeated annual fees.