Walk through any suburb built between 1975 and 1995 and you’ll see them: sprawling colonials and split-levels with four bedrooms, a two-car garage, and a dining room table that hasn’t sat more than two people on a regular Tuesday in years. The kids are grown, scattered across other cities, and the house that once felt too small now feels strangely oversized.
What used to be described as a reward for decades of work is starting to look, on paper at least, like a different kind of burden. The house is still standing, still valuable, still full of memories. But the math behind keeping it has quietly shifted, and millions of boomers are discovering that the forever home comes with strings attached that nobody mentioned at the closing table.
The empty nest paradox: too much house, too few people
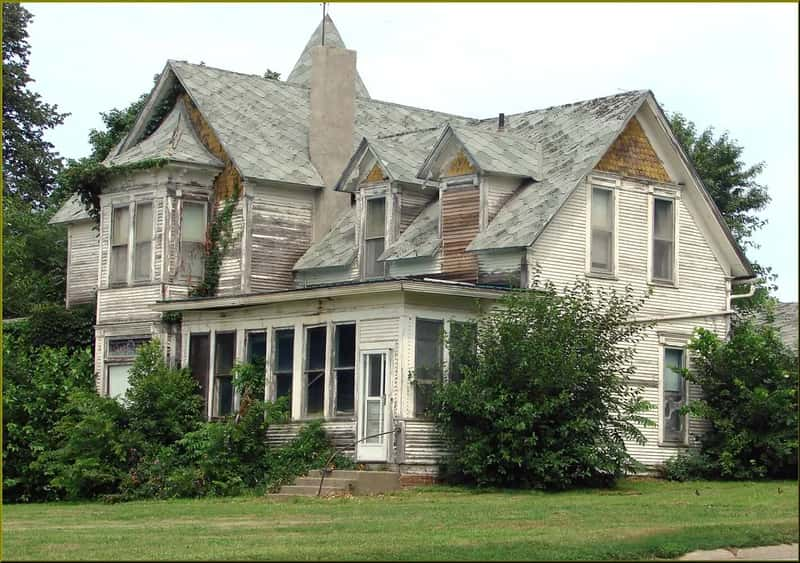
The scale of this mismatch is easy to overlook until you see the numbers side by side. Empty-nest boomers hold 28% of the country’s large homes while millennial families with children hold just 16%.[1] That gap exists in nearly every major metro area in the country, not just a handful of retirement hotspots.
In Memphis, the divide is especially stark. Empty-nest baby boomers own 31.2% of the metro’s three-bedroom-plus housing stock, the highest share in the Redfin analysis, while millennial families with children own just 15.3% of large homes in the area.[1] Cleveland, Buffalo, and Richmond show nearly identical patterns, which suggests this isn’t a regional quirk. It’s a structural feature of how the housing market aged alongside the generation that built so much of it.
The math that no longer adds up
For years, staying put looked like the obvious financial choice. Many boomers bought their homes decades ago at a fraction of today’s prices, and a large share carry no mortgage at all. Nearly three in five baby-boomer homeowners carry no loan balance at all, removing the financial incentive to sell and taking those properties off the market.[1]
The problem is that a paid-off mortgage doesn’t erase property taxes, insurance, utilities, or the roof that eventually needs replacing. A four-bedroom house built for a family of five still requires heating five bedrooms, mowing a full lot, and maintaining square footage that two people simply don’t use anymore. The bills scale with the house, not with the number of people living in it, and that disconnect is where the “liability” framing starts to make sense.
Falls, stairs, and the hidden safety risk
A four-bedroom forever home usually means two stories, a finished basement, or both. That layout made sense when kids were running up and down the stairs every day. It makes considerably less sense for someone in their seventies managing balance issues or early arthritis.
The safety numbers back this up. Four in five deaths related to hip fractures among older adults are caused by falls.[2] Stairs, uneven thresholds, and multi-level bathrooms are exactly the features that define a classic four-bedroom colonial, and they’re also exactly the features that turn a familiar house into a genuine physical risk as mobility changes.
The renovation bill nobody budgets for
Staying in a large home as you age isn’t free, even once the mortgage is gone. Aging-in-place remodeling costs range from $3,000 to $15,000, with a national average of $9,500.[3] That’s often just the starting point, not the ceiling.
Bigger projects push the bill much higher. A curbless walk-in shower alone can run $3,000 to $15,000 for a bathroom-first project, where most home falls happen, followed by entry and mobility upgrades over time as needs change.[4] Add a stair lift, wider doorways, or a residential elevator, and a whole-home retrofit can climb well past fifty thousand dollars, an expense many retirees never planned for when they first bought the place.
Why boomers aren’t selling anyway
Given all of this, you might expect a wave of boomers listing their homes and moving into something smaller. That wave has been remarkably slow to arrive. Just 10% of boomers plan to sell within the next five years, down from 15% in 2024, meaning that 90% of the homes owned by this generation won’t hit the market until the 2030s.[5]
Part of the reluctance is emotional, part is purely practical. There’s often nowhere obvious to go. There is a shortage of smaller, affordable homes that would enable older Americans to downsize, and elevated home prices and mortgage rates continue to price out younger buyers attempting to enter or move up the housing ladder.[6] Selling a paid-off house only to face a smaller inventory of overpriced condos doesn’t feel like an upgrade to most people in their seventies.
The silver tsunami that turned into a trickle
Housing economists have talked about a coming “silver tsunami” for the better part of a decade, the idea that aging boomers would eventually flood the market with inventory. So far, that flood hasn’t materialized in the way it was predicted. Instead, seniors are holding onto homes longer, and an increasing share of properties are skipping the market entirely.[7]
Inheritance data tells much of the story. About 340,000 U.S. properties were transferred through inheritance in the 12 months ending in August 2025, representing 7% of all property transfers, the highest share the firm has recorded.[8] Rather than being listed for sale, many of these homes are simply passed down and kept in the family, which does little to loosen the housing market for younger buyers who need the space.
Maintenance, upkeep, and the deferred decay problem
A four-bedroom house doesn’t stay in good shape on its own. Roofs, furnaces, plumbing, and foundations all have a shelf life, and for older homeowners on fixed incomes, deferred maintenance is often the path of least resistance. That’s a quiet but real risk, because small problems compound into expensive ones the longer they sit.
Older housing stock adds another layer to this. In the top 100 metro areas, markets with larger shares of older home owners also tend to have older housing stock, and these homes are unlikely to be direct substitutes for newer construction, as when they enter the market, many may require significant renovation and, in some cases, redevelopment.[9] In other words, when these houses do eventually change hands, buyers often inherit a renovation project along with the deed.
The emotional weight of downsizing
None of this is purely financial. A four-bedroom home isn’t just square footage; it’s decades of birthdays, holidays, and a specific creak on the third stair that everyone in the family knows by heart. Letting go of that is genuinely hard, and it’s a mistake to treat the decision as a spreadsheet exercise.
Sorting through a lifetime of accumulated belongings is often the actual bottleneck, more than the real estate transaction itself. The physical and emotional effort of clearing out a house filled with decades of memories stops many people before they even list the property, regardless of how sound the financial argument for moving might be. That resistance is understandable, even if it works against the broader housing market’s need for more inventory.
What happens to these houses next
The generational handoff is coming, even if it’s arriving slower than expected. The number of older owner-occupants who exit homeownership between 2026 and 2036 is projected to total between 13.1 million and 14.6 million, an increase of at least 42 percent over the number of older homeowners who exited during the last ten years.[10] That’s a meaningful shift, just one spread across a decade rather than concentrated into a single dramatic moment.
What’s less certain is where those homes go once they change hands. Most of these homes are staying off the open market, as many heirs are moving in themselves or holding onto them as long-term family assets, reinforced by state tax structures that preserve lower property tax assessments if they occupy inherited homes as primary residences.[11] That pattern means the four-bedroom forever home doesn’t disappear so much as it gets passed to a new owner who inherits the same maintenance bills and layout challenges.
Signs it might be time to reconsider the forever home
Not every large home is a liability, and not every boomer needs to move. But certain signals tend to repeat: a growing list of postponed repairs, bedrooms that have become storage rooms, and a set of stairs that feels a little riskier every winter. Utility and property tax bills that keep climbing while usable living space shrinks are another quiet warning sign.
The decision doesn’t have to be all or nothing either. Some homeowners choose targeted aging-in-place upgrades instead of a full move, tackling the bathroom first since that’s where most home falls happen, then adding entry ramps or a stair lift later as needs change. Others decide the smarter long-term move is downsizing into something single-level, even if the current shortage of small, affordable homes makes that search harder than it should be.
The bigger picture
The four-bedroom forever home was designed around a version of family life that, for most boomers, ended years ago. What remains is a structure built for a household that no longer exists, paired with costs, risks, and upkeep that scale with square footage rather than with the number of people actually living there. That disconnect is quiet, easy to ignore day to day, and genuinely expensive to unwind once mobility, maintenance, or money force the issue.
For now, most of these homes will stay exactly where they are, occupied by the people who raised families in them, waiting on a decision that keeps getting deferred. Whether that deferral is wisdom or avoidance probably depends on the house, the stairs, and how honest the person living there is willing to be about both.