For nearly two decades, Florida felt like the finish line. No state income tax, endless sunshine, a beach never more than an hour away. I bought my condo near the Gulf Coast fully expecting to grow old there, watching sunsets from my lanai until I couldn’t climb the stairs anymore. Then the bills started arriving, and the math simply stopped working.
I’m not alone in this. Thousands of retirees across the state have watched their fixed incomes get swallowed by rising premiums, property taxes, and everyday costs that climbed faster than almost anywhere else in the country. Selling my home and moving abroad wasn’t a dramatic act of rebellion. It was arithmetic. And two years into life overseas, I can say without hesitation that it was the right call.
The Insurance Bill That Changed Everything
The moment I knew I couldn’t stay came with my homeowners insurance renewal notice. My premium had crept up steadily for years, but the jump that finally broke my budget was staggering. Retirees across the state have reported similar shocks, with some homeowners watching a $620,000 paid-off home go from roughly $4,200 in 2020 to over $14,200 by 2026. That is not a rounding error. That is a second mortgage showing up out of nowhere, on a house that was already paid off.
I wasn’t imagining the trend either. Statewide, average annual property insurance premiums reached $2,794 through 2025, up 63% since 2020, and when you add rising property taxes on top, annual housing-related costs can exceed $10,000 for many homeowners. On a fixed Social Security check, that kind of increase doesn’t just pinch. It rewrites your entire budget overnight.
It Wasn’t Just Insurance, It Was Everything
Insurance was the loudest alarm bell, but it wasn’t ringing alone. A Florida TaxWatch report found that while prices rose modestly through the 2010s, the rate of increase has surged in the 2020s, jumping from about 1.3% annually to roughly 5.8% per year. That’s nearly a fivefold acceleration in the pace of everyday price hikes, hitting rent, groceries, utilities, and childcare costs for younger relatives all at once.
Rent tells a similarly brutal story for anyone who didn’t own outright. Florida’s average rent climbed from $1,194 in 2015 to $2,208 in 2025, an 85% increase over the decade, pushing the state from the 14th most expensive rental market in the country to the sixth. I wasn’t renting, but I watched friends in my building get priced out of their own neighborhoods. It’s no surprise that nearly 90% of Floridians surveyed in 2025 said they were concerned about inflation, and about half reported considering moving out of the state because of rising costs. I was simply one of the ones who actually went through with it.
Weighing the Alternative: Staying and Adapting
Before I made any decision, I looked seriously at whether I could just adapt in place. Financial advisors often suggest moving inland, and there’s real logic to it. Homes further from the coast tend to sit outside the riskiest wind zones, and premiums commonly fall 60% to 70% once you leave the wind-pool zone, with the sale of a coastal home sometimes able to fund a smaller inland house outright with cash left over.
It’s a sound strategy for plenty of people, and I don’t think less of anyone who takes that route. But for me, moving forty miles inland still meant staying inside the same insurance market, the same property tax structure, and the same overall cost trajectory. I wanted a change that actually solved the underlying problem rather than just softening the blow for a few more years.
Why I Started Looking Overseas
I started reading everything I could find about American retirees living abroad, and the pattern was consistent. The sharp rise in living costs in the US has become one of the strongest drivers of retirement migration, and for retirees who rely largely on Social Security, the average check of around $1,976 barely covers basic needs domestically but can provide a comfortable life abroad. That single fact reframed the whole decision for me. My income wasn’t shrinking. The cost of staying put was simply growing faster than it could keep up with.
I also learned I wasn’t part of some tiny fringe movement. Retirement migration research groups now describe what’s happening as a genuine trend rather than an anomaly, noting that cost of living is no longer just an economic parameter but a central element of retirement security strategy, and that low-cost countries are about sustainable life planning rather than simply chasing savings. That reassured me. I wasn’t running from something. I was planning toward something.
Choosing Portugal Over the Other Options
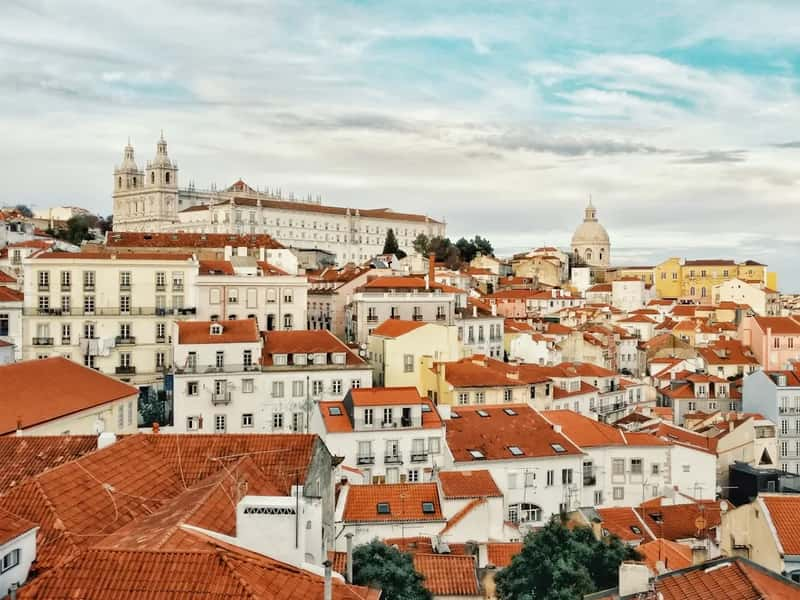
I looked hard at Mexico, Panama, and Costa Rica before landing on Portugal, and each had genuine appeal. Mexico remains hugely popular with Americans, and it’s still the top choice for a lot of American retirees looking abroad because it’s close to home, things work pretty much as expected, and the money goes incredibly far. Panama’s Pensionado visa program is famously generous too, and towns like Boquete draw enormous expat populations.
What tipped me toward Portugal was the combination of safety, healthcare, and an established American community. The country ranks seventh in the 2025 Global Peace Index, reflecting its high level of societal safety, low violent crime, and stable international relations, and by 2024, 19,258 US citizens lived in the country, giving new American retirees access to familiar networks and a smoother adjustment period. I wasn’t looking to disappear into total isolation. I wanted a soft landing, and Portugal offered one.
The Cost Difference Is Not Subtle
People sometimes assume the savings from moving abroad are marginal, a few hundred dollars a month at best. That has not been my experience at all. According to cost-of-living comparisons, the cost of living in Lisbon, including rent, runs 30 to 50% lower compared to places like New York City or San Francisco, and outside the capital in regions like the Algarve, the gap widens even further, with rents running around 60% lower and groceries roughly 40% cheaper compared to US cities.
For context on just how far a fixed income can stretch elsewhere, research groups tracking retiree spending found that Americans over 65 spent roughly $5,119 per month in 2024 inside the US, while popular retirement destinations abroad cut that figure by 34% to 71%, translating to tens of thousands of dollars saved every year. I didn’t need to cut corners or live frugally to feel that difference. I just needed to leave.
Healthcare Abroad Surprised Me the Most
I expected to sacrifice quality of care for lower costs, and that assumption turned out to be completely wrong. In Portugal and similar countries, private specialist visits and procedures cost a fraction of American prices, and routine specialist appointments might run 50 to 100 euros privately, with surgeries or advanced treatments costing a fraction of US prices, leaving many Americans astonished they can finally afford procedures they’d postponed at home.
Once you become a legal resident, the benefits go even further. Retirees in Portugal generally report excellent care and modern facilities with much lower medical bills, and once legally resident, can access public healthcare virtually for free. I’ve since had two procedures done that I’d been putting off in Florida for years simply because I dreaded the bill. Neither came close to what I would have paid back home.
What I Actually Miss About Florida
I want to be honest here, because this isn’t a story about a place being all bad. I miss certain grocery brands. I miss being able to call a friend and drive over the same afternoon instead of coordinating a six-hour time difference. I miss the easy, low-effort version of English-language everything, forms, customer service, small talk at the pharmacy.
I also genuinely understand why so many people stay despite the costs. Real estate professionals on the ground say demand hasn’t collapsed at all, and one South Florida realtor put it plainly, noting the insurance rates are crazy, but it isn’t a major impediment at this point, since retirement communities keep popping up everywhere and sell very quickly. Florida’s pull is real. It’s just that the math no longer worked for my particular retirement.
What I’d Tell Anyone Considering the Same Move
If you’re weighing this decision, don’t romanticize it and don’t panic into it either. Visa and residency rules shift constantly, and destinations that were once wide open can tighten quickly. Mexico is a good example, since income requirements there rose sharply, and by 2025, new income requirements of $4,200 per month for temporary residency and $7,000 for permanent residency made it unattainable for many retirees relying solely on Social Security. Do the current research before you commit to a country, not the research that was accurate three years ago.
Talk to real people already living there if you can find them, run your own numbers against your own income rather than a stranger’s blog post, and visit during an off season, not just the postcard months. Moving abroad in retirement isn’t a fantasy escape. It’s a financial decision dressed up in a nicer view, and it deserves the same careful math you’d apply to any major life change.
Looking Back Without Regret
Two years out, I don’t wake up second-guessing the decision. My monthly costs are lower, my healthcare is better than I expected, and I sleep easier not wondering what next year’s insurance renewal letter will say. Florida gave me twenty good years, and I don’t resent it for what it became. Costs change, states change, and sometimes the smartest retirement move isn’t staying loyal to a zip code, but staying loyal to your own bottom line.
If there’s one thing I’d want another retiree standing where I once stood to hear, it’s this: leaving isn’t giving up. Sometimes it’s the clearest-eyed decision you’ll ever make.