Ask any retiree scrolling through expat forums and you’ll get the same two names over and over: Portugal and Spain. Both offer sunshine, seaside towns, historic cities, and a slower pace of life that appeals to anyone leaving behind a career and a colder climate. Still, the question of which country actually stretches a retirement budget further isn’t as simple as picking the cheaper flight. Housing, healthcare, taxes, and visa rules all play a role, and the gap between the two nations has narrowed in some areas while widening in others.
This comparison digs into the real numbers for 2026, from monthly living costs to the fine print on retirement visas and pension taxation, so you can see where your money would actually go further.
The Headline Cost of Living Numbers
On paper, Portugal keeps its reputation as the cheaper of the two. While both countries remain relatively affordable compared to much of Western Europe, Portugal generally maintains a modest cost advantage over Spain. The difference is most visible in housing, utilities, and routine services, although it narrows significantly in smaller Spanish cities and inland regions. That last part matters more than people assume, since a retiree comparing Lisbon to Madrid will see a very different picture than one comparing Faro to Alicante.
Independent cost indices back this up. Portugal has a cost of living index of 40.2 and Spain has 45.2, with the cheaper country in absolute terms being Portugal, though the gap only matters relative to what you earn. Interestingly, purchasing power tells a slightly different story. Spain typically offers more residual income after covering living costs, though this varies by profession and city. For retirees living on fixed pensions rather than local salaries, though, the raw cost of goods and rent usually matters more than purchasing power ratios built around wages.
Housing and Rent: Where the Real Savings Happen
Rent is almost always the single biggest line item in a retirement budget, and this is where Portugal’s advantage becomes concrete. Portugal’s average rent runs about €10 per square metre compared to €12 per square metre in Spain. That may not sound dramatic, but multiplied across a full apartment, it adds up to a meaningful difference over a year. Of course, your actual housing bill depends heavily on city and neighbourhood, so a retiree chasing bargains in the Alentejo will pay far less than one insisting on central Lisbon.
Spain does have its own low-cost pockets. In cities like Seville, retirees who want authentic Andalusian culture and a lower cost of living can find rents starting around €800 per month, with a slower pace of life than in larger cities. Coastal favorites like Alicante and Marbella carry different price tags depending on proximity to the beach and the size of the expat community, but inland Spanish towns can rival Portugal’s smaller cities for affordability. The takeaway is that national averages only tell part of the story; regional choice inside each country often matters more than the country itself.
Monthly Budgets: What Retirees Actually Spend
Real-world budget estimates for Portugal cluster in a fairly tight range. In Portugal, a single person can typically live comfortably on €1,200 to €1,500 per month, depending on location and lifestyle. For couples, the picture shifts a bit higher. A single retiree can live comfortably on €1,300 to €1,700 per month in Portugal, and couples often spend €2,000 to €2,500 depending on the region. Outside the two major cities, Portugal offers the lowest cost of living in Western Europe, where a couple can live nicely on $2,500 to $3,000 a month.
Spain’s equivalent figures run a bit higher across most sources, particularly once you factor in the bigger cities. Madrid and Barcelona pull average costs upward the same way Lisbon and Porto do in Portugal, but Spain’s second-tier cities and inland regions can close much of that gap. The honest conclusion from most recent budget breakdowns is that Portugal wins by a modest but consistent margin overall, while Spain’s cheaper regions can occasionally undercut Portugal’s pricier ones.
Retirement Visa Requirements: D7 vs Non-Lucrative Visa
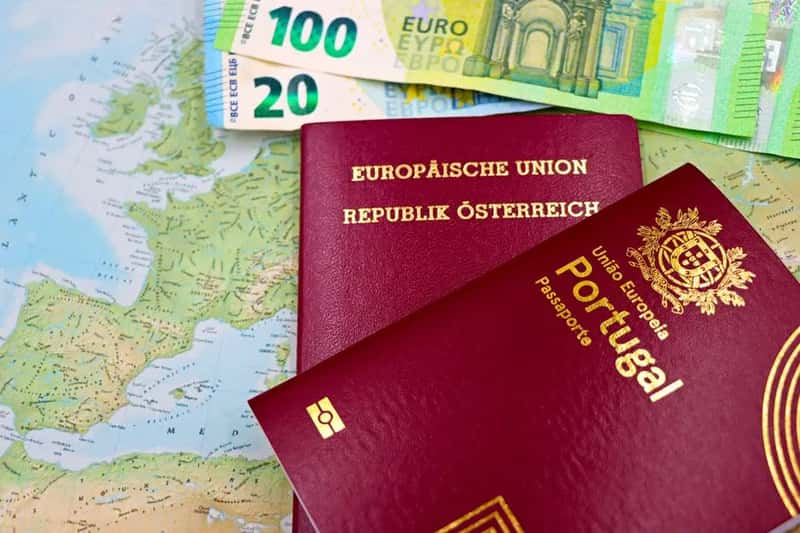
For non-EU retirees, the visa income threshold is often the first real filter, and here the two countries diverge sharply. Portugal’s route is the D7 visa. As of January 1, 2026, the Portugal D7 Visa minimum passive income requirement is €920 per month, totalling around €11,040 per year. This amount increases 50 percent for a spouse and 30 percent for each dependent child. That threshold is tied directly to the minimum wage rather than a fixed sum, which is why it has crept up gradually over recent years.
Spain’s equivalent path looks very different in scale. Spain’s retirement route is the Non-Lucrative Visa, with a 2026 income minimum of €28,800 per year, or €2,400 per month, for the main applicant, plus an additional €7,200 per year per dependent. That’s roughly three times Portugal’s requirement. It’s worth noting too that the Golden Visa ended on 3 April 2025, meaning property purchases no longer grant residency in Spain and retirees now rely on the Non-Lucrative Visa. For anyone qualifying on a modest pension, Portugal’s D7 is simply far easier to clear.
Taxes on Pensions and Retirement Income

This is where the picture gets more complicated than most retirement guides admit. Portugal’s famous Non-Habitual Resident regime, which once let foreign pensioners pay little or no tax on overseas pension income, no longer exists for new arrivals. On January 1st, 2025, the NHR officially ended and was replaced by the IFICI tax regime, which instead of relying on passive capital such as pensions or real estate investment, focuses on talent and innovation. The new scheme is aimed squarely at skilled professionals, not retirees.
Most current guidance suggests pension income now falls under ordinary rules. For 2026, that means progressive IRS rates from 12.5% to 48% on worldwide income as a tax resident, with a solidarity surcharge of 2.5% on income between €80,000 and €250,000, and 5% above €250,000. There is some conflicting guidance online about whether a narrower retiree sub-regime with a reduced flat rate still exists within IFICI, so anyone relying on favorable pension tax treatment should verify their specific situation with a Portuguese tax adviser rather than assume the old NHR benefits still apply. Spain, for its part, also taxes worldwide income for tax residents and layers on additional complexity: Spain imposes a wealth tax on worldwide assets, though regional governments in Madrid and Andalusia currently provide a roughly 100 percent rebate on this wealth tax. Neither country offers the tax-free retirement haven that Portugal was once known for.
Healthcare Costs: Public Systems and Private Backup
Both countries run public healthcare systems that legal residents can access, and both have earned solid reputations for quality of care at a fraction of American prices. Spain’s system in particular draws praise for its private sector as a complement to public coverage. Private healthcare is popular in Spain, providing faster access to specialized care and comfortable hospital environments, with private health insurance typically costing between €50 and €100 per month. That’s a manageable add-on for most retirement budgets, and it lets people skip long public waitlists for elective procedures.
Portugal’s private insurance costs sit in a comparable range, and its public system, the SNS, is generally considered reliable for both citizens and long-term residents. For visa applicants specifically, private coverage is not optional. Comprehensive health insurance coverage is required for the applicant and any family members included under the visa in Portugal, and Spain’s Non-Lucrative Visa carries an even stricter version of this rule, demanding policies with no co-payments or deductibles. In practice, healthcare costs end up fairly close between the two countries, with the real difference showing up in wait times and English-language service availability rather than price.
Daily Expenses: Groceries, Dining, and Getting Around
Day-to-day spending is where Portugal’s reputation for affordability really shows up in granular detail. One breakdown for a single retiree outside Lisbon put rent at $760 to $1,300 for a one-bedroom, groceries at $270 to $380, utilities and internet at $110 to $165, a transit pass around $43, and private health insurance between $55 and $165. Those numbers illustrate just how far a modest fixed income can stretch once you’re outside the capital.
Spain’s equivalent daily costs run similarly, though slightly higher in the major hubs. What tends to separate the two countries in daily life isn’t so much the price tag as the lifestyle wrapped around it. Major cities like Madrid and Barcelona bring a more energetic lifestyle with late-night dining, festivals, and a faster urban tempo, and daily life in Spain tends to be more lively and urban compared to Portugal’s calm, community-oriented environment. Retirees who want buzz and nightlife may find that vibrancy worth paying slightly more for, while those craving quiet routine will feel right at home in Portugal’s smaller towns.
Climate, Language, and Lifestyle Trade-Offs
Cost isn’t the only factor shaping where retirees land, and it’s worth being honest about the lifestyle differences that come bundled with the price tag. Portugal’s climate is generally considered more pleasing throughout the year, while Spain is slightly more accessible in terms of flight connections and destinations. Spain also tends to run warmer in its southern coastal regions. Mediterranean regions such as the Costa del Sol and Costa Blanca offer long, hot summers and mild winters, ideal for retirees who prefer consistent heat.
Language is another practical wrinkle that budget comparisons often skip. Portugal scores 35 out of 100 on English proficiency while Spain scores 44, making Spain somewhat more accessible for English speakers. That gap can influence everything from navigating bureaucracy to making friends, and it’s worth weighing alongside the euros-and-cents comparison. Neither factor changes the cost math dramatically, but they shape how comfortable that cheaper or pricier life actually feels day to day.
Best Value Regions in Each Country
Zooming into specific towns rather than national averages usually reveals the biggest savings opportunities. In Portugal, smaller cities consistently undercut the capital. Porto is often described as more traditional, with a lower cost of living than Lisbon, and inland regions and the quieter stretches of the Algarve go even further for retirees willing to trade big-city amenities for savings.
Spain offers a similar pattern of regional bargains. Beyond Seville’s affordable rents, coastal alternatives provide their own value proposition. Alicante on the Costa Blanca appeals to retirees seeking beaches and a strong international community, while Marbella on the Costa del Sol offers mild winters, a large expat population, good restaurants, and strong healthcare facilities, generally at costs below the biggest Spanish cities. In both countries, stepping away from the capital and the most Instagram-famous coastal strips is the single most effective way to lower your monthly spend.
So Which Country Actually Costs Less?
Adding it all up, Portugal edges out Spain as the cheaper overall choice for most retirees, primarily thanks to lower average rents, a lower cost of living index, and a dramatically more accessible visa income threshold. The D7 visa’s requirement of roughly €920 a month stands in stark contrast to Spain’s Non-Lucrative Visa threshold of €2,400 a month, and that gap alone determines eligibility for a large share of retirees living on modest pensions or Social Security.
Still, “less expensive” doesn’t automatically mean “better fit.” Spain’s warmer southern coast, livelier cities, better English accessibility, and competitive private healthcare pricing make a compelling case for retirees who value lifestyle and convenience over squeezing every last euro from their monthly budget. The most honest answer is that Portugal generally costs less on paper, but the right choice ultimately depends on whether you’re optimizing for savings or for the specific version of retirement you actually want to live.