For most of the last decade, the American migration story was simple: people were leaving expensive, cold, high-tax states for sunny, affordable ones. That script is now falling apart. Between rising insurance premiums, disappearing coverage, extreme heat, and a historic slowdown in the immigration that had quietly propped up many big metros, a new and more complicated pattern of decline is emerging.
Census data released in early 2026 shows the national population grew by just 1.78 million people between July 2024 and July 2025, roughly half the 3.2 million added the year before. That slowdown was driven almost entirely by a 54% decline in net international migration, from 2.7 million to 1.3 million. That single shift is now exposing which cities were only growing because immigrants were arriving, not because Americans wanted to live there. Layer in a worsening home insurance crisis, and you get a shortlist of cities that look increasingly fragile heading into 2027.
New Orleans, Louisiana: Sinking Under Insurance Costs
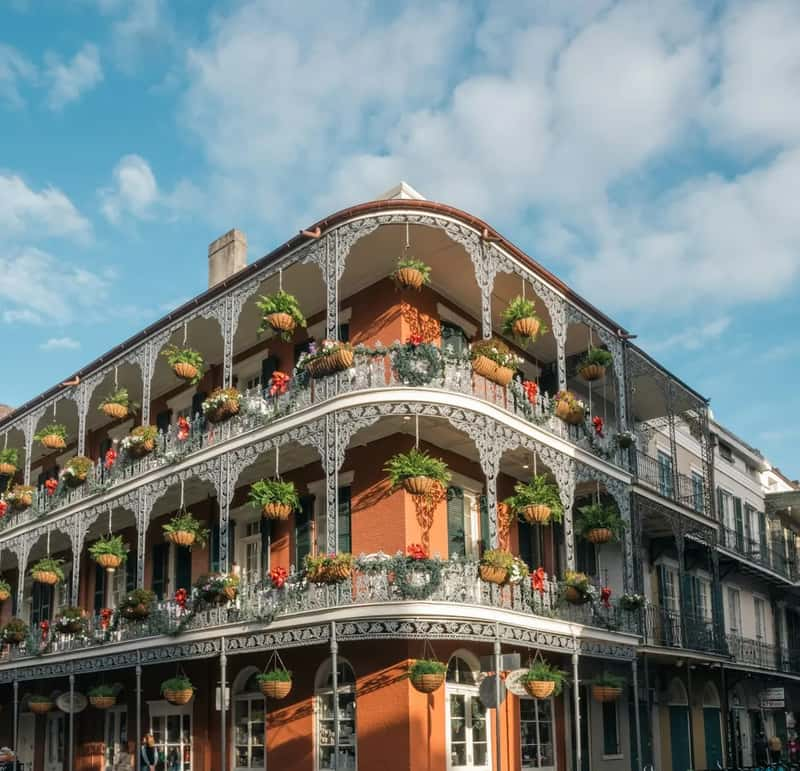
New Orleans has always lived with water, but the economics of staying have shifted dramatically. In high-risk Louisiana parishes, researchers have found that 30 to 40 percent of mortgage loans fail because of high home insurance costs. That is not a distant risk; it is happening in real time, as buyers walk away from closings once they see what coverage actually costs.
Louisiana sits alongside Florida, Oklahoma, and Texas as one of the country’s perennial highest-cost states for homeowners insurance, largely because of its exposure to wind and hail, water damage and freezing, and fire and lightning. As premiums climb faster than wages and home values struggle to keep pace, longtime residents are being squeezed out of a housing market that increasingly treats coastal Louisiana as a liability rather than an asset.
Miami and South Florida: The Price of Paradise
Miami has spent years as the poster child of Sun Belt growth, but the insurance math is starting to catch up with the postcard views. Researchers at First Street have found that home insurance rates in the city could quadruple as climate-driven losses continue to mount. Florida homeowners already pay some of the steepest premiums in the country, and multiple national carriers have pulled back from writing new policies statewide.
The instability runs deeper than any single storm season. In Florida, home-insurance rates are deregulated and are four times the national average, and climbing. Despite that, both Florida and California have seen major insurers withdraw from the market, including Farmers Insurance leaving Florida in 2023 and leaving 100,000 customers without insurance. For a metro that depends heavily on continued in-migration to sustain its housing market, a genuine insurance breakdown could turn Miami from a magnet into a cautionary tale.
Sacramento and California’s Wildfire Corridor
California has already tipped into outright population decline, and its wildfire-exposed interior cities are a big part of why. The state lost roughly 9,000 residents on net between mid-2024 and mid-2025, a shift largely explained by persistent domestic outmigration of about 230,000 residents per year, combined with net immigration to California dropping roughly 70 percent year over year, from 361,000 to approximately 109,000. Sacramento, sitting at the edge of increasingly fire-prone foothills, has felt that pressure acutely as insurers reassess risk across the region.
The insurance retreat has been dramatic. According to the California Public Policy Institute, California has been hit especially hard, with seven out of 12 major carriers leaving or reducing coverage since 2022. Meanwhile, First Street’s modeling suggests premiums in nearby Sacramento could double over the coming decades. For a metro that markets itself as an affordable alternative to the Bay Area, losing that affordability edge to insurance costs undercuts its entire appeal.
San Francisco: The Cost-of-Living Exodus Continues
San Francisco’s population losses during the pandemic era are well documented, and the underlying pressures, sky-high housing costs, a shrinking office workforce, and remote work flexibility, have not fully reversed. California’s broader domestic outmigration trend, running at roughly a quarter million residents a year on a net basis, has hit expensive coastal metros like San Francisco especially hard, since it is precisely the households with means and remote-work options who have the easiest path to leave.
What kept San Francisco’s headline population numbers from collapsing further was immigration, not domestic growth. Harvard’s Joint Center for Housing Studies has noted that at least five large metros, including Washington, Philadelphia, Miami, Boston, and Seattle, would have lost population without international immigration. San Francisco fits that same pattern. With international arrivals down sharply nationwide, the cushion that masked years of domestic flight is thinning out fast.
Phoenix, Arizona: Running Dry in the Desert
Phoenix built its growth story on cheap land and endless sunshine, but water scarcity and extreme heat are becoming harder to ignore. The Colorado River basin, which supplies much of the Southwest, has faced years of strained allocations, and rising summer temperatures are pushing up cooling costs at the same time insurance premiums climb for heat-related infrastructure damage. It is a slow-moving squeeze rather than a single dramatic event, but it is a squeeze nonetheless.
Arizona has not shown up yet among the outright population-losing states, but the broader Sun Belt slowdown described in 2026 migration data is worth watching closely here. Analysts note that Texas and Florida, the two largest migration magnets of the past decade, are now classified as balanced by United Van Lines, a first for both states in recent memory. If that cooling trend extends to Arizona as water and heat costs rise, Phoenix’s decades-long growth engine could stall out much faster than most residents expect.
Houston, Texas: Flood Risk Meets Rising Premiums
Houston has flooded repeatedly and severely over the past decade, and insurers have taken notice. Texas is one of the four states, alongside Florida, Louisiana, and Oklahoma, that the Insurance Information Institute considers perennially the four highest-price states for homeowner’s insurance, a designation driven by wind, hail, and water damage risk that hits the Houston metro particularly hard.
Even as Texas as a whole keeps adding residents, the composition of that growth is shifting. The state has moved into the “balanced” migration category for the first time in years, meaning inbound and outbound moves are now roughly equal rather than overwhelmingly favoring newcomers. For flood-prone neighborhoods around Houston specifically, rising premiums and repeated buyouts of flood-damaged homes suggest the metro’s long boom is running into real geographic limits.
New York City: Growth on Paper, Exodus in Practice
New York offers the clearest example of a city whose headline numbers hide a much shakier reality. The metro posted the largest gain in the nation at 213,403 people, almost entirely attributable to international migration. Strip that away, and the picture looks very different.
Domestically, New York is still bleeding residents at a startling pace. The metro lost nearly 277,000 people during 2020-2021 and continues to lose domestic residents at a rate of approximately 119,000 per year. With international arrivals now cut roughly in half nationwide, the math that has propped up New York’s population for years is becoming significantly more challenging. If that immigration cushion keeps shrinking, New York’s decade-long pattern of quiet domestic flight could finally show up in the topline numbers too.
Chicago and the Illinois Question
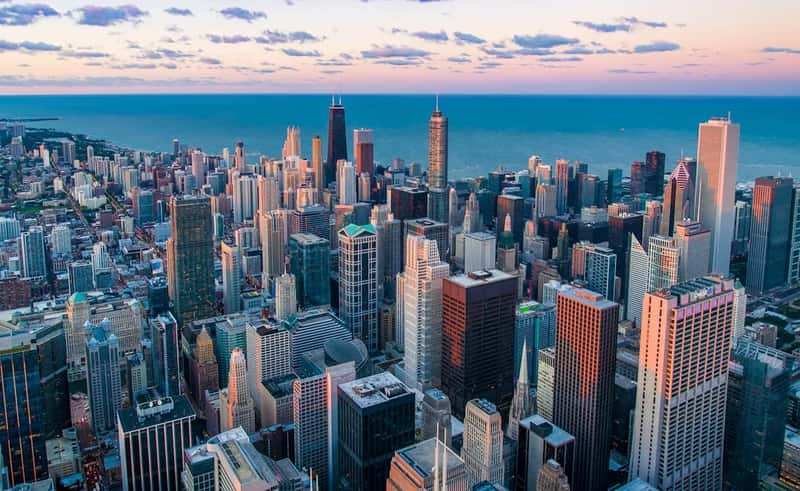
Chicago has long carried a reputation as one of the country’s steadiest population losers, driven by high property taxes, pension obligations, and colder winters that make Sun Belt alternatives tempting. Illinois itself was ranked the No. 2 outbound state by United Van Lines in 2024, a title that reflected years of accumulated frustration among residents weighing their options.
There are some tentative signs of stabilization. Illinois moved to balanced status in 2025, the first time in over a decade, though whether this stabilization holds depends in large part on immigration. Chicago fits the same profile as other Great Lakes and coastal metros that depend on international arrivals to offset domestic losses. With that inflow now cut sharply, Chicago’s recent calm could prove temporary rather than a genuine turnaround.
Where Everyone Is Moving Instead
The flip side of this story is just as important as the exodus itself. U-Haul’s growth data shows Americans are gravitating toward smaller, more affordable metros rather than the old coastal giants, a pattern the company’s rankings have captured clearly: Ocala, Florida, was the No. 1 growth city for the third time in four years, and twelve of U-Haul’s top 25 growth cities are in Florida, including eight of the top 10. Meanwhile, researchers have started flagging a very different kind of winner altogether.
Cities around the Great Lakes are increasingly discussed as long-term climate havens, thanks to their freshwater access and relatively moderate exposure to extreme heat and sea-level rise. Reporting on this trend notes that researchers have identified portions of the U.S. Great Lakes region as potential climate havens because of abundant freshwater resources, and cities including Buffalo, Cleveland, Duluth and Madison have begun discussing how they might accommodate future climate migrants. Whether that shift accelerates by 2027 or unfolds over a longer horizon, the underlying signal is the same: affordability, insurability, and climate resilience are now doing as much to shape American migration as sunshine and job growth ever did. Cities that ignore that shift are the ones most likely to keep watching their populations quietly slip away.