Most retirees spend months planning their dream trips – the Tuscany villa, the Alaskan cruise, the river journey through Portugal – and then spend about 10 minutes picking a travel insurance policy. That mismatch is exactly how a $7,000 trip turns into a $90,000 disaster. Seventy percent of Americans aged 50 and older planned to travel last year, and the average retiree expected to spend nearly $7,000 doing it. The financial stakes of getting insurance wrong have never been higher for this age group.
Here’s the hard part: most of these mistakes are invisible until a claim gets denied, a medical bill arrives from overseas, or a foreign hospital demands cash upfront at midnight. The 15 mistakes below are the ones that keep coming up – the ones retirees only talk about after the trip goes sideways.
#15 – Assuming Medicare Has Your Back Abroad

One of the most dangerous assumptions retirees carry onto a plane is believing Medicare will cover them the moment something goes wrong overseas. Except in very limited circumstances, Medicare does not cover medical costs incurred outside the United States – and it does not cover medical evacuation at all. That’s not buried fine print. That’s the rule, stated plainly in Medicare’s own documentation.
Even retirees with Medigap supplemental coverage face a hard ceiling: Medigap policies carry a lifetime maximum of $50,000 for eligible healthcare costs abroad. One serious hospitalization in Tokyo or Rome can eat through that entire lifetime cap in a matter of days. Retirees who travel frequently and carry no additional travel medical insurance are essentially uninsured the moment their flight leaves U.S. airspace.
At a Glance: What Medicare Actually Covers Abroad
- Original Medicare: Almost no international coverage – rare exceptions only (e.g., border emergencies near Canada or Mexico)
- Medigap: Covers some emergency care abroad, but only in the first 60 days of a trip and capped at a $50,000 lifetime limit
- Medicare Advantage: Coverage varies by plan – most require you to check with your provider before traveling internationally
- Medicare Part D: Does not cover prescriptions purchased outside the U.S.
- Medical evacuation: Not covered by any Medicare plan
#14 – Skipping Evacuation Coverage Because It Sounds Optional
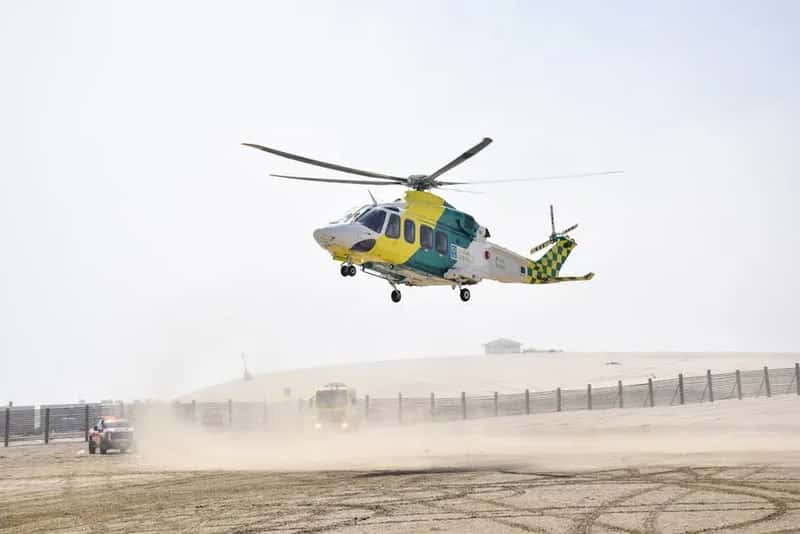
Medical evacuation coverage feels like an upsell – the kind of thing you’ll never actually use. Turns out, it’s often the single most financially catastrophic thing that can go wrong on a trip. A medevac helicopter from a remote destination – say, a trekking region in Nepal – can run anywhere from $150,000 to $200,000, and that figure covers only the transport, not the treatment. Even a shorter Caribbean cruise evacuation can easily cost around $20,000.
Retirees booking adventure-adjacent itineraries – safaris, river expeditions, remote hiking tours – are the most exposed. Standard “basic” travel insurance plans frequently exclude evacuation entirely, and that detail almost never shows up on the checkout summary page. You have to dig into the full policy document to find it, which most people never do. Experts recommend a minimum of $100,000 in evacuation coverage for international travel, with higher limits for remote or adventure destinations.
#13 – Buying the Policy Offered by the Cruise Line or Tour Operator
It’s easy and it’s right there at checkout. That’s exactly why so many retirees click “add travel protection” through their cruise line or tour operator without comparing anything else. The problem? Those bundled policies are frequently designed to protect the vendor, not you. Many cruise and tour operator plans do not cover medical expenses abroad or medical evacuation – the two things most likely to financially ruin a retiree if something goes wrong.
The cruise line’s policy typically covers trip cancellation back to their own credits, not cash reimbursements to you. A cheaper plan with inadequate coverage can prove far more expensive in the long run when something significant happens. Always compare third-party policies before accepting whatever the travel company drops into your cart at checkout.
#12 – Not Realizing “Cancel for Any Reason” Is a Time-Limited Upgrade

Plenty of retirees hear about Cancel for Any Reason (CFAR) coverage and assume they can add it whenever they get around to it. That’s not how it works. To qualify for CFAR – and for other time-sensitive benefits like the preexisting condition waiver – you typically need to purchase the policy within 10 to 21 days of your very first trip payment. Miss that window by even a single day, and CFAR is gone. No exceptions, no appeals.
Demand for Cancel for Any Reason add-ons has risen 22% year-over-year, which tells you something: more retirees are learning this lesson the hard way and trying to get ahead of it next time. CFAR typically reimburses around 75% of nonrefundable costs – not 100% – but that partial reimbursement can still mean thousands of dollars back in your pocket if health, family, or circumstances shift between booking and departure.
#11 – Waiting Too Long to Buy the Policy at All
This mistake compounds every other one on this list. Retirees often book a trip and then sit on buying insurance for weeks while they finalize hotels and excursion packages. The best time to buy travel insurance is immediately after you make your first payment – whether that’s a flight deposit, cruise down payment, or hotel booking. That first payment starts the eligibility clock for the most valuable benefits. Waiting doesn’t save money. It permanently limits what your policy can cover.
Here’s the version that really stings: if a named storm or major disruption makes the news before you buy your policy, it’s already too late to get coverage for that specific threat. Buying after a known event is public is functionally the same as buying no insurance at all for that event. The clock starts the moment you make your first trip payment – not when you feel like getting around to it.
Worth Knowing: The Time-Sensitive Benefits You Lose by Waiting
- Preexisting condition waiver: Typically requires purchase within 14 to 21 days of first trip deposit
- Cancel for Any Reason (CFAR): Usually must be added within 10 to 21 days of initial payment
- Named storm coverage: Unavailable once a storm is publicly named or announced
- “Cancel for Work Reasons” add-ons: Often time-gated in the same early-purchase window
- Full trip-cost coverage: Insuring 100% of nonrefundable costs is often required to unlock the preexisting condition waiver
#10 – Misunderstanding What “Trip Cancellation” Actually Covers

Most retirees believe that if they cancel their trip, the insurance pays. That’s not even close to how it works. “Changed my mind,” “work got complicated,” or “I got nervous about the destination” are not covered reasons under a standard policy. The covered reasons list is specific and narrow, and if your reason isn’t on it, the claim gets denied – no matter how reasonable your situation sounds to you.
In 2024, travel insurance claims rose 21% from the prior year, with canceled or cut-short trips representing a top category of losses. Trip protection reimburses prepaid, nonrefundable expenses only when cancellation happens for a reason explicitly listed in the policy. Knowing exactly what “covered reasons” means in your specific plan isn’t optional reading – it’s the entire game.
#9 – Forgetting to Insure the Full Trip Cost
This mistake seems minor and costs big. Retirees often insure only part of their trip – just the flights, say – and assume that’s enough. It isn’t. You need to insure all nonrefundable travel expenses: transportation, accommodations, rental cars, tours, and excursions. Anything you’d lose money on if the trip collapsed needs to be included in the insured amount.
It matters doubly because insuring the full trip cost is often a hard requirement for qualifying for the preexisting condition waiver. Miss that requirement – even while meeting all the others – and the waiver disappears entirely. That can mean a six-figure medical bill with zero coverage from a policy you paid good money for.
#8 – Not Disclosing Pre-Existing Conditions at Purchase
This is the number one reason travel insurance claims get denied for retirees, and it’s completely avoidable. Failure to disclose pre-existing conditions can result in denied claims – and the logic insurers use is brutal: if you didn’t disclose a condition, they can argue any related claim was foreseeable, and therefore excluded. Conditions like controlled high blood pressure, managed diabetes, or recent medication changes all fall into this zone.
Many travelers assume mild conditions don’t need to be mentioned. Insurers disagree. Disclosing everything feels uncomfortable, but it’s the only way the coverage you’re paying for actually functions. The insurer will either cover the condition, offer a waiver, or tell you upfront it’s excluded – all of which are better outcomes than a surprise denial in a foreign hospital.
#7 – Missing the Preexisting Condition Waiver Window
Even retirees who know about preexisting condition waivers often miss the tight purchase window required to get one. To ensure coverage for potential flare-ups of known conditions, you typically need to purchase your policy within 14 days of your initial trip deposit and insure 100% of your nonrefundable costs. Some plans extend that window to 21 days – but it varies by insurer, and once it closes, it closes permanently.
The downstream consequence of missing this window is severe. Insurers review your medical history during a “lookback period” – typically 60 to 180 days before your policy purchase date. If you changed a medication, had a new symptom, or saw a specialist during that window, your condition may be flagged as unstable. Any related claim can be denied in full, even if the condition seemed minor at the time.
Quick Compare: Stable vs. Unstable Conditions at Purchase
- Likely covered with waiver: High blood pressure controlled with the same medication for 12+ months, no dosage changes
- Likely flagged as unstable: Same condition, but medication dosage changed 6 weeks before purchase
- Likely covered with waiver: Type 2 diabetes, stable A1C, no new prescriptions during lookback period
- Likely flagged as unstable: New specialist visit or symptom evaluation logged within the lookback window
- Key rule: “Stable” means no new diagnosis, no new medication, and no recommended change in treatment during the lookback period
#6 – Choosing a Policy Based on Price Alone
Shopping for travel insurance the way you’d hunt for the cheapest flight is a trap specifically designed to catch retirees off guard. Older travelers carry more medical complexity, higher trip costs, and higher stakes than any other demographic – and a $79 “basic” policy almost never covers any of it adequately. The difference in premium between a bare-bones plan and a comprehensive senior-focused one is often a few hundred dollars. The difference in what actually gets covered can be tens of thousands.
As a general benchmark, look for policies offering at least $50,000 in emergency medical coverage and $100,000 in medical evacuation coverage – and retirees with known health conditions or adventure itineraries should look for significantly more. Specialized plans built for seniors include emergency medical care, evacuation, and preexisting condition protection as standard features, not expensive add-ons. The policy that looks cheapest at checkout is frequently the most expensive one when something actually goes wrong.
#5 – Not Keeping Documentation During the Trip

Retirees who’ve navigated home insurance or car insurance claims already know documentation is everything. Travel insurance is exactly the same – but people forget this when they’re in vacation mode. Missing paperwork is one of the most common technical reasons for a valid claim being denied. Save every receipt, report incidents immediately, and submit claims within the policy deadline, which is usually 30 to 90 days after the incident.
There’s one documentation requirement that catches people especially off guard: if illness prevents you from traveling, you need to see a doctor before canceling and have them complete a physician statement confirming you are unable to travel. Don’t simply cancel and file a claim. That physician statement sounds like a formality – skip it, and the entire claim can be thrown out regardless of how legitimate the illness was.
#4 – Ignoring Policy Exclusions for “Standard” Activities
Here’s one that catches active retirees completely by surprise: travel insurance policies exclude far more activities than most people assume. Common exclusions include hazardous sports, acts of war, and travel to countries under government travel warnings. But the definition of “hazardous” varies wildly between insurers – and some perfectly ordinary retirement-trip activities fall squarely into that category.
Skiing, scuba diving, and riding a rented motorbike may all be denied under standard coverage unless you’ve added a specific rider. A rented scooter in Greece or a snorkeling excursion in Cancún can be enough to void a claim if the policy wasn’t set up to cover it. If you plan to do anything more active than sightseeing, check the exclusions list before you buy – not after you’re already at the trailhead.
Fast Facts: Activities That Can Void a Standard Travel Insurance Claim
- Skiing and snowboarding (unless adventure sports rider is added)
- Scuba diving below a policy’s stated depth limit
- Riding a rented motorbike or scooter without a valid motorcycle license
- Bungee jumping, zip-lining, or paragliding in some standard plans
- Travel to a country or region under a U.S. State Department Level 3 or 4 travel advisory
#3 – Thinking a Single Annual Policy Covers Everything

Multi-trip annual policies sound like a smart, cost-efficient move for retirees who travel frequently. And they can be – but retirees often assume they cover everything a single-trip policy would. That assumption is frequently wrong. Annual plans typically cap coverage at 30, 60, or 90 days per trip. A retiree on a 45-day European river tour is completely exposed for the final two weeks if their annual policy has a 30-day per-trip limit.
Annual policies also tend to carry lower medical limits than comprehensive single-trip plans, and preexisting condition coverage may be absent or severely restricted. Before defaulting to the convenience of an annual policy, check the per-trip day limits, total medical maximums, and whether preexisting condition coverage is genuinely included. “Flexible” doesn’t mean “complete.”
#2 – Canceling a Trip Without Calling the Insurer First
This mistake is shockingly common and almost always fatal to a claim. A retiree gets sick, decides not to travel, calls the airline, cancels the hotel – and then files an insurance claim. The problem is the order of operations. For a trip cancellation or interruption claim to succeed, most policies require the insurer to be notified before or at the same time you cancel with service providers. Calling after the fact – even the same day – can be grounds for denial under the policy’s notification clause.
Most insurance companies also enforce a strict filing deadline. If you don’t provide required documents within the stated time frame, usually 30 to 90 days, your claim can be denied regardless of merit. The simple rule: call your insurer before you cancel anything. That one phone call is often the difference between a full reimbursement and a complete denial.
#1 – Assuming the Policy You Bought Actually Covers What You Think It Does
This is the mistake that underlies every other one on this list. Retirees buy a travel insurance policy, drop it in an email folder, and never read it. Then something goes wrong and they discover – too late, in the worst possible circumstances – that their understanding of what was covered bore almost no resemblance to the actual policy language. One of the most consistent findings in travel insurance claim data is that travelers who thoroughly read their policies and follow documentation requirements are dramatically more likely to receive a payout.
Some travelers assume their insurance will pay simply because their trip didn’t go smoothly. But for a claim to be covered, the specific cause of disruption must appear on the policy’s covered reasons list – full stop. The policy document isn’t exciting reading. But it’s the only document that matters when something goes wrong at 11 p.m. in a foreign hospital, and no one can interpret it for you in that moment except you.
The time to read the fine print is before you need it, not after.
Common counsel from travel insurance claims professionals
The through-line in all 15 of these mistakes is the same: travel insurance only works when you treat it as seriously as the trip itself. Buy it early, read it cover to cover, insure the full cost, disclose every condition, and call your insurer before you cancel anything. The gap between having insurance and having the right insurance can easily cost more than the trip itself – and unlike a missed excursion, it’s a loss you carry home with you.