Retiring abroad has never been more popular, but the rulebook keeps shifting under people’s feet. Governments that once welcomed foreign pensioners with open arms are now recalculating the trade-offs, weighing tourism revenue and property investment against housing pressure, healthcare costs, and public opinion about long-term foreign residents.
The result is a patchwork of quiet policy tweaks and, in some cases, sweeping legal overhauls that retirees planning a move need to watch closely. Below are seven countries where the direction of travel points toward stricter retiree visa conditions, based on changes already enacted or actively underway in 2025 and 2026.
1. Portugal
Portugal’s D7 visa has long been a favorite for retirees because of its modest income bar, but the surrounding legal framework has grown noticeably less forgiving. As of January 1, 2026, the Portugal D7 Visa minimum passive income requirement is €920 per month, totalling around €11,040 per year. That threshold rises automatically whenever the minimum wage does, since Portugal visa requirements have changed following the increase of the national minimum wage to €920 per month, directly affecting the income thresholds for the D7 and D8 residence visas, so when the minimum wage increases, the income and savings thresholds automatically increase.
The bigger shift is on citizenship and family reunification. Portuguese citizenship now requires 10 years of legal residence, or 7 years for EU citizens and nationals of Portuguese-speaking countries, under Lei Orgânica n.º 1/2026 in force from 19 May 2026. Family reunification has also hardened: as of October 2025, Portugal’s “Lei n.º 61/2025” entered into force, significantly reshaping the framework for family reunification, with the new regime placing stronger emphasis on self-sufficiency, integration, and procedural compliance. Notably, no general exemptions apply to D7 visa holders, unlike specific carve-outs granted to Golden Visa investors and D3 highly qualified professionals, which means ordinary retirees are absorbing the brunt of the tightening.
2. Spain
Spain’s retiree pathway looks stable on the surface, since the income threshold for the Non-Lucrative Visa hasn’t risen this year. Still, the enforcement environment around it has changed considerably. With the investment route gone, the Golden Visa suspended in April 2025 means the Non-Lucrative Visa is now a primary pathway to residency, and as a result, consulates are applying stricter checks on income sources, documentation, and financial traceability.
Two specific rule changes stand out for anyone planning ahead. First, remote work scrutiny has increased: remote work income is not accepted, full stop, and the 2025–2026 round of consular guidance has made this stricter, not looser. Second, physical presence now matters more than it used to, since the 183-day rule was put back into force under Royal Decree 1155/2024, which came into force on 20 May 2025. Health insurance standards have also crept upward, with some consulates now rejecting policies that fall short of newly enforced coverage minimums, a detail that has quietly tripped up applicants who assumed their old travel policy would still pass muster.
3. Thailand
Thailand has not rewritten its retirement visa from scratch, but the accumulation of smaller enforcement changes has made the Non-Immigrant O-A route considerably less casual than it once was. The 2024–2025 reforms brought new health insurance thresholds, tightened proof-of-funds rules, and the rise of alternative long-stay visas, making the picture in 2026 clearer but stricter than ever. Coverage requirements for the O-A category now sit well above where they started, and paperwork that once floated through on trust is being checked with far more rigor.
Verification of funds has become a particular pain point. Since many embassies, including the US, UK, and France, have ceased issuing income letters, authorities in 2026 require Thai bank statements showing Foreign Exchange Transfers over 12 consecutive months. That single change has pushed many applicants toward the bank-deposit route instead of the income route, adding friction for retirees who previously relied on a simple embassy letter. Digital oversight compounds the effect, since the verification process has become largely electronic via the Thai E-Visa portal, making forged documents or questionable intermediaries immediately identifiable by consular services.
4. Malaysia
Malaysia My Second Home, the country’s long-running retiree and long-stay program, has developed a reputation for changing its terms with little warning. Guides now routinely flag this as a risk factor rather than a footnote, noting that Malaysia’s program offers a long runway for retirees with financial stability, respected healthcare, and widely spoken English, though requirements have shifted periodically and careful review is needed.
The broader regional context makes the trend harder to ignore. Malaysia sits among the Southeast Asian nations where retirement visa rules moved this year, though none of the countries banned retirement outright, it’s the cheap, improvised version of long-term stays that is closing. For prospective MM2H applicants, that means the fixed-deposit and income tiers that looked settled a year or two ago should be treated as a moving target rather than a fixed number to plan around for the next decade.
5. Indonesia
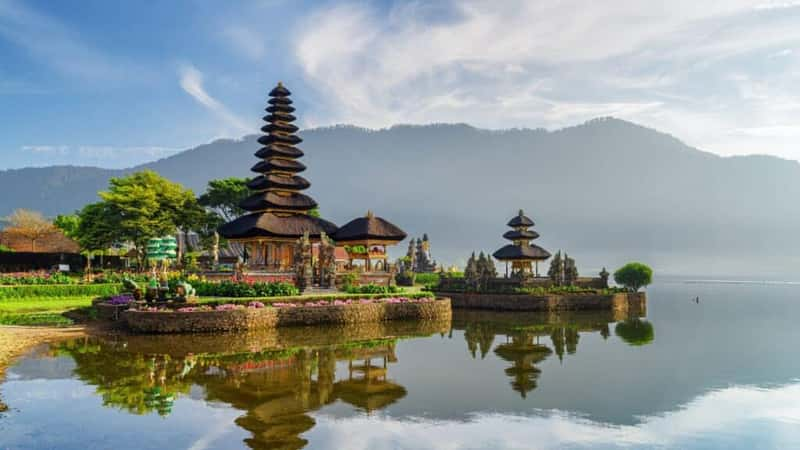
Indonesia has effectively restructured its long-stay options around capital rather than income, a shift that squeezes out the modest-pension retiree who once found the classic retirement visa affordable. Indonesia now routes most long-stayers through its Second Home Visa, a five-year permit backed by property or a deposit of roughly IDR 2 billion, about USD 130,000 at mid-2026 rates, or its Golden Visa from USD 350,000, with both options capital-gated rather than income-gated, suiting investors more than modest-pension retirees.
Beyond the money, there are unusual staffing obligations attached to residency in some categories. Some programs require a commitment to employ local citizens, and in Indonesia that means at least two employees, such as domestic help, nursing staff, a driver, or a gardener. Combined with the capital-gating, this pushes Indonesia’s retiree pathway further from the budget-friendly reputation Bali built its expat reputation on, and toward a wealthier, more heavily documented applicant pool.
6. Vietnam
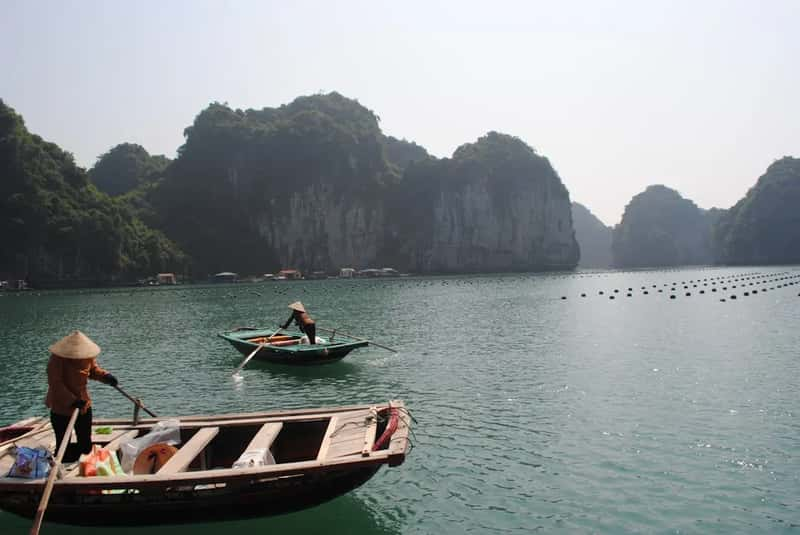
Vietnam never built a dedicated retirement visa in the first place, and the country’s 2026 legal reform makes that gap even more consequential for long-stay retirees. There’s no retiree-specific visa, so long-stayers rely on e-visas of up to 90 days, exemptions of up to 45 days for some nationalities, business or talent visas, or investment-linked residency. That patchwork approach is now getting stricter rather than more accommodating.
The timing is specific and worth noting for anyone mid-application. The new immigration law from 1 July 2026 tightens the framework further, and crucially, there’s no blanket guarantee that in-flight applications are grandfathered, since several 2026 changes took effect on short notice, though in practice an application already lodged under existing rules is often assessed under those rules while fees, deposits, and document standards can move mid-process. For a country already described as weaker than its neighbors on retiree stability, that unpredictability adds a real layer of risk.
7. Cambodia
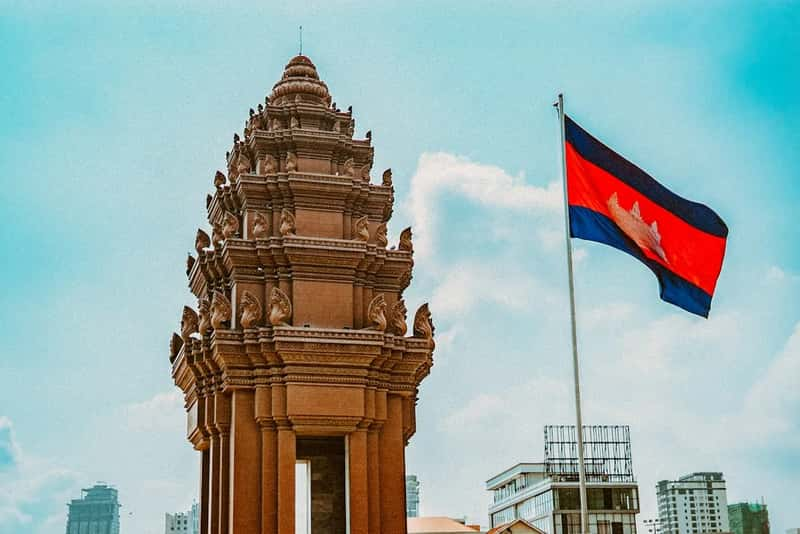
Cambodia still markets itself as the budget option in the region, and on paper that remains true. Cambodia’s ER visa remains cheapest at USD 300 annually for age 55 and up, but enforcement is tightening with per-applicant financial-proof checks and closer scrutiny on extensions. The low headline price is increasingly paired with more paperwork behind the scenes.
That pattern fits a wider regional logic. Three forces drive the tightening across the region: abuse, security, and revenue, with governments wanting fewer low-spend long-stayers who overstay or work illegally, tighter control after transnational-crime crackdowns, and more income from deposits, tax, and higher-value visa tiers. Cambodia’s low fee structure may survive the current wave of reform, but the days of a rubber-stamp renewal with minimal documentation appear to be ending, and retirees relying on the ER visa as a low-friction fallback should expect more scrutiny at each renewal cycle going forward.
Taken together, these seven cases point to a common thread rather than seven unrelated stories. Countries are not slamming the door on foreign retirees, but they are raising the paperwork burden, tying thresholds more tightly to local wage indexes, and pushing enforcement toward digital verification that leaves less room for the informal workarounds many long-stayers used to rely on.
For anyone weighing a move abroad in the near term, the practical takeaway is straightforward: verify current requirements directly with the relevant consulate or immigration authority before committing to a country, and build in a financial and documentary buffer well above the stated minimum. Rules that felt settled a year ago are, in several of these cases, already out of date.