
Family vacations rarely fail on the big decisions. They get expensive through smaller charges, such as a second checked bag, a hotel resort fee or a missed flight that forces a rebooking. Credit card benefits can offset some of those costs, though the right card depends heavily on how a household spends and travels. A recent guide from The Points Guy [1] outlined several cards aimed at families, and the overlap between their perks points to a few practical patterns worth understanding. ([1])
Why the travel details matter more than the rewards rate
A high earning rate on groceries or dining is easy to advertise, but families often gain more from benefits that apply to every traveler on a reservation. Southwest’s Priority card is a clear example. Cardholders receive a free first checked bag, Group 5 boarding and seat selection, and those benefits can extend to up to eight additional passengers on the same booking. For a family of four, the guide estimates that skipping a second bag fee saves $360 on a round-trip flight, which can cover the card’s $229 annual fee in a single trip.
Protection plans work differently. Trip cancellation and interruption coverage, baggage-delay coverage and primary rental car insurance can matter most when something goes wrong. The Chase Sapphire Preferred is positioned around that safety net, and its $95 annual fee is lower than many premium options. Families planning an expensive trip may place more value on a covered disruption than on a few extra points.
Everyday spending cards built for the household budget
Several cards in the guide focus on the bills that arrive every month. The Blue Cash Preferred from American Express offers 6 percent cash back at U.S. supermarkets on up to $6,000 in purchases each calendar year, then 1 percent. Its 3 percent category covers U.S. gas stations and transit, and it offers a $0 annual fee for the first year before moving to $95. The Citi Strata Premier takes a broader approach, with bonus categories spanning supermarkets, restaurants, gas stations and hotel purchases.
The Capital One Savor Cash Rewards card takes a different route. It carries no annual fee and earns 3 percent at grocery stores, dining, entertainment and popular streaming services. Superstores such as Walmart and Target are excluded from the grocery category, however, which makes the card less suitable for households that do most of their shopping there. The Venture Rewards card suits families whose expenses are spread across many categories, since it earns 2 miles per dollar on nearly everything, with no category tracking.
What matters now: Welcome bonuses and benefit terms change frequently, and several perks require enrollment or carry expiration dates. Families should confirm current offers and fees directly with each issuer before applying.
Premium cards and the math behind the fee
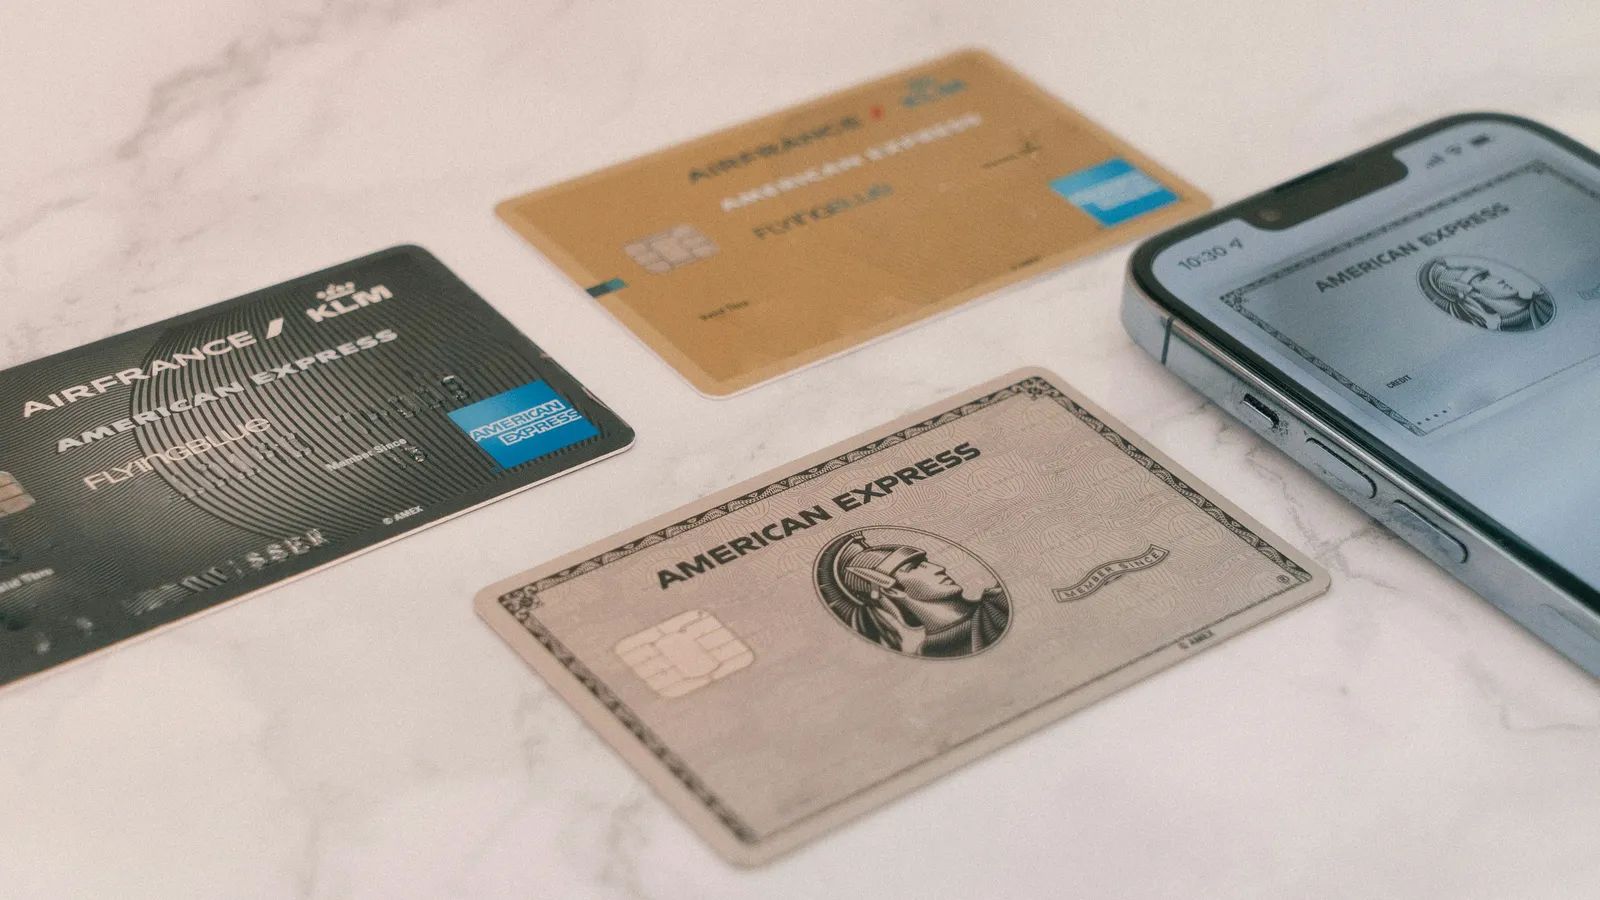
The Amex Platinum sits at the top of the range, with an $895 annual fee. The guide describes it as a fit for frequent-traveling families who can use its credits and lounge access. Those credits include up to $200 in airline incidental charges each calendar year, up to $219 toward CLEAR+ and a Global Lounge Collection membership. Children 17 and younger can accompany a CLEAR+ member through security without their own membership, which adds value for households with several children.
The guide is clear that the card is not necessary for most families. A household that does not regularly use the credits or the lounge network would struggle to justify the cost. The comparison becomes simpler when families list the credits they would realistically use and set them against the fee.
How to narrow the choice
Families often try to find one card that handles everything, but the guide’s selections suggest a more practical approach. A family that flies together several times a year may get more from an airline card with bag and boarding benefits. A household that spends heavily on groceries and streaming may prefer a cash back card with no travel obligations. Families that stay in hotels frequently can compare resort-focused awards with hotel credits and fee waivers.
The choice comes down to how a family actually spends. A card that rewards the right expenses, supports every traveler on the trip and carries a fee the household will use is more likely to deliver savings than one with the highest headline rate. For families planning their next vacation, the most valuable benefit may be the one they already know they will need.