Most people planning a retirement overseas spend months comparing countries, weighing beach towns against mountain villages, and building spreadsheets full of rent estimates. Far fewer stop to ask a simpler question: when should this actually happen? The calendar, it turns out, can be just as important as the destination, shaping everything from your monthly Social Security check to the exchange rate you’ll be living with for years to come.
Why the “when” question deserves as much attention as the “where”
Retirement guides tend to obsess over rankings, and there’s no shortage of them. Greece has climbed to the top of International Living’s Global Retirement Index for 2026, a first for the country, thanks to its combination of affordable Mediterranean living, EU membership benefits, and a uniquely attractive tax deal that has set it apart from long-standing favorites like Portugal and Spain. Panama sits close behind, largely because of its dollarized economy, first-world infrastructure, and the legendary Pensionado Visa, widely considered one of the world’s most generous retiree programs.
Those rankings matter, but they only tell half the story. A great country chosen at the wrong moment in your financial life, your visa cycle, or even the calendar year can turn a smart decision into a costly one. Timing touches your income, your paperwork, your healthcare coverage, and even how comfortable your first few months abroad will feel.
Social Security timing: the decision that follows you overseas
For many American retirees, when to claim Social Security is the single biggest financial lever they’ll pull before ever boarding a plane. Claiming at 62 instead of waiting until full retirement age of 67 permanently reduces your benefit by 30 percent, which on the average benefit works out to roughly 623 dollars less per month, for life. That’s not a small rounding error when you’re converting dollars into pesos, baht, or euros every single month.
Wait a little longer and the math flips in your favor. Waiting until 70 increases the benefit further, since delayed retirement credits add 8 percent per year past full retirement age, for a total 24 percent increase from 67 to 70, an additional roughly 498 dollars a month compared to claiming at 67. As of 2026, the average retired worker benefit is 2,076 dollars per month, and that gap between an early claim and a delayed one can be the difference between a tight budget in a foreign city and genuine breathing room.
Currency swings can make or break your budget
A retirement plan built entirely around today’s exchange rate is a plan built on sand. For retirees abroad living on a fixed dollar income, a swing in exchange rates collides with local price increases, which is why planning ahead matters more, not less, when you live overseas. A dollar that buys generously in one year can buy noticeably less two years later, even if nothing about your lifestyle has changed.
Financial advisors who specialize in expat retirement often flag this as an underappreciated risk. Ignoring currency trends and prioritizing the wrong benefit during a period of currency swings can cut your real spending power. That’s one reason some retirees keep a U.S. bank account active even after moving, so they can time transfers when the exchange rate favors them rather than being forced to convert money on a fixed schedule.
Visa processing windows are longer than most people expect
Even the friendliest retirement visa programs run on government timelines, not personal ones. Portugal’s D7 visa, often cited as one of the easiest retirement pathways for Americans, requires a passive income of just 920 euros per month, though the processing time is six to nine months in 2026, and the visa can lead to permanent residency and citizenship. Applying too close to a planned move date can leave you scrambling or paying for temporary housing you never budgeted for.
Panama’s well-known Pensionado program has its own income threshold to plan around, requiring a lifetime pension starting at 1,000 dollars a month for a single applicant. The lesson across nearly every destination is the same: start the paperwork long before you intend to pack a suitcase, not the month before.
The off-season scouting trip nobody talks about
Glossy retirement brochures rarely show a place during its rainy season, its off-season lull, or the week when half the shops close for a local holiday. Yet that’s exactly when many practical questions get answered honestly. Experienced relocation guides consistently recommend visiting during the less flattering months, not just the postcard season, before signing a lease or buying property.
This matters because a destination that feels magical in April might feel isolating in November, especially somewhere with a small expat community or limited English-speaking services. Financial advisors focused on Social Security and expat retirement note that retirees who make this work tend to visit for several months before signing on the bottom line. A short vacation is not the same test as living through an ordinary Tuesday in January.
Healthcare enrollment gaps and waiting periods
Healthcare timing is where a lot of retirees get caught off guard, partly because Medicare simply doesn’t travel with you. The standard Medicare Part B premium of about 203 dollars per month still applies if you keep it, yet Medicare isn’t available abroad since it doesn’t cover healthcare outside the U.S. That means budgeting for local private insurance or public system access from day one, not after you’ve already moved.
Even countries with excellent public healthcare can impose a waiting period before new residents are eligible. Even in countries with excellent public systems like France or Spain, new residents often face a waiting period before becoming eligible, leaving a critical gap that only private international insurance can fill. Arriving without a bridge policy in place, even for a few weeks, is a gap most people would rather not test in person.
Housing cycles in popular retirement hubs
Property markets in popular expat destinations don’t move in a straight line, and buying at the wrong point in that cycle can cost thousands. International Living’s annual retirement index specifically evaluates the ease of buying and owning property as a foreigner, then the value received as a homeowner, factoring in the price of housing in expat-friendly locations and property taxes, along with rental values. In many markets, the smarter early move isn’t buying at all.
Renting first gives new arrivals room to breathe while the local market, and their own preferences, become clearer. As the same research notes, in many destinations renting makes better financial sense than buying, which is why long-term leases and the cost of renting a furnished two-bedroom apartment in a mid-range area get close scrutiny. Committing to a purchase during your first month in a new country, before you’ve lived through a full seasonal cycle, is rarely the wisest sequence.
Tax year alignment and residency rules
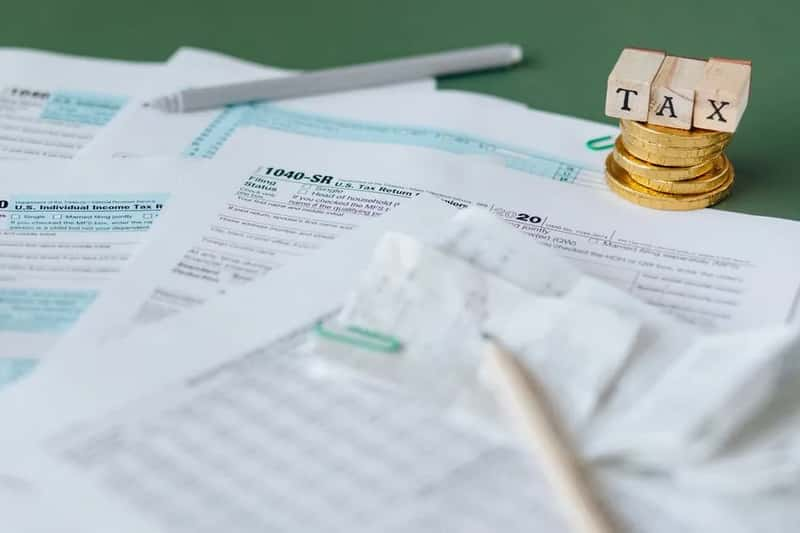
Few things complicate a retirement move like straddling two tax systems in the same year. Americans abroad remain on the hook regardless of address, since most U.S. citizens must still file federal taxes on worldwide income regardless of where they live, and income from Social Security, pensions and rental properties can make things even more complicated. Moving mid-year without understanding how a host country defines tax residency can trigger filing obligations in two places at once.
Expat tax specialists generally recommend mapping out the transition well in advance rather than reacting after the fact. A practical approach within the first 30 days is to request your Social Security statement and pension projections, review your country’s tax treaty with the U.S., and later model claiming scenarios at current exchange rates. Lining up a move date with a clean tax-year break, rather than an arbitrary lease start date, often saves a genuine headache the following spring.
Health, mobility, and the physical cost of waiting too long
There’s a quieter kind of timing that has nothing to do with visas or exchange rates: your own body’s schedule. Retirement guides that focus on the practical side of moving abroad often stress the importance of thinking honestly about issues that become more significant as you age, such as flight connections home, availability of specialist medical care, and the accessibility of everyday life. A hillside village that’s charming at 65 can feel a lot less practical at 80 if stairs and distance from a hospital become daily concerns.
Waiting for the “perfect” financial moment indefinitely carries its own risk, since health and mobility rarely improve with delay. Many retirees who move successfully in their late sixties or early seventies later admit they wish they’d made the jump a few years earlier, while travel and adjustment felt easier. Balancing the financial case for waiting against the physical case for moving sooner is, in many ways, the real heart of the timing question.
Policy shifts that can change the calculus overnight
Visa rules and benefit structures are not fixed forever, and recent years have shown how quickly the ground can shift. The Social Security Fairness Act, for instance, ended the Windfall Elimination Provision and the related Government Pension Offset, with December 2023 the last month those rules applied, meaning benefits payable from January 2024 forward are calculated without the WEP reduction. That single legislative change meaningfully increased monthly income for many retirees with foreign pensions.
Longer-term funding questions add another layer worth watching. The 2026 Social Security Trustees Report now projects the retirement trust fund will run short in late 2032, after which incoming revenue would cover about 78 percent of scheduled benefits, an automatic cut of roughly 22 percent unless Congress acts, a projection released on June 9, 2026 that moved the depletion date up by one quarter from the prior year. Nothing changes for current retirees today, but anyone weighing when to claim benefits over the next several years has good reason to treat that 2032 date as a real planning input rather than background noise.
Final thoughts
There’s no single calendar date that works for everyone chasing a retirement abroad. Some people benefit from moving the moment a visa clears and a lease is signed, while others gain more by waiting a few extra years for a larger Social Security check or a stronger exchange rate. The countries topping the 2026 rankings, from Greece’s tax advantages to Panama’s long-running Pensionado program, will likely still be there in a year or two.
What won’t wait is the compounding effect of an early Social Security claim, a currency shift, or a visa window closing without warning. Treating timing as seriously as location doesn’t guarantee a flawless move, but it does mean fewer surprises once the boxes are unpacked and the new address feels like home.