You paid into Medicare for decades, so it’s natural to assume that card works wherever you land. Then a hospital billing desk abroad hands you an invoice, and the card turns out to be worth far less than you thought. That moment is exactly where these 15 details tend to surface for travelers over 65: at a billing window, in a denial letter, or the day after a deadline quietly expired.
The strange part is that none of these traps are exotic. They hide in a 15-day window, a single word like “limited,” and a phone call you’re supposed to make before you do anything else. Here they are, counting down, and the one that costs families the most is waiting at #1.
#15 – Medicare Mostly Stops at the Border
Plenty of retirees treat their red, white, and blue card like a passport to care. Original Medicare generally does not pay for health care outside the United States, apart from a few narrow exceptions. Those include certain cases in Canada when you’re traveling directly between Alaska and another state, or care on a ship within six hours of a U.S. port.
What catches people off guard is how ordinary the trips are. A weekend in Cancún, a river cruise in Europe, or a week at a daughter’s place abroad can all leave you uncovered. A single emergency room visit overseas can be billed to you in full, with no Medicare reimbursement at all. And the backup plans people count on come with catches of their own.
#14 – The Medigap “Foreign Travel” Benefit Has a Lifetime Ceiling
Some supplement plans include a foreign-travel perk, and people hear that and relax. Several Medigap plan letters, including C, D, F, G, M, and N, carry a limited emergency benefit abroad. Under the standard rules, it pays 80 percent after a $250 deductible.
The catch is the cap. The standard benefit is limited to $50,000 for your entire life, not per trip. It also generally applies only to emergencies that begin during the first 60 days of a trip. One serious hospital stay abroad can burn through a limit like that in a hurry.
But the Medicare Advantage version of this promise is even vaguer, and it’s next at #13…
#13 – “Emergency Coverage Abroad” on a Medicare Advantage Plan Can Be Thin
Medicare Advantage brochures sometimes mention worldwide emergency coverage in one quiet line. Coverage abroad is an optional extra that only some plans include, and the word “limited” is doing a lot of work when they do. The details live in the fine print, not on the front page.
Plans differ on dollar caps, on what counts as an emergency, and on whether follow-up care is covered. Routine care, and often the flight home, typically isn’t part of the deal. Your plan’s Evidence of Coverage document is where the real rules live. It’s rarely the first thing anyone reads before booking.
Quick Compare
- Original Medicare: generally nothing outside the U.S., apart from a few narrow exceptions.
- Medigap (some letters): a limited emergency benefit, 80% after a $250 deductible, capped at $50,000 for life.
- Medicare Advantage: an optional extra on some plans, with caps and definitions that vary.
- Travel insurance: only as strong as the limits and exclusions you choose.
Now for a deadline that most travelers blow past without knowing it exists, at #12…
#12 – The Clock Starts With Your First Deposit, Not Your Flight
The most valuable perk for older travelers comes with a ticking timer. To qualify for a pre-existing condition waiver, you usually need to buy the policy within 14 to 21 days after your first trip deposit. Travel Guard, for example, sets that window at 15 days.
Here’s how people get burned. They book a cruise cabin with a small hold, then start shopping for insurance weeks later. By then, the window may have already closed, and the waiver is gone for good. Cancel-for-any-reason coverage often runs on the same schedule.
Even buying on time can fall short, because the waiver has a second requirement, and it’s next at #11…
#11 – The Waiver Often Requires Insuring the Entire Trip Cost
You can beat the deadline and still lose the benefit. To qualify, you’ll generally need to insure the full nonrefundable trip cost. Covering just the flight while the hotel and tours sit outside the policy can disqualify you.
Added costs matter too. A pricey excursion booked after you bought the policy may not be included unless you update the coverage. The gap between what you paid and what you insured can quietly undo the waiver. It’s worth adding up every prepaid cost before you click “buy.”
And the next requirement has nothing to do with money…
#10 – “Fit to Travel” on Purchase Day Can Override Everything
Here’s a detail almost nobody mentions on the checkout page. Travel insurance policies generally expect you to be fit to travel on the day you buy, and that includes plans advertising a pre-existing condition waiver. It’s a quiet condition sitting underneath the headline promise.
If your health is shaky that day, the insurer can use it against you later. Not being fit to travel can override the waiver and lead to a denied claim. A waiver is only as strong as your health on the day you bought the policy. Some travelers get a quick check-in with their doctor before purchasing, which feels like overkill until a claim gets questioned.
The next trap involves a pill you may not think of as “treatment”…
#9 – Your Look-Back Period Can Include a Simple Medication Change
Insurers don’t just ask whether you’re sick. They look backward. Look-back periods vary by insurer, but usually start 60 to 180 days before you purchased your plan, and anything that happened in that stretch can count.
The definition is broader than most people expect. A pre-existing condition is any medical issue that existed, changed, or required treatment during that period. A changed dose or a new prescription can reclassify a “stable” condition as unstable. On the flip side, a condition with no treatment, visits, or procedures during the look-back may not count as pre-existing.
Age adds another wrinkle, and it isn’t the one you’d expect at #8…
#8 – There’s Often No Upper Age Limit, but the Price Tells a Different Story
Many travelers assume coverage vanishes somewhere around 80. Often it doesn’t. Reviewers note that GoReady by Aegis has no age limit for coverage, and Allianz also has no upper age limits.
The sticker shock is the real problem. Premiums generally rise with age, because the insurer is pricing a higher chance of a claim. Some plans are built specifically for Medicare-enrolled travelers up to age 99. One such product is marketed to seniors aged 65 to 99. That age-banded pricing is why two travelers on the same cruise can pay wildly different amounts for the same protection.
At a Glance
- Some insurers, including GoReady by Aegis and Allianz, are noted for having no upper age limit.
- At least one plan is marketed to Medicare-enrolled travelers aged 65 to 99.
- Premiums generally climb as the traveler’s age goes up.
- Same ship, same cabin, very different price tags.
Now for the detail that decides who pays first, at #7…
#7 – Primary vs. Secondary Coverage Decides Who Pays First
Two policies with the same limits can behave very differently. A secondary plan only pays after your other insurance does, while a primary plan pays first. Travel Insured’s policies offer primary coverage, so you can submit for reimbursement without first proving you tried your regular health insurance.
That matters if you’re on Medicare abroad. With a secondary plan, you may have to collect a denial from an insurer that was never going to pay. That means extra paperwork while you’re recovering in a foreign hospital bed. The fine print on this one deserves a slow read.
But the next detail could make or break the whole policy at #6…
#6 – The Medical Limit You Pick Can Be Dangerously Low
Plenty of people sort by price and grab the cheapest option. It’s an easy move to make, and it can leave a huge hole if you land in a hospital abroad. Limits aren’t standardized, so a bargain plan may cover only a sliver of a serious bill.
At the top end, Tin Leg offers up to $500,000 in medical coverage, with a matching $500,000 for emergency evacuation. The low-limit plan and the high-limit plan can look nearly identical on a comparison page. The headline benefits match until you look at the dollar figures.
Next, the activities your policy may quietly refuse to cover, at #5…
#5 – The Fun Stuff Is Where Exclusions Hide
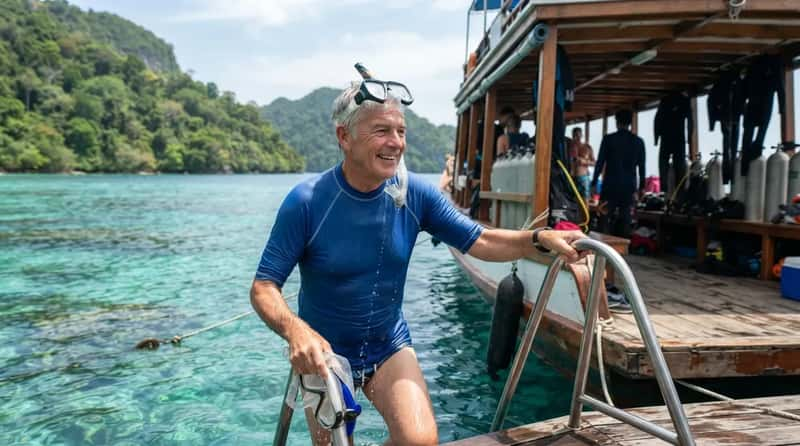
Insurers don’t only ask about your health. Many policies exclude or limit coverage for certain activities, and vacation excursions can land right in that zone. Think scuba diving, zip lines, and rented motorbikes.
Alcohol is another sore spot, since many policies can reduce or deny claims when intoxication contributed to an injury. A harmless-looking shore excursion can be the one activity your policy never agreed to cover. The exclusions list usually sits in the policy document, not on the marketing page. Reading it before the trip beats reading it in the ER.
Fast Facts
- Scuba diving, zip lines, and rented motorbikes are common trouble spots.
- Alcohol involvement can shrink or sink a claim.
- The exclusions live in the full policy document, not the sales page.
- Before you book an excursion, ask the insurer in writing whether it’s covered.
Next up is a feature that sounds like a magic wand but isn’t, at #4…
#4 – “Cancel for Any Reason” Rarely Means a Full Refund
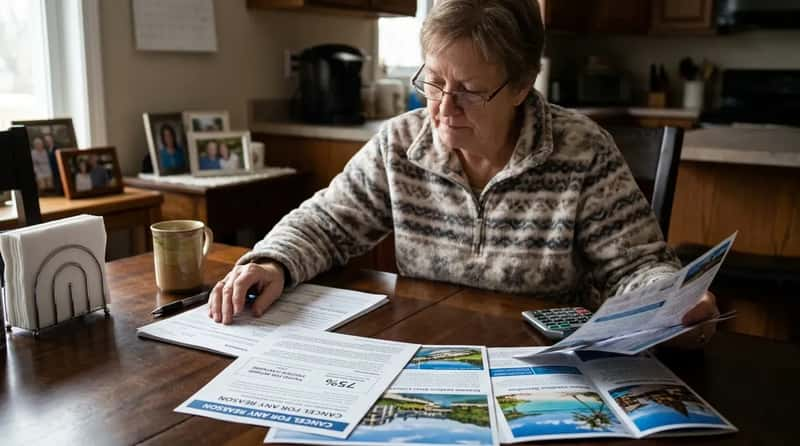
The name sounds like a guarantee. It isn’t. One popular add-on reimburses 75% when purchased within 21 days of initial payment, and another plan in the same review lists the same 75% for Cancel for Any Reason.
That’s a real benefit, but it’s often oversold. You can still lose a quarter of your nonrefundable trip cost, and you must cancel before the insurer’s cutoff ahead of departure. It can be worth it for people with real uncertainty about their plans. Just don’t mistake it for a full refund.
But the card in your wallet may be an even bigger gamble, as #3 shows…
#3 – Your Credit Card’s Travel Perk Probably Won’t Cover a Hospital Stay
A lot of travelers lean on the benefits that come with a premium credit card. Those perks tend to be narrower than people think. Trip delay and baggage coverage are common, while robust emergency medical coverage, especially for long hospital stays, often isn’t part of the package.
Where medical benefits do exist, they can be secondary and capped. Many retirees discover the gap only after the claim form asks for a policy number that was never theirs. The card’s guide to benefits spells all of this out. It rarely gets opened until something goes wrong.
And then there’s the place where medical help seems easiest to reach, at #2…
#2 – Cruise Ship Medical Care Can Come With Its Own Bill
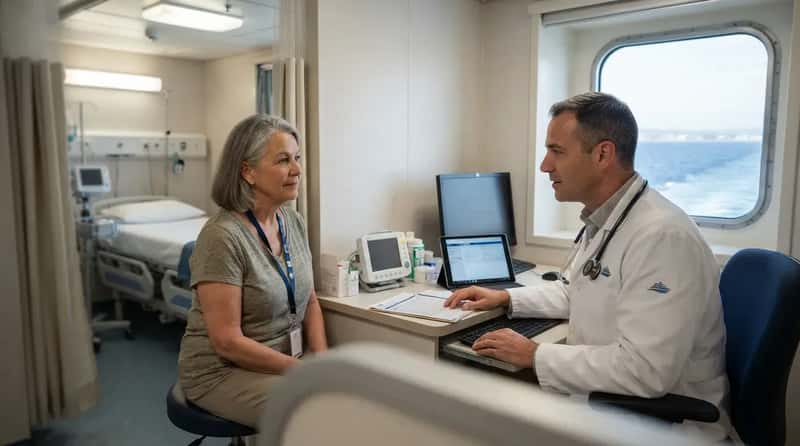
A cruise feels like the safest kind of trip. There’s a doctor on board, after all. But shipboard medical centers typically charge for visits and treatment, often billed straight to your onboard account, and your regular health plan likely won’t pay.
Serious cases are a different story. A ship’s clinic is built to stabilize passengers, not provide long-term care. A serious emergency at sea can mean being taken ashore in a port you’ve never visited. That’s when evacuation coverage stops being fine print and becomes the whole point.
But the biggest surprise, the one insiders warn about most, comes next at #1…
#1 – Medical Evacuation Is a Separate Coverage, and the Insurer Often Calls the Shots
This is the one that costs families the most. Medical evacuation moves you to a facility that can actually treat you, and it’s not the same as an ambulance ride. It can also mean getting you home. Private medical flights can run into the tens of thousands of dollars, and Medicare won’t cover them abroad.
Plans often require you to contact their assistance team before arranging anything. That team usually decides what’s medically necessary and where you go. Booking your own flight first can leave you paying out of pocket. That’s why evacuation limits, like the $500,000 emergency evacuation benefit on one top plan, are worth comparing carefully.
Worth Knowing
- Evacuation is its own benefit, with its own dollar limit, separate from emergency medical coverage.
- Medicare won’t pay for private medical flights abroad.
- Call the plan’s assistance line first, and book nothing until they weigh in.
- Save that number in your phone and keep a printed copy in your wallet.
Look back over the list and a pattern shows up. Medicare mostly stops at the border, the supplemental perks are capped, and the strongest protections come with short windows, often 14 to 21 days after your first trip deposit. The cheapest plan, the credit card perk, and the cancel-for-any-reason add-on all turn out to be weaker than they sound.
None of this is meant to scare anyone out of the trip of a lifetime. It’s the opposite: the people who enjoy those trips most are usually the ones who read the dull paperwork first. Which of these surprised you most, and did one ever cost you something?