Retirement planning has become a numbers game unlike any generation before has faced. It is a challenging reality to question whether someone can retire on $1 million, when there was a time that amount put you in rare air and you thought you had it made for all the right reasons. Today, geography is arguably the most powerful financial lever a retiree can pull. In some of America’s most popular retirement towns, a million dollars could last more than 20 years, even if you are living comfortably with more than just the basics. Choosing the right city, however, makes all the difference between a nest egg that lasts a lifetime and one that runs dry far too soon.
To identify where money goes the furthest, GOBankingRates identified U.S. locales with the highest percentages of residents aged 65 and up, then penciled out living expenses to determine how long a million-dollar nest egg would last, drawing on data from the U.S. Census, Sperling’s Best Places, Zillow, and the Bureau of Labor Statistics. At a 4% safe withdrawal rate, a retiree draws roughly $40,000 per year before Social Security payments are factored in. The five cities below represent standout options where that math actually works in your favor.
1. Chattanooga, Tennessee
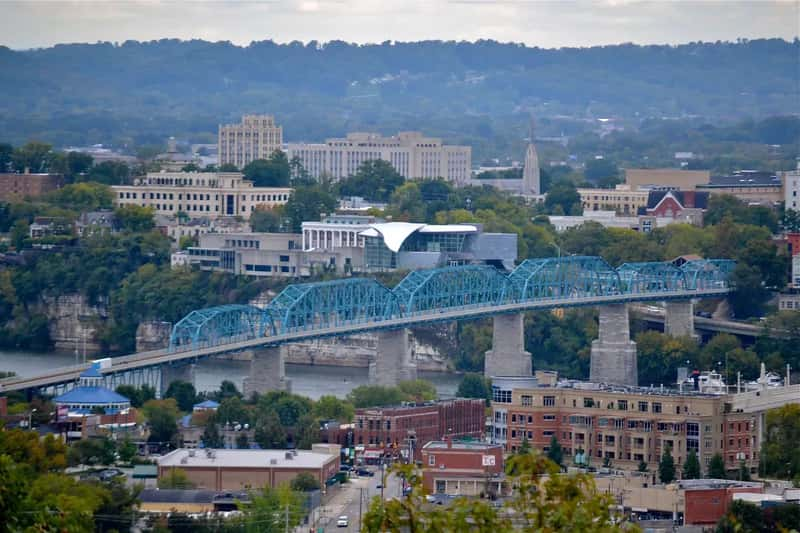
Chattanooga is part of a stretch of East Tennessee that includes the tech-forward, scenic hub of the city alongside the energetic college town of Knoxville and the quieter, value-driven Tri-Cities area. For those seeking a blend of affordability and lifestyle, Knoxville and Chattanooga are especially appealing. The Tennessee River cuts right through the heart of the city, offering a setting that is genuinely beautiful without the premium price tag that typically comes with waterfront living. Tennessee has one of the lowest costs of living in the United States, sitting at 10% below the national average, and everyday expenses such as utilities and groceries are budget-friendly, with housing options ranging from suburban homes to retirement communities priced below the national average.
One of Tennessee’s biggest selling points is its 0% state income tax. Compared with Georgia and North Carolina, where state taxes reduce take-home pay, Tennessee lets you keep more. Retirees benefit especially, since Social Security and pensions are not taxed at the state level. In the hottest neighborhoods of Chattanooga, median home prices range from around $350,000 to $450,000. The average cost of senior living in Chattanooga is approximately $3,417 per month, which is well within reach for a retiree drawing from a $1 million portfolio supplemented by Social Security. Social Security and pensions go further here, and lower utility costs help fixed incomes stretch farther.
2. Cape Coral, Florida
Florida is one of the few states with no state income tax, allowing retirees to retain more of their Social Security benefits, pension payments, and other retirement income. There are also no estate or inheritance taxes, and seniors can benefit from homestead exemptions that reduce property taxes and lower annual housing costs significantly. Cape Coral, located on the southwest Gulf Coast, sits in a particularly sweet spot of Florida’s otherwise pricey real estate landscape. In the Fort Myers and Cape Coral area, prices have come down over 10% from their peak, creating real deals for patient buyers, while nearby Punta Gorda offers a median price around $390,000 for strong value compared to the state average.
According to U.S. News and World Report’s 2026 rankings, several Florida cities scored high for retirement, including Palm Harbor, Naples, Pensacola, Cape Coral, and Bonita Springs, all earning strong marks for population and migration trends as well as quality of life. The cost of living in larger Florida cities like Miami and Fort Lauderdale runs over 20% higher than in cities like Jacksonville, Orlando, and Ocala, where costs are below the national average. Cape Coral leans toward the affordable end of that spectrum. Cape Coral is expanding rapidly with more affordable housing, making it one of the more budget-conscious entry points into Florida retirement living. Retirees from the Midwest and Northeast continue to move in, drawn by the sunshine, lifestyle, and tax advantages.
3. San Antonio, Texas
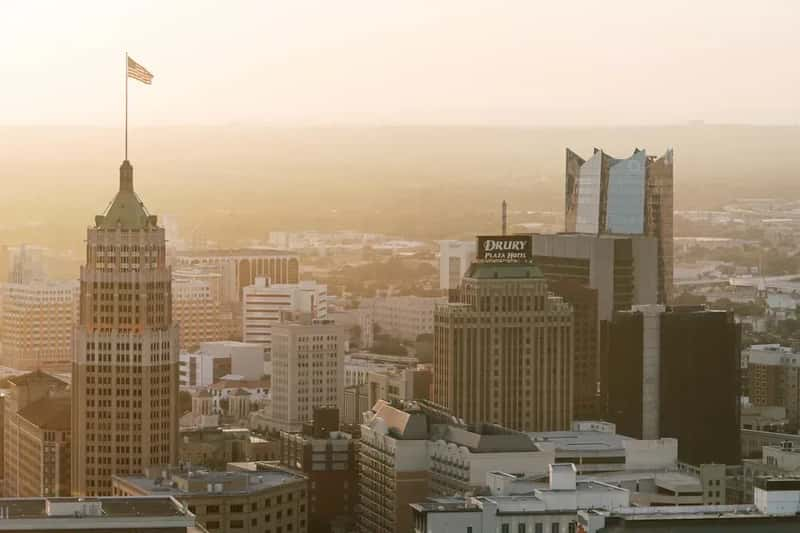
Texas offers retirees an income-tax-free state, mild winters, much lower living and housing costs than California, and the chance to live in cities known for vibrant culture and high-quality healthcare options. San Antonio in particular has long been recognized as one of the more affordable major American cities, blending history, culture, and a genuine sense of community. For those seeking affordability and rich history, San Antonio provides a unique cultural backdrop with a lower cost of living. Cities such as San Antonio, TX, are among the best places for renters to retire, with quality hospitals and doctors, plenty of green space, and retiree-friendly amenities.
Among the nine states with no state income taxes, Texas stands alongside Florida, Nevada, Wyoming, and others, giving retirees immediate savings on every dollar they draw from a pension, IRA, or investment account. Major healthcare systems, including UT Southwestern and MD Anderson Cancer Center, ensure seniors get the care they need. Property taxes can vary dramatically between neighboring towns, and suburbs of major cities like San Antonio can offer a strategic balance of access to amenities, quality healthcare, and more manageable property tax rates. That balance is precisely what makes a $1 million retirement feel genuinely spacious here rather than strained.
4. Tucson, Arizona
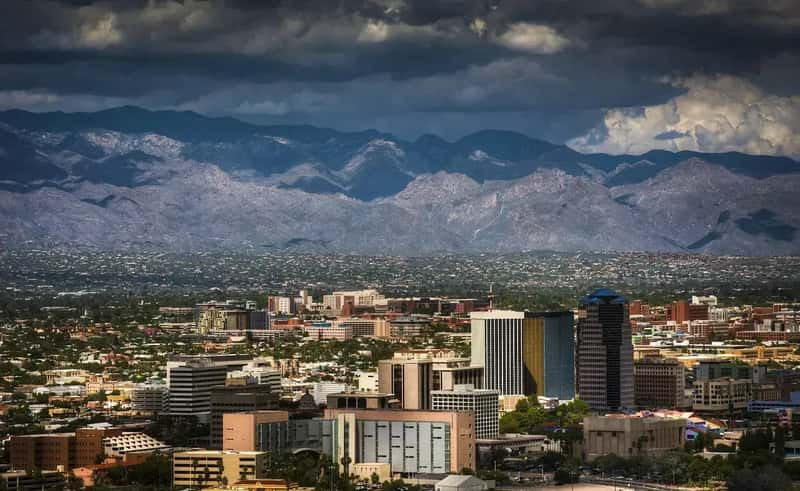
Arizona is a fantastic retirement destination known for its breathtaking landscapes and warm climate. It offers retirees a balance of affordability, tax advantages, and opportunities for an active lifestyle. Arizona has no tax on Social Security benefits, helping ensure fixed income goes further, plus reasonable property taxes and deductions available for certain retirement income. Tucson sits at a higher elevation than Phoenix, which means summers are noticeably more bearable, a practical advantage that many retirees underestimate. From Tucson to Phoenix, Arizona is packed with 55-plus communities and resort-style living options that cater specifically to the needs and preferences of older adults.
Wellton, a small town in southwestern Arizona located in Yuma County, has single-family homes worth about $260,000 on average, illustrating just how affordable the Arizona market can be outside of Scottsdale or Phoenix. Scottsdale, Arizona, ranks among the second-best places to retire in the country in large part because of its abundance of activities popular with retirees, including top rankings for adult volunteer activities, art galleries, and public golf courses per capita. Tax-friendliness is another strong reason to retire in the Tucson-Scottsdale region of Arizona. Someone living modestly in a low to medium cost-of-living lifestyle will likely be just fine with a $1 million retirement fund lasting at least 30 years. In Tucson, that scenario is entirely realistic.
5. Asheville, North Carolina
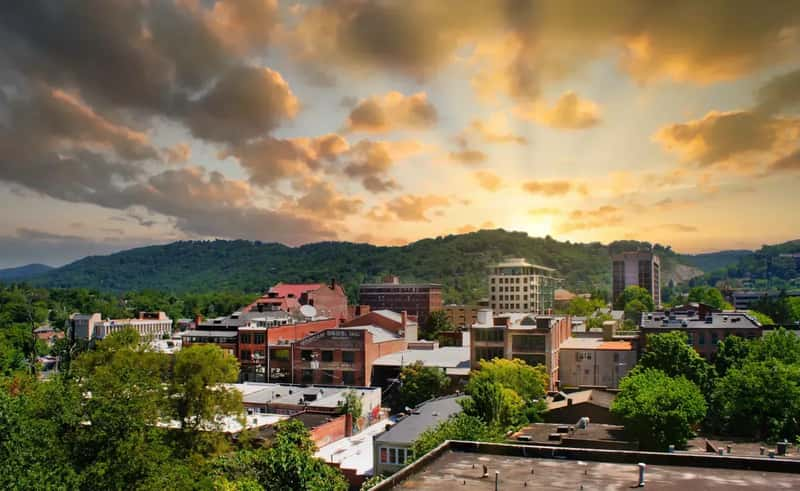
North Carolina’s geographic diversity is one of its greatest assets. Retirees can choose between the vibrant, arts-focused mountain communities of Asheville and Boone or the serene coastal living of the Outer Banks, ensuring access to year-round outdoor recreation from hiking the Blue Ridge Parkway to relaxing on pristine Atlantic beaches. Asheville’s cost of living is 70% lower than San Francisco, 29% less than Washington, D.C., 5% below Miami, and 57% below New York. That comparison alone makes the city’s value proposition crystal clear. The weather in Asheville is considered ideal, and based on data from NOAA’s National Climatic Data Center, Asheville ranks as having one of the most favorable climates in the country based on comfort and the number of days with clear skies.
North Carolina is a healthcare powerhouse, anchored by the world-renowned Duke University and UNC Health systems in the Research Triangle area, providing retirees access to cutting-edge care and specialized services. Asheville’s cost of living in 2026 runs approximately $2,756 per month for a single person. That figure, when stacked against a $40,000 annual safe withdrawal from a $1 million portfolio plus average Social Security, gives retirees genuine breathing room for travel, dining, and leisure. Kiplinger’s 2025 roundup of the most affordable retirement areas highlights places where housing prices run 30 to 60 percent below the national average, and Asheville fits squarely into that category when compared with coastal peers. The combination of mountain scenery, an arts-driven community, accessible healthcare, and manageable living costs make it one of the most compelling under-the-radar retirement destinations in the entire country.
The Bigger Picture: Location Is Your Most Powerful Retirement Tool
Where you retire could affect how far your savings go. The cost of living varies widely across the U.S., and these differences can have a major impact on retirement planning. A comfortable lifestyle in one state might require much more – or less – in another. If you want to live in a high-cost city like San Francisco, Miami, or New York, a $1 million fund will fall short. Even with a rent-controlled place, you could still need at least $100,000 per year to live, creating a $60,000 annual shortfall against a $40,000 safe withdrawal rate. The five cities profiled here – Chattanooga, Cape Coral, San Antonio, Tucson, and Asheville – share a common thread: they offer strong quality of life, favorable tax rates, growing senior populations, and accessible healthcare.
According to the Employee Benefit Research Institute’s 2025 Retirement Confidence Survey, 67% of workers reported feeling at least somewhat confident they would have enough money to retire comfortably, but only 24% said they were “very confident.” Choosing the right city can be the single decision that shifts a retiree from the anxious majority into that confident minority. Retirement lifestyle depends not only on how much you save, but where you choose to live and how carefully you plan. The best-case scenario for making $1 million last, no matter when you retire, is arriving already debt-free and settled in a city where your dollar genuinely works hard every single day.