Anyone who has priced out a move to the Southeast knows that a state’s cost of living rarely stays flat across twelve months. Utility bills swing wildly between January and August, insurance premiums reset at different points in the calendar, and property tax deadlines land on specific dates that can catch new residents off guard. For retirees weighing Florida against South Carolina, those seasonal shifts matter just as much as the big-picture tax debate that usually dominates the conversation.
This breakdown walks through the year as it actually unfolds for a retired household living in either state, month by month, so the comparison reflects real timing rather than just annual averages.
January and February: snowbird season and housing pressure
Winter is when Florida’s population swells with seasonal residents, and that surge shows up directly in rental prices and everyday demand for services. Housing remains the sharpest contrast between the two states going into the new year. Florida’s statewide median home price sits around $412,000 to $420,000 as of early 2026, while the Greenville metro’s median sale price is currently around $312,000 to $325,000. That gap alone can shape a retiree’s budget before a single utility bill or tax form enters the picture.
South Carolina’s winter months are milder in terms of cost pressure since the state doesn’t see the same seasonal population spike. Heating costs stay modest in both states this time of year because winters are short and generally gentle. Florida retirees who own rather than rent tend to feel less of the January housing crunch, but those still shopping for a home will notice competition from snowbirds driving up asking prices in popular coastal towns.
March: property tax filing deadlines come due
March is a pivotal month for Florida homeowners because it’s when homestead exemption paperwork is due. Each additional exemption must be filed separately with your county property appraiser, typically by the same March 1 deadline. Missing that window can mean losing a full year of savings, which matters a great deal for retirees on fixed incomes.
Florida’s senior exemption adds meaningful relief for those who qualify. If you are 65 or older as of January 1 of the filing year and your household adjusted gross income does not exceed $38,686, you can claim the additional senior exemption. Stacked with the standard homestead break, Florida homeowners 65+ can receive property tax exemptions reducing taxable home value by up to $150,000, saving $1,500 to $2,400 or more annually. South Carolina has no equivalent March deadline crunch, since its property tax system runs on a different, generally simpler schedule with lower baseline rates.
April and May: the calm before hurricane season
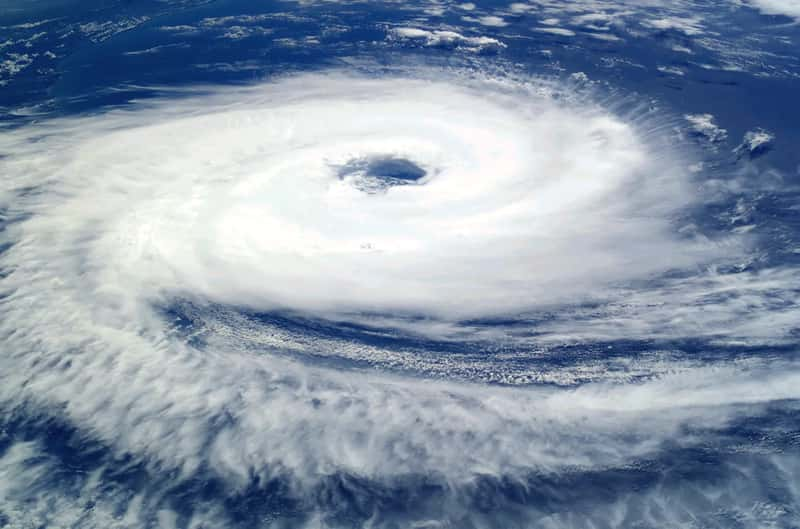
This is a retouched picture, which means that it has been digitally altered from its original version. Modifications: Increased contrast; decreased brightness; adjusted color balance in favor of blues and whites; removed large black splotches in several locations. Modifications made by Tomf688., Public domain)
Spring is typically the most predictable stretch of the year for both states, with utility bills sitting near their annual midpoint. This is also when many retirees start shopping for homeowners insurance renewals ahead of the June 1 start of hurricane season. Florida premiums during this window reflect a market that has been unusually volatile in recent years but is finally showing signs of stabilizing.
Florida homeowners insurance is stabilizing for the first time in over a decade, with Citizens Property Insurance announcing an average 8.7% rate cut statewide for 2026. Even with that relief, the average Florida homeowner still pays between $4,200 and $5,700 per year, more than double the national average of $2,580. South Carolina retirees shopping for coverage in the same window pay noticeably less, since the state’s inland geography and lower storm exposure keep premiums well below Florida’s coastal rates.
June: hurricane season begins and premiums lock in
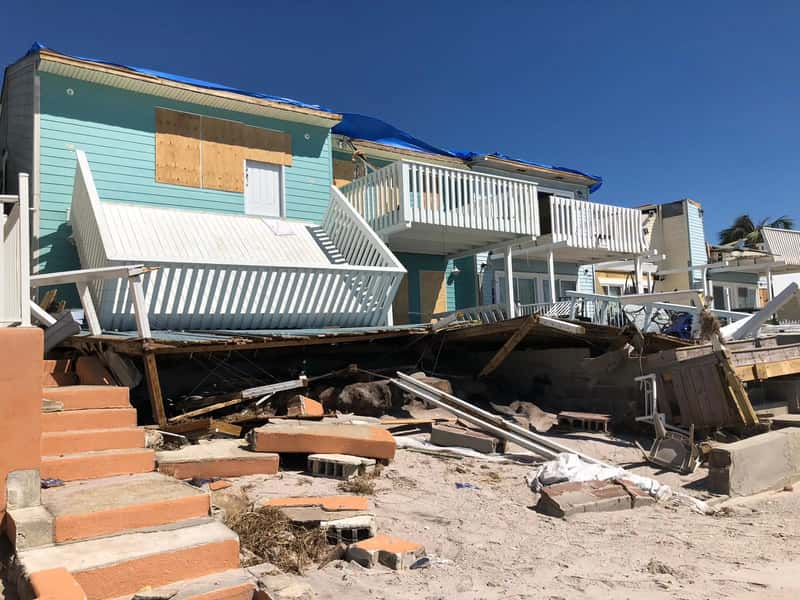
June 1 marks the official start of Atlantic hurricane season, and it’s the point where Florida insurance costs become locked in for the year regardless of how the season actually plays out. Hurricane season starting June 1 makes this the critical time to review a policy, shore up coverage gaps, and lock in potential savings. Retirees who wait past this point often find fewer options and less negotiating room with carriers.
South Carolina homeowners face a comparatively quiet June, since the state’s exposure to major hurricane landfalls is lower than Florida’s peninsula geography. South Carolina generally has lower property insurance costs than Florida’s coastal areas, along with a lower overall cost of living and distinct seasons. That seasonal calm doesn’t mean South Carolina is immune to storms, but the pricing reflects a genuinely different risk profile.
July and August: peak cooling costs hit hard
Midsummer is when air conditioning becomes the dominant line item on any Southeastern utility bill, and both states show it. Florida’s estimated monthly electric bill runs around $139, with gas near $67 and water around $46. South Carolina’s rates per kilowatt-hour are lower, but usage tends to run higher because of humidity.
South Carolina residents consume roughly 13,000 kWh per year, about 15% more than the national average, driven largely by air conditioning demand from May through September. That heavier usage partly offsets the state’s cheaper per-kWh rate, which sits at 17.06 cents per kilowatt-hour as of July 2026, approximately 13% below the national average of 18.83 cents. In practical terms, both states hand retirees their highest electric bills of the year during these two months, even if the underlying math differs.
September and October: hurricane season peaks
Late summer into early fall is when hurricane risk in Florida reaches its highest point, and it’s the stretch retirees feel most acutely if a storm actually makes landfall. Florida’s hurricane season runs between June and November and peaks in mid-August through October. This is also when hurricane deductibles, which are separate from standard homeowners deductibles, become relevant if a named storm causes damage.
Common hurricane deductible options in Florida include 2%, 5%, and 10% of the dwelling value, meaning a retiree with a $400,000 home and a 2% deductible could face $8,000 in out-of-pocket costs before insurance coverage kicks in on a hurricane claim. South Carolina retirees face a real but statistically smaller version of this same risk, since the state sits along the Atlantic coast without the same peninsula exposure that puts nearly all of Florida within reach of tropical systems.
November: snowbirds return and bills start dropping
November brings a welcome shift for budgets in both states as cooling costs fall and the snowbird population begins arriving in Florida again. It’s also typically when Florida county tax collectors mail out annual property tax bills, with early payment discounts available for homeowners who pay ahead of the March deadline. Retirees who plan around this schedule can shave a small percentage off their annual property tax bill simply by paying early.
South Carolina property owners see a comparatively gentler tax bill overall, since the state’s effective rates run lower across the board. South Carolina offers a lower overall cost of living, roughly 9% below the national average, and lower property taxes with an average rate near 0.45%. That rate advantage compounds every November when tax bills land, regardless of home value.
December: year-end tax planning and retirement withdrawals
December is decision time for retirees managing required minimum distributions, pension timing, and any last adjustments before a new tax year begins. This is where the two states diverge most sharply on income tax, since South Carolina taxes retirement withdrawals while Florida does not. South Carolina reformed to a two-bracket system in 2026, with 0% on the first $18,050 of taxable income and 5% above that, Social Security benefits fully exempt, and retirees aged 65 and older able to deduct $15,000 from their retirement income.
The dollar impact becomes concrete at higher withdrawal levels. At $75,000 in non-Social Security retirement income, a South Carolina retiree pays approximately $2,098 in state tax while a Florida retiree pays zero. For retirees drawing modestly from Social Security alone, this December gap shrinks considerably, since South Carolina fully exempts Social Security benefits from state income tax in the same way Florida does by having no income tax at all.
How sales tax and everyday spending compare year round
Outside of the big seasonal categories, day-to-day spending on groceries, dining, and retail purchases follows a fairly steady pattern across both states throughout the year. Florida’s base sales tax rate is 6%, with most counties adding 0.5% to 1.5% for a total of 6.5% to 7.5%, while South Carolina’s base sales tax rate is also 6%, with some counties adding 1% to 2% on top for a total of 7% to 8%. In practice, this is effectively a wash for most retirees regardless of which state they choose.
Where the two states diverge more is in housing-adjacent monthly costs rather than sales tax. Outside premium markets like Charleston and Hilton Head Island, retirees can usually purchase more home for their money in South Carolina than in many of Florida’s popular retirement destinations. That difference in purchasing power shows up every month in the form of a smaller mortgage payment or a lower homeowners association fee, long after the initial purchase decision is made.
Adding up the annual totals
When the twelve months are stacked together, the pattern that emerges is less about one state being universally cheaper and more about where the savings and costs land. Florida’s biggest financial advantage remains its complete absence of state income tax, which matters most to retirees drawing larger pension or investment income. Florida has the tax edge, since no state income tax is a real advantage for most retirees, along with a wider range of 55+ communities to choose from.
South Carolina’s advantage shows up more steadily across housing, insurance, and general cost of living rather than in a single dramatic tax break. South Carolina has the cost of living edge, lower property taxes, and more geographic variety for retirees who value those factors over the income tax exemption. As one broader estimate put it, a Florida retiree planning to live from 65 to 85 is estimated to need around $1.2 million in retirement dollars, while a South Carolina retiree aiming for the same timeline can settle for approximately $967,000, though actual figures vary widely based on lifestyle, housing choice, and healthcare needs.