Most travelers treat trip insurance like a magic shield: buy it, forget it, and assume it’ll catch whatever goes wrong. Claims adjusters see the fallout from that assumption constantly – policies that look bulletproof on the sales page and full of trapdoors in the actual contract nobody opened.
Buried in that fine print are rules almost nobody expects: deadlines measured in hours, a single drink that can erase your medical coverage, and payout caps that shrink the moment you actually need the money. Here’s what claims adjusters and policy experts say happens when travelers finally read the pages they skipped.
#22 – The “Look-Back Period” That Quietly Disqualifies Pre-Existing Conditions
Almost nobody realizes their insurer investigates their medical history before ever paying a claim. Companies use what’s called a “look-back period,” and depending on the plan it can stretch 60, 90, or even 180 days before you bought the policy. If your condition wasn’t stable during that stretch, it gets treated as pre-existing and foreseeable – and usually gets excluded entirely.
Here’s the silver lining most travelers miss: a condition that’s effectively managed, with consistent prescription medication at the same dosage, generally isn’t treated as pre-existing. Most plans will still cover it as long as treatment hasn’t changed. The catch is that almost no one checks their own look-back window before symptoms flare up on a trip.
#21 – “Cancel For Any Reason” Still Isn’t a Full Refund
The name sounds like a blank check. It isn’t. CFAR typically reimburses only 50% to 75% of your non-refundable trip costs if you cancel for a reason standard coverage won’t touch, and travelers who assume they’ll get every dollar back are frequently blindsided at claim time.
The upgrade also isn’t cheap or flexible on timing. A CFAR add-on runs roughly 3% of your total trip cost and can inflate your overall premium by 40% to 60%. On top of that, most plans require you to cancel at least 48 hours before departure – same-day cancellations don’t qualify at all.
Fast Facts
- Reimburses 50% to 75% of non-refundable trip costs, not 100%
- Add-on typically costs about 3% of your total trip price
- Can raise your overall premium by 40% to 60%
- Usually requires cancellation at least 48 hours before departure
#20 – One Drink Too Many Can Erase Your Medical Coverage
Nobody reads the alcohol clause until they’re already in a hospital bed overseas. Most standard travel insurance plans exclude alcohol-related incidents from coverage outright, and the wording sounds harsher than most people expect until it actually applies to them.
Insurers do have the right to deny a claim based on intoxication, but many will also weigh how much alcohol actually contributed to the incident using the medical evidence available. A slip-and-fall after a couple of cocktails can go either way depending entirely on how a doctor’s report describes what happened – which is exactly why this clause causes so many disputed claims.
#19 – Your Credit Card’s Rental Coverage May Only Kick In Second
Travelers love bragging that their credit card covers rental cars for free. Many don’t realize it’s often a backup plan, not a first line of defense – some cards offer primary coverage that acts immediately, while others only offer secondary coverage that pays after your own auto insurance does.
Secondary coverage means your personal policy has to pay first. If you’re in an accident, you file with your own insurer, wait for that payout, and only then turn to the card’s secondary coverage for whatever’s left. If you don’t even own a car, that “backup” suddenly feels a lot less reassuring than the marketing brochure implied.
#18 – The Adventure Sports List Excludes More Than Just Skydiving
Most travelers think “adventure sports exclusions” mean skydiving and mountaineering. In reality, many standard comprehensive plans quietly exclude activities people don’t consider extreme at all – scuba diving below certain depths, jet skiing, horseback riding, even zip-lining, depending on the insurer’s specific list.
The frustrating part is that the list isn’t standardized across companies. One insurer’s “covered recreational activity” is another’s “hazardous sport” requiring a separate add-on. Travelers who assume a comprehensive plan covers anything active on a vacation are often shocked to learn their snorkeling injury or bike-path accident fell outside the definition entirely.
#17 – Mental Health Claims Face Tighter Limits Than Physical Injuries
Anxiety attacks, panic disorders, and depression-related trip interruptions get treated differently than a broken leg in most policies. Many plans cap mental health-related medical claims at a much lower dollar amount than physical illness, or require the condition to be newly diagnosed rather than pre-existing just to qualify.
This distinction rarely makes it into marketing materials or quick-comparison charts. Travelers managing anxiety, depression, or other ongoing mental health conditions are increasingly advised to call the insurer directly and ask about specific mental health sub-limits before assuming a “comprehensive” plan treats every condition the same way.
#16 – Quarantine Coverage Depends on Being the “Sole Reason” You Can’t Travel
Plenty of travelers bought pandemic-era policies believing any quarantine order would trigger a payout. Many policies attach a stricter condition: the quarantine has to be the sole reason you can’t complete the trip, and it often has to be ordered specifically for you – not a general regional advisory.
That distinction has denied more claims than people expect. A broad government travel advisory or a destination-wide lockdown frequently doesn’t qualify the same way an individual quarantine order does. Travelers who assumed “quarantine” meant blanket protection have been surprised to learn the trigger is far narrower than it sounds.
#15 – Lost Luggage Gets Paid Out at Depreciated Value, Not Replacement Cost
Here’s the detail that infuriates the most claimants: insurers rarely pay what it costs to replace your lost bag’s contents today. Instead, most policies use “actual cash value,” which factors in depreciation based on an item’s age and condition – meaning that two-year-old laptop might come back at a fraction of its original price.
Receipts matter more than people realize. Without proof of purchase date and original price, insurers default to conservative depreciation estimates. Travelers who assume a lost suitcase means a full refund of everything inside are often stunned by how small the final check actually is.
#14 – Per-Item Baggage Limits Hide Inside the Total Coverage Number
A policy advertising “$2,500 in baggage coverage” sounds generous until you read the per-item cap tucked further down the page. Many plans limit any single item – a camera, a phone, a piece of jewelry – to a few hundred dollars, no matter what the total policy limit says.
This is one of the most common surprises adjusters see: a traveler loses an expensive piece of electronics, assumes the full policy limit applies, and instead gets reimbursed at the individual item cap. Reading that specific line item before buying a plan matters far more than most people assume.
#13 – War and Civil Unrest Exclusions Can Erase Coverage Overnight
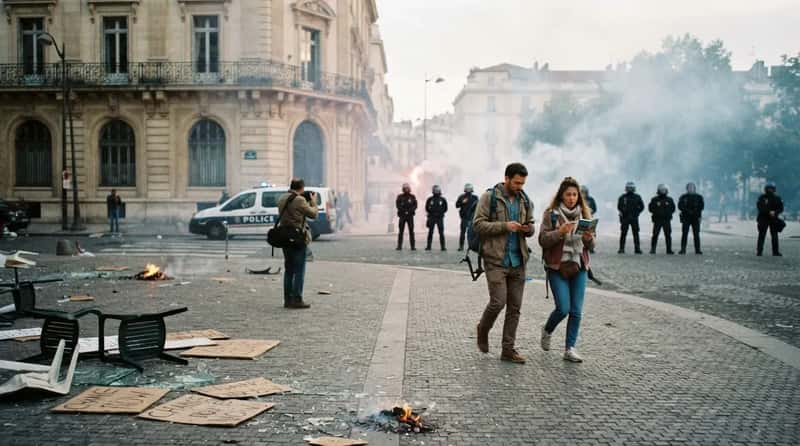
Standard travel insurance almost universally excludes losses connected to war, insurrection, or civil unrest – and that exclusion doesn’t require an official declaration of war to apply. Protests turning violent, sudden government instability, or armed conflict breaking out near a destination can trigger this clause even mid-trip.
Travelers heading to regions with any political tension rarely check whether their policy carves out an exception for this. Some specialty plans do offer limited civil unrest protection, but it’s an add-on most people never think to ask about until news breaks while they’re already abroad.
#12 – Epidemic Exclusions Depend on Whether the Outbreak Is “Named”
Since 2020, insurers have gotten far more specific about disease-related exclusions, and the wording matters enormously. Some policies exclude any loss connected to a “known, existing, or declared epidemic,” while others only exclude outbreaks that existed before the policy was purchased.
That means the same outbreak can be covered under one plan and excluded under another, depending entirely on timing and how the insurer defines “known” at the moment you bought the policy. Travelers assuming pandemic-related protections are uniform across providers are frequently disappointed to learn how narrow, and how differently worded, these clauses really are.
#11 – Emergency Evacuation Sends You to the Nearest Hospital, Not Home
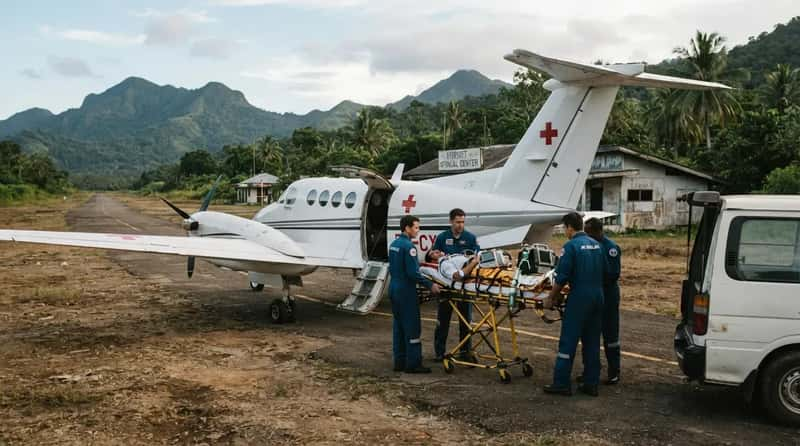
People buy medical evacuation coverage picturing a private jet flying them back to their hometown hospital. That’s rarely how it works. Most policies define evacuation as transport to the “nearest adequate medical facility” capable of treating the condition, which might mean a hospital in a neighboring country, not a flight home.
Only after you’re medically stabilized does repatriation to your home country typically become an option, and even then it’s often subject to a separate, smaller benefit limit. Travelers picturing a direct flight home during a medical emergency are often surprised by how many steps, and how much distance, separate them from that outcome.
#10 – Claim-Filing Deadlines Are Shorter Than Most People Expect
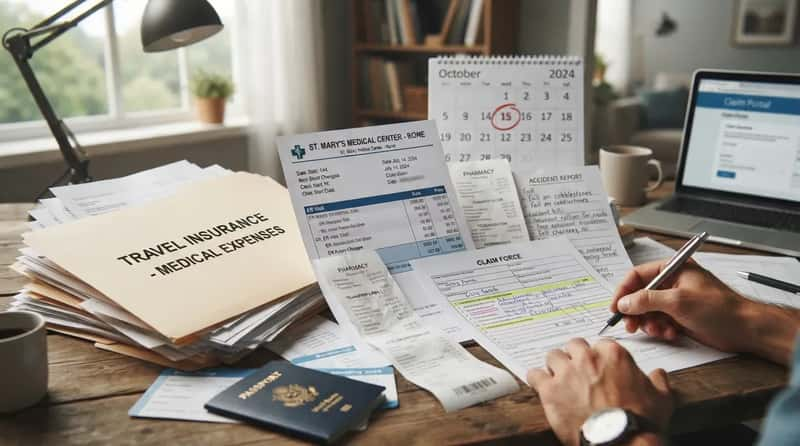
Even a perfectly valid claim can get denied for one reason alone: filing too late. Most policies give you around 90 days to submit a claim, and many travelers don’t realize the clock starts the moment the covered event happens – not whenever they get around to the paperwork.
Documentation requirements add another layer people skip. Insurers typically want itemized medical bills, receipts, accident reports, and proof of payment. Waiting weeks to gather these documents after returning home has quietly cost travelers claims that would have otherwise sailed through.
Worth Knowing
- Most policies allow around 90 days to file a claim
- The clock starts at the moment of the covered event, not when paperwork begins
- Itemized medical bills, receipts, and proof of payment are typically required
- Accident reports can strengthen claims tied to injuries or disruptions
#9 – Missed Connection Benefits Require a Minimum Layover Window
Travelers assume a missed connecting flight automatically triggers reimbursement for hotels, meals, and rebooking costs. Many policies attach a condition first: your original layover has to meet a minimum time threshold, often three hours or more, before the missed-connection benefit even applies.
Book a tight 90-minute connection and get bumped by a delay, and some policies won’t pay a dime toward the disruption – even though it feels identical to what a traveler with a longer layover would experience. It’s a distinction almost nobody checks before booking flights around their insurance policy.
#8 – The Ship’s Doctor on Your Cruise Isn’t Technically “Covered” the Way You Think
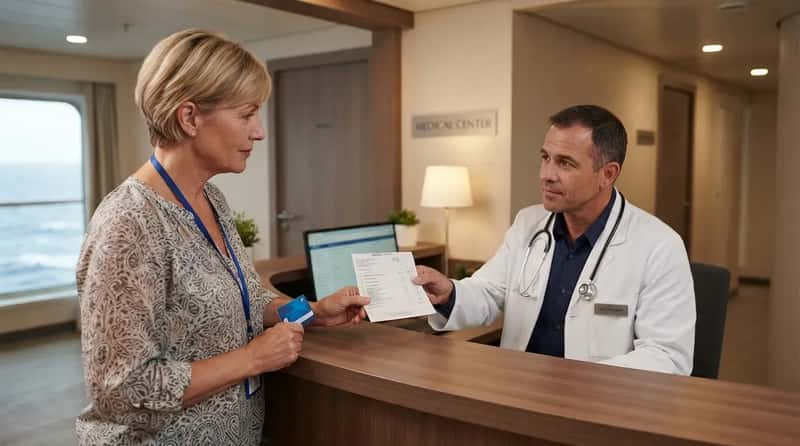
Cruise travelers often assume onboard medical care falls neatly under their travel medical benefits like any other doctor visit. In many cases, ship physicians are independent contractors rather than direct hospital employees, and reimbursement can depend heavily on how that visit gets billed and documented.
This nuance rarely shows up until a traveler is disputing a bill weeks after disembarking. Getting an itemized receipt directly from the ship’s medical center, rather than a vague charge on the final cruise invoice, often makes the difference between a smooth reimbursement and a drawn-out appeal.
#7 – An Exotic or Oversized Rental Car Can Void Your Credit Card’s Coverage
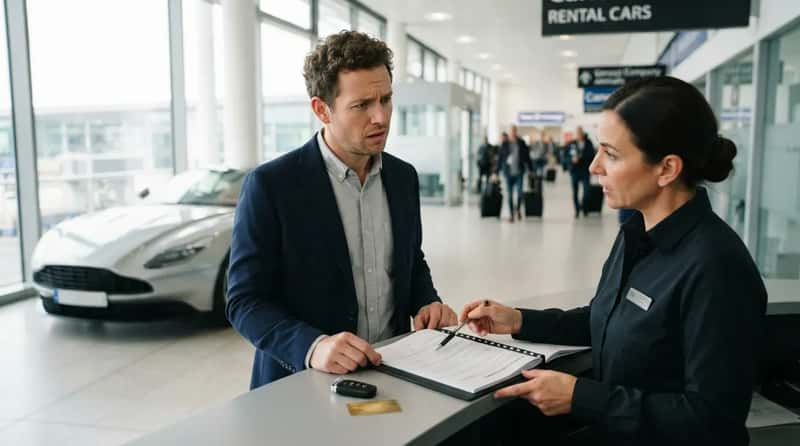
Rent a luxury sedan, a full-size van, or anything remotely “exotic,” and that free credit card rental protection people rely on can disappear instantly. Vehicles like antique cars, exotic cars, and high-capacity vans are commonly excluded from coverage altogether.
International rentals add another wrinkle travelers routinely miss. You may need to buy additional coverage, especially when renting outside the United States. Assuming the same card benefit applies identically at every rental counter worldwide is one of the most common, and costly, misunderstandings in travel.
Quick Compare
- Standard sedan: usually covered under free credit card rental protection
- Luxury or exotic car: frequently excluded outright
- Full-size van or high-capacity vehicle: commonly excluded as well
- International rental: may require purchasing separate coverage
#6 – The “Free Look Period” Lets You Cancel a Bad Policy Penalty-Free
Almost nobody knows this exists, yet it’s one of the most useful protections in the entire industry. Most comprehensive plans include a short window, often 10 to 15 days after purchase, during which you can cancel entirely for a full refund – as long as you haven’t started your trip or filed a claim.
This “free look period” is designed to let travelers actually read the policy before being locked in, which is exactly what most people skip doing. Discovering a better plan, or a dealbreaker exclusion, within that window means you can switch without losing a single dollar – but only if you know the window exists in the first place.
#5 – Repatriation of Remains Has Its Own Separate, Smaller Limit
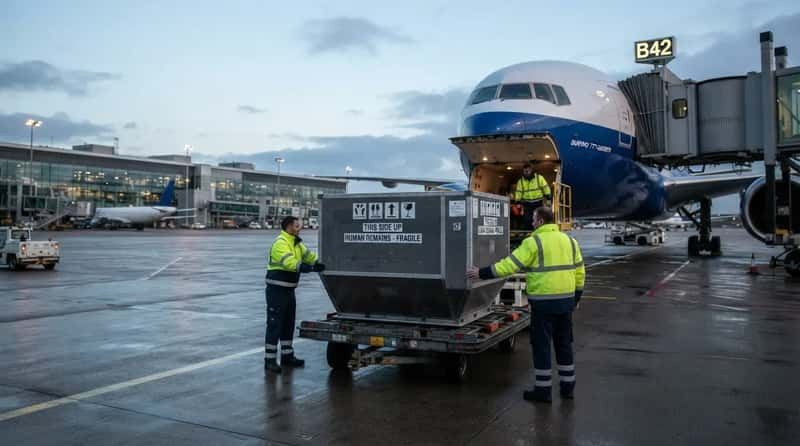
It’s an uncomfortable detail, but a critical one: the benefit covering emergency medical evacuation is almost never the same benefit that covers returning a traveler’s remains home in the event of death abroad. That’s typically a distinct line item, often with a noticeably lower coverage cap than the medical evacuation limit.
Families dealing with this scenario are frequently shocked to discover the shortfall exists at all, especially since international repatriation costs can run well into five figures depending on the country and logistics involved. It’s one of the least discussed numbers in any policy, precisely because nobody wants to think about needing it.
#4 – “Covered Reasons” for Cancellation Are a Narrower List Than People Assume
Standard trip cancellation coverage doesn’t reimburse you for changing your mind, work getting busy, or simply not feeling up to the trip anymore. It only pays out for specific reasons named in the policy – illness, severe weather, certain job losses, and a handful of others.
This is precisely why CFAR upgrades exist in the first place, because the base list frustrates so many travelers. Cancel For Any Reason exists specifically to cover the gaps standard coverage won’t touch, with certain restrictions attached. Anyone who skips reading the “covered reasons” list is essentially gambling on whether their specific circumstance happens to be one of the handful the insurer actually names.
#3 – Multiple Policies Don’t Simply “Stack” – One Usually Pays First
Travelers who buy a standalone travel medical plan while also holding credit card travel benefits often assume both will pay out fully. In practice, insurers coordinate benefits, meaning one policy is typically designated primary and pays first, while the other only covers costs left over, if it pays at all.
This coordination clause is buried deep in policy documents and rarely explained clearly at the point of purchase. Figuring out which of your overlapping benefits is primary before a claim happens, rather than during a stressful emergency abroad, can prevent a lot of confusion about why a “second” policy paid far less than expected.
#2 – Cash, Jewelry, and Electronics Often Face Blanket Sub-Limits
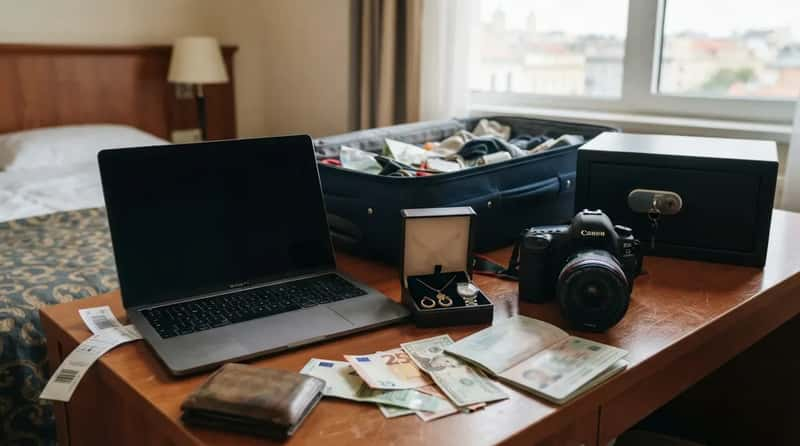
Baggage coverage sounds broad until you notice the carve-outs for specific categories of items. Cash is frequently excluded entirely or capped at a token amount, while jewelry, electronics, and even sports equipment often face their own separate, and much lower, sub-limits regardless of the policy’s total baggage figure.
This is where high-value travelers get caught off guard most often. Someone traveling with a laptop, a camera, and a piece of jewelry can easily exceed the combined sub-limits without realizing it, since the total looks generous on paper while the category-specific caps quietly do the real work of limiting payouts.
#1 – Miss the Purchase Window, Lose Pre-Existing Condition Protection Forever
This is the detail insurance agents say costs travelers the most money, and it comes down to timing most people never think to check. To qualify for a pre-existing condition waiver, you typically need to buy coverage within 14 to 21 days of your initial trip deposit, and insure 100% of your prepaid, non-refundable trip costs.
Miss either requirement – buy the policy a day too late, or insure only part of the trip cost – and the waiver disappears for that trip entirely. There’s no appeal, no grace period, and no second chance once that window closes, which is exactly why experts say this one overlooked rule causes more denied claims than almost anything else in the entire policy.
At a Glance
- Waiver window: typically 14 to 21 days after your initial trip deposit
- Requirement: insure 100% of prepaid, non-refundable trip costs
- Miss the window: the waiver disappears for that trip, no exceptions
- No appeal or grace period exists once the window closes
Travel insurance isn’t designed to trick anyone, but it is written by people who assume you’ll read every page – and most travelers simply don’t. The gap between what people believe their policy covers and what the actual contract says is where the vast majority of denied claims come from.
Knowing these 22 details before you buy, not after you file a claim, is the difference between a policy that actually protects your trip and one that just feels like it does. Which one caught you off guard the most? Chances are you’re not the only one who didn’t know.