Moving abroad used to be mostly about weather, cost of living, or a slower pace of life. These days, tax policy has become just as big a factor in that decision, especially as governments compete for remote workers, retirees, and wealthy individuals looking for a new base. Several countries have built entire immigration strategies around offering reduced rates or flat fees on foreign income, though the rules keep shifting as budgets tighten and political pressure grows.
What follows is a rundown of seven countries currently running formal tax incentive programs for new foreign residents, along with what changed heading into 2026 and who each program actually suits.
Portugal’s IFICI regime, the successor to NHR
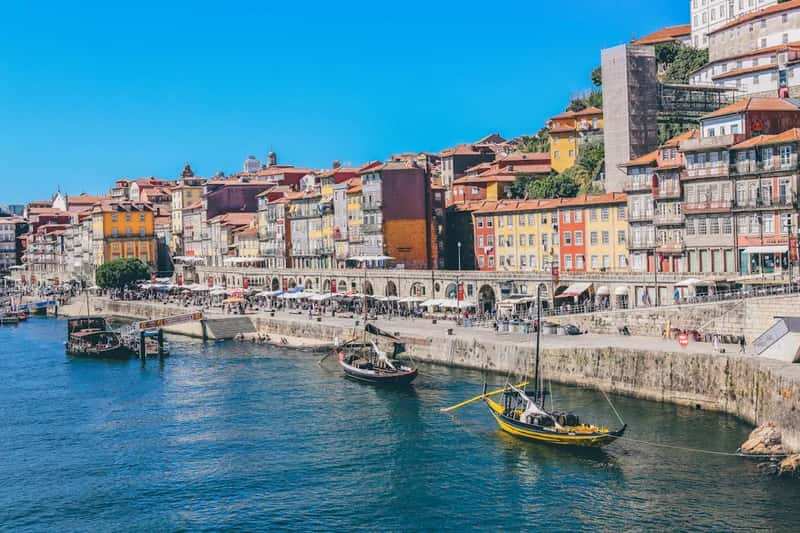
Portugal’s famous Non-Habitual Resident program is gone. The original NHR stopped accepting new applicants in January 2024, and the last transition window shut in March 2025. In its place sits a narrower scheme called IFICI, unofficially known as NHR 2.0, which trades broad accessibility for a tighter focus on specific professions.
The IFICI regime is Portugal’s current tax incentive for new residents, offering a 20% flat income tax rate on qualifying Portuguese employment income, plus exemption on most foreign-sourced income, for up to 10 consecutive years. The catch is eligibility. The government has shifted focus from attracting anyone seeking tax relief to drawing in highly-skilled individuals who can contribute directly to the country’s strategic sectors such as research, technology, and higher education. Anyone who registered under the old NHR rules before the cutoff keeps their original ten-year benefits regardless of the change.
Italy’s flat tax for high-net-worth newcomers
Italy runs one of Europe’s most talked-about relocation incentives, and it just got considerably more expensive to access. Effective January 1, 2026, Italy’s substitute flat tax on foreign-source income for high-net-worth new residents increased from €200,000 to €300,000 per year, with the family member surcharge doubling from €25,000 to €50,000. That’s on top of an earlier jump from the original €100,000 rate introduced back in 2017.
The mechanics remain straightforward even if the price tag has tripled. Your total tax bill on worldwide earnings would be capped at the flat rate, regardless of whether you earned a million or a billion euro, in lieu of standard Italian tax rates. The regime can last for up to 15 years and gives you several benefits, including exemption from wealth taxes on foreign assets and no requirement to report holdings held outside Italy. It’s clearly no longer aimed at the merely comfortable, but for people with genuinely large foreign income streams, the math still works out favorably.
Greece’s flat tax options for retirees and investors
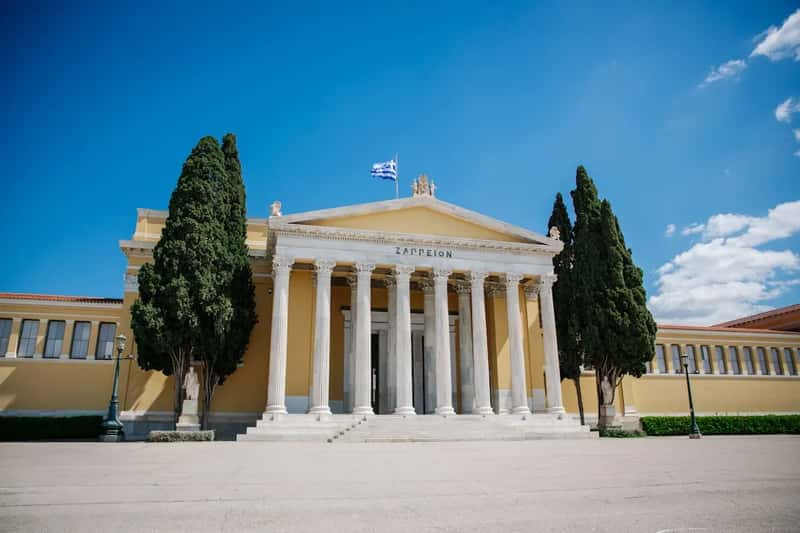
Greece keeps things relatively simple compared to its neighbors, running parallel programs depending on whether someone is retired or simply wealthy. Introduced in 2020 and enhanced since, this regime allows foreign pensioners and retirees moving their tax residency to Greece to pay a flat tax rate of 7% on all foreign-source income, for 15 years. There’s no investment requirement attached to the pensioner track, which sets it apart from most comparable European schemes.
For those with deeper pockets, a separate non-dom path exists. High-net-worth non-doms can pay a flat annual tax of €100,000 on all foreign income, and the non-dom status lasts for up to 15 years under this regime. To qualify for the pensioner rate, applicants generally have not been a Greek tax resident for 5 of the past 6 years, and income earned locally within Greece still falls under the country’s regular progressive tax brackets.
Spain’s Beckham Law for relocating professionals
Named informally after the footballer who used it after joining Real Madrid, Spain’s special expatriate regime has quietly become one of the more flexible options in Europe. This offers a preferential tax treatment to expatriates, allowing them to be taxed at a flat rate of 24% on their Spanish-sourced income rather than the standard progressive tax rates applicable to worldwide income, which can range from 19% to 45%. That benefit runs for six tax years starting from the move.
Eligibility has loosened somewhat in recent years. Applicants must not have been a tax resident in Spain for the five years prior to moving, and must relocate to Spain for work purposes, such as with a job offer, intra-company transfer, or digital nomad visa. Standard freelancers billing local Spanish clients are still excluded, though those working remotely for foreign employers under the digital nomad visa framework can often qualify, which has made the regime increasingly attractive to remote tech workers rather than just corporate transferees.
Cyprus and its long non-dom exemption window
Cyprus takes a different approach entirely, skipping the flat annual fee model in favor of an extended exemption period. Residents who are not domiciled in Cyprus pay 0% Special Defence Contribution on dividends, interest, and rental income, regardless of source, for the first 17 years of Cyprus tax residency, provided the individual was not resident in Cyprus in 17 of the 20 years preceding the application. That’s an unusually generous window by European standards.
Cyprus tightened up residency rules slightly at the start of 2026 while extending the program’s long-term appeal. As of a change effective 1 January 2026, applicants no longer need to prove they are not a tax resident elsewhere, and dual tax residency is now permitted. Those who reach the end of the initial period aren’t necessarily done either. From 2026 onwards, after the initial 17 years, non-doms whose domicile of origin is outside Cyprus can extend the exemption for two consecutive five-year periods at a €250,000 lump-sum payment per extension.
Malta’s residence programs for retirees and remittance-based taxpayers
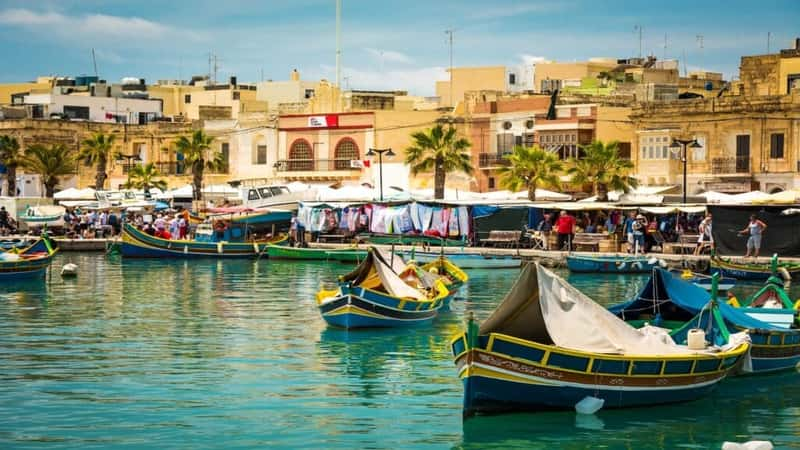
Malta relies on a remittance basis of taxation, meaning what matters is not where income is earned but whether it’s actually brought into the country. Foreign income kept offshore is not taxed in Malta, foreign income brought into Malta is taxed at 15%, and Malta-source income is taxed at normal rates. This structure has made Malta a longstanding favorite for people with diversified international income who don’t need to spend all of it locally.
For retirees specifically, Malta runs a dedicated scheme with its own flat structure. The Malta Retirement Programme is specifically for retired individuals in receipt of pension income, offering a 15% flat rate on pension income received in Malta, with a minimum tax of €7,500 per year for the main applicant and €500 for each dependant. On the general residence side, the minimum tax of €15,000 applies regardless of how much foreign income is remitted, which effectively sets a floor cost for participating even for those who bring in relatively modest amounts.
The United Arab Emirates and its zero personal income tax model
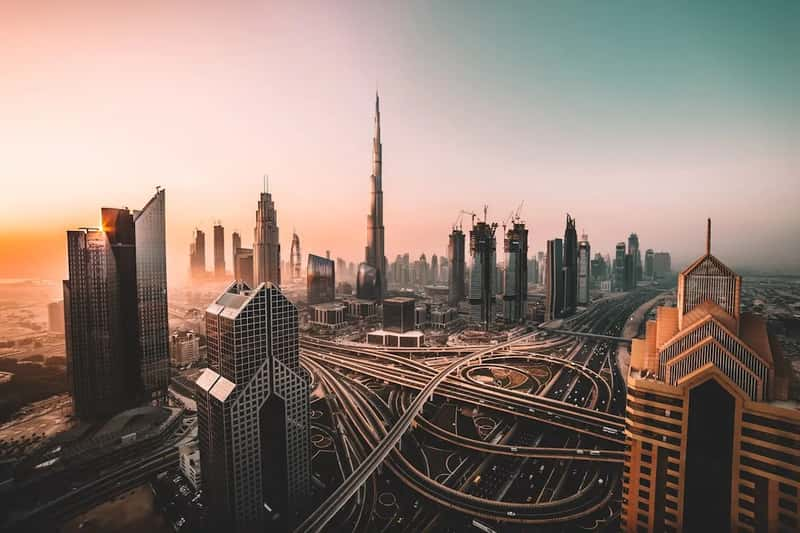
The UAE doesn’t offer a special program so much as a national policy that happens to be extraordinarily attractive to relocating professionals and investors. The UAE remains the most popular global solution, as there is still no personal income tax for individuals. There’s no separate application process or qualifying activity required, since the zero rate applies broadly across the resident population.
The details underneath that headline figure are worth knowing too. Personal income tax sits at 0% on all income, capital gains tax is 0%, inheritance tax is 0%, dividend and interest tax is 0%, while corporate tax is 9% on profits exceeding roughly 375,000 dirhams, with qualifying free zone entities taxed at 0%. The main exception that trips people up involves American citizens, since US persons still owe US taxes and UAE income must be reported on US tax filings regardless of where they physically live, a reminder that domestic tax obligations rarely disappear just because someone changes their address.
None of these programs are static, and several have already gotten more restrictive or more expensive within the past two years alone. Portugal narrowed its scope to skilled professionals, Italy tripled its entry price for wealthy applicants, and Cyprus adjusted its residency proof requirements even while extending its exemption window further than before. Anyone seriously considering a move for tax reasons should treat these details as a starting point for professional advice rather than a final answer, since eligibility rules, minimum stays, and family provisions vary enough between countries that a program that works well for one person’s situation can be a poor fit for someone else’s.