Most travelers over 60 assume a travel insurance policy works like their health plan: you get sick, it pays. It doesn’t. A handful of buried clauses decide whether a claim gets paid or denied, and some of them come with deadlines that start ticking the day you make your first deposit.
The brochure shows a smiling couple on a beach. The contract tells a different story, one written in definitions, look-back windows and dollar caps. Stick around for the clause with the shortest fuse. It’s saved for last, because it’s the one that catches the most people.
#13 – The “Free Look” Window Most People Let Expire
Many insurers give you a short review period after you buy, often around 10 to 14 days. During that time you may be able to cancel for a full refund. The exact length depends on the insurer and your state, and it usually disappears once you file a claim or your trip begins.
Here’s the catch. Most buyers never read the contract until something goes wrong, and by then the review window is long closed. Print or save a copy of the terms the day you buy online. Read the whole thing while the window is open, and you can walk away from a bad fit at little or no cost.
At a Glance
- Typical review period: around 10 to 14 days, depending on insurer and state
- Usually ends once you file a claim or your trip starts
- Best move: save the full terms the day you buy
- Payoff: a possible full refund if the policy is a bad fit
The next clause quietly shrinks what you get back for your belongings…
#12 – The Baggage Cap That Doesn’t Match Your Camera
Baggage coverage sounds simple until you read the sub-limits. Policies commonly set a maximum per item, plus a separate, lower cap for jewelry, cameras and electronics. A new tablet or a good camera can be worth far more than the policy will ever pay.
Many policies also reduce or deny payment for valuables left unattended or packed in checked luggage. That means the items you worry about most are often the ones with the weakest protection. Check whether prescription eyewear and hearing devices are named or excluded, and whether payment is based on depreciated value rather than replacement cost.
And the clause that follows can leave you stuck at a gate with nothing to show for it…
#11 – The Trip Delay Clock That Starts Late
Trip delay benefits don’t kick in the moment your flight slips. Most policies require the delay to pass a minimum number of hours before anything is payable. That threshold varies by plan, and it can be several hours.
Then come the daily caps and the paperwork. Plenty of travelers sit through a long, exhausting delay and learn the policy only reimburses receipts, and only after the threshold is met. Look for what counts as a “covered reason,” since weather and airline staffing problems are often treated differently. Keep every meal and hotel receipt.
Next comes one tiny word that decides who pays first, and it can mean months of waiting…
#10 – “Primary” vs. “Secondary”: The One Word That Decides Who Pays First
A primary policy pays first. A secondary medical policy pays only after your other coverage has paid or denied the claim. That single word can change how fast your money comes back.
It matters because providers abroad sit outside any U.S. network and often want payment upfront, sometimes in cash. If your policy is secondary, you may have to file with another insurer first. You could be fronting thousands of dollars while two companies trade paperwork. Ask which type you’re buying before you hit “purchase.”
The next exclusion tends to surprise people most on a sunny day at the port…
#9 – The “Hazardous Activity” List Hiding in Your Shore Excursion
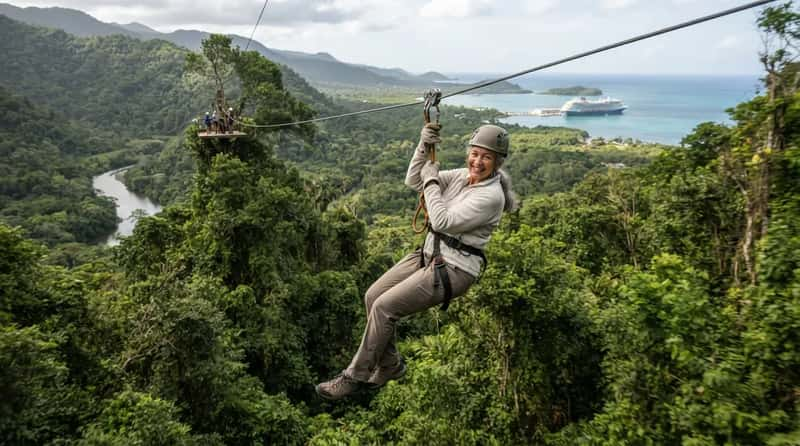
You might picture “dangerous activities” as bungee jumping. Policies often define them much more broadly. Depending on the plan, scuba diving, zip-lining, off-road rides or mountain hiking at altitude can be excluded or require an add-on.
Here’s what most people don’t realize. A single excursion booked on a whim can void the medical benefit for any injury that happens during it. Many policies also deny claims tied to alcohol use. Read the exclusions page, then compare it with every excursion on your itinerary. If one is excluded, ask about an adventure upgrade.
Worth Knowing
- Scuba, zip-lining, off-road rides and high-altitude hikes are common trouble spots
- Alcohol-related injuries are often excluded
- Some insurers sell an adventure add-on for excluded activities
- Check the exclusions page against your excursion list before you book
The next clause is about people who aren’t even on the trip…
#8 – Whose Illness Counts? The Family Definition Trap
Trip cancellation benefits often cover a serious illness in a family member. That sounds comforting, but every policy defines “family” differently. Some lists stop at spouses, children and parents. Others add siblings, grandchildren, in-laws or even a travel companion.
Now think about your own life. If a sibling or grandchild you’re close to isn’t on the list, their hospital stay may not be a covered reason to cancel. The relative’s own health history may also be tested against the policy’s look-back rules. Check the definitions section, not the glossy summary, before you assume your people are covered.
Still, the next clause can price some travelers out before they even reach checkout…
#7 – The Age Wall Nobody Mentions Until Checkout
Age is built into both pricing and eligibility. One senior-focused guide notes that standard policies can become prohibitively expensive, or exclude coverage entirely, after age 70 to 75. Some plans have hard upper age limits, and others simply charge far more.
That can tempt older travelers to grab the cheapest option on the screen. One review of senior plans warns that premiums climb steeply past age 75, even on policies with no upper age limit. Check whether benefit limits shrink at older ages, not just whether you’re allowed to buy at all.
Fast Facts
- Standard policies can get pricey or unavailable somewhere between 70 and 75
- Some plans set a hard upper age limit
- Others stay open but charge steeply more past 75
- Ask whether benefit caps drop as you age
And the next clause involves a program many Americans assume will bail them out…
#6 – The Medicare Myth That Ends at the Border
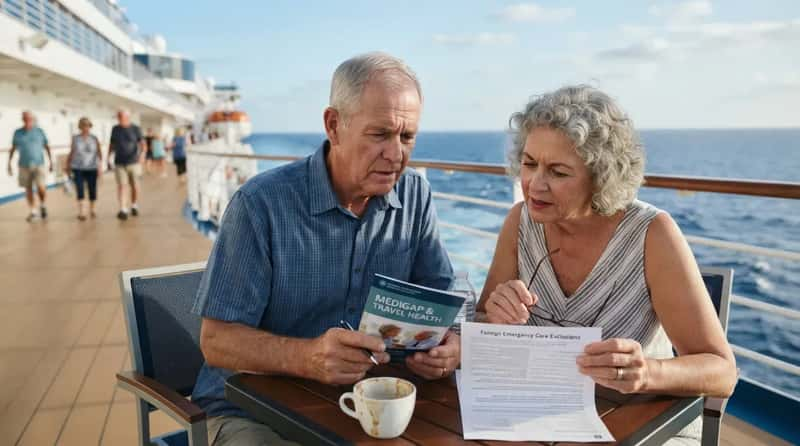
Plenty of retirees assume Medicare follows them overseas. It doesn’t. Beyond a few narrow exceptions, Original Medicare won’t pay for care abroad. One exception involves cruises: you may be covered if the ship is within six hours of a U.S. port.
Medigap helps, but only a little. Some plans cover 80% of emergency costs abroad, but only up to a $50,000 lifetime limit and within the first 60 days of a trip, after a $250 deductible. That lifetime cap is shared across every trip you ever take. Snowbirds and long-haul cruisers can run into the time limit and still face a bill.
Now for the number on the next clause, the one that decides how big a bill you could survive…
#5 – The Medical Limit That Looks Big Until the Hospital Bill Arrives
Many travelers choose a policy by price and only glance at the medical limit. That’s where the trouble starts. One guide says $50,000 to $100,000 may suit a healthy 30-year-old but leaves real exposure for seniors, since treatment tends to be longer and more complex.
Plenty of agents tell older travelers a basic policy is “good enough.” Some travel insurance guides push back, suggesting at least $250,000 in travel medical benefits and $500,000 for medical evacuation. The cheapest policy on the screen is often the one with the smallest cushion. Also check whether the limit is per trip, per person or shared.
Quick Compare
- Healthy 30-year-old: $50,000 to $100,000 in medical coverage may be enough
- Senior traveler: at least $250,000 in medical benefits is often suggested
- Medical evacuation: $500,000 is the figure some guides recommend
Next up is a benefit that can cost more than a house down payment…
#4 – The Evacuation Clause: Where “Medically Necessary” Gets Decided
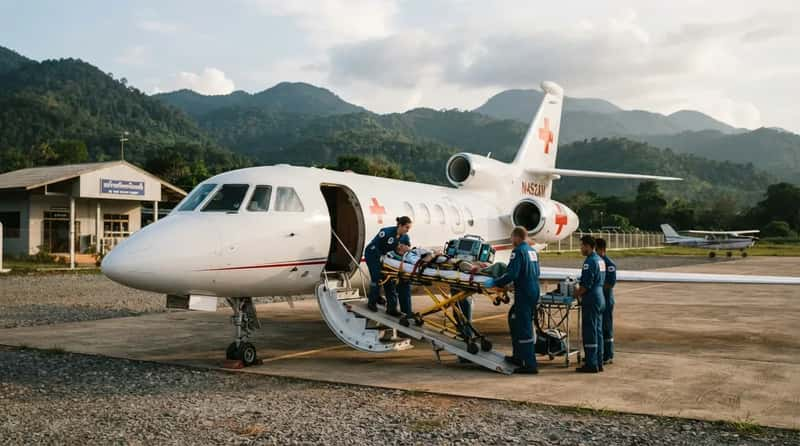
Evacuation is the benefit travelers think about least and need most. Most health plans don’t pay for special air ambulance transport back to the U.S. A travel policy might, but the fine print matters.
Look for who decides what’s “medically necessary.” Some policies move you to the nearest adequate facility, which may not be the hospital near your home. Ask whether a trip home is covered, and whether the insurer’s own medical team has to approve the transfer first. A missed pre-approval step can sink an otherwise valid claim.
And then there’s the add-on that sounds like a safety net and works more like a partial refund…
#3 – “Cancel for Any Reason” Isn’t Actually Any Reason
The name promises total freedom. The terms are narrower. Cancel for any reason (CFAR) coverage typically reimburses 50% to 75% of non-refundable trip costs, and you usually must cancel at least 48 to 72 hours before departure.
There are strings on the purchase, too. Most plans require you to buy within 10 to 21 days of your first payment and to insure 100% of your prepaid, non-refundable costs. It isn’t available in all states, including New York and Washington. One insurer notes that it can add 40% to 60% to the cost of a standard policy.
- Buy it within the window after your first deposit.
- Insure all prepaid, non-refundable costs.
- Cancel before the cutoff, usually 48 to 72 hours.
Now for the clause that decides whether your own medical history works against you…
#2 – The Look-Back Period That Quietly Defines “Pre-Existing”
Insurers don’t just ask whether you have a condition. They ask whether you were treated for it recently. Look-back periods usually run 60 to 180 days before you buy, and anything treated or medicated in that window can count as pre-existing.
This is where managed conditions trip people up. Standard rules look for no new treatment, prescription changes or new symptoms during the window. A simple dosage change for blood pressure, made a few weeks before buying, can change how an insurer classifies you. Ask for the exact window in days, and check what counts as a “change.”
Now for the clause that matters most, and the one with the shortest fuse…
#1 – The Pre-Existing Condition Waiver Clock Starts at Your First Deposit
This is the big one. Most policies exclude pre-existing conditions unless you qualify for a waiver. That usually means buying within 14 to 21 days of your first trip or cruise deposit. It doesn’t matter whether the trip is next month or 18 months away; the deposit date starts the clock.
Miss it, and the exclusion generally stays. One senior-focused review says this narrow timing trips up more older travelers than almost anything else in the market. Waivers typically also require that you’re medically able to travel at purchase and that you insure the full non-refundable trip cost. Without the waiver, claims tied to a known condition like heart issues, diabetes or arthritis can be denied.
The most expensive surprises in senior travel insurance rarely hide in big print. They hide in deadlines, definitions and dollar limits, the parts nobody reads while they’re picturing the beach.
So the next time a policy looks thorough, flip past the glossy summary and find the clocks. The trip you’ve been dreaming about is only as protected as the page nobody wanted to read.