The first trip after retirement is supposed to be the victory lap. The savings are there, the calendar is wide open, and nobody is waiting on an email. Then the real stories start coming in: an overstuffed suitcase hauled up a cobblestone street at midnight, a pill bottle lost somewhere between two airports, a Medicare card that turns out to be useless in another country.
Retirees and the experts who work with them keep naming the same regrets. Some are cheap to fix. A few can cost tens of thousands of dollars. And the one at #1 has almost nothing to do with spending too much, which is what most careful savers expect it to be.
#12 – The Suitcase That Turned a Dream Trip Into a Workout
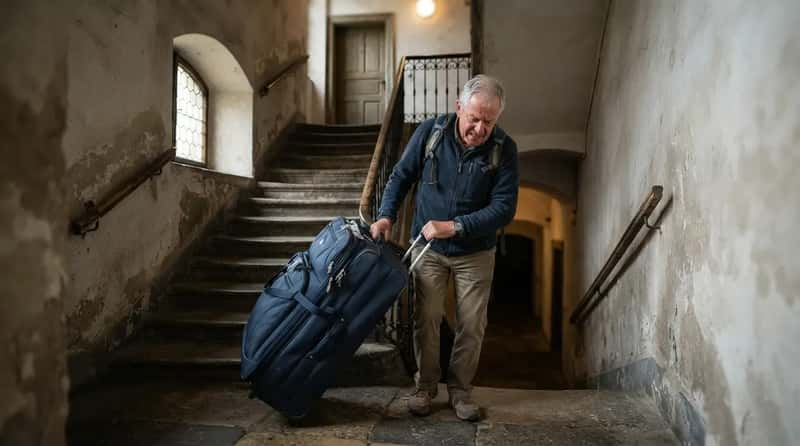
That “just in case” outfit is the first thing many retirees wish they’d left at home. A tour operator that works with older travelers lists overpacking as a common mistake. Heavy suitcases create stress at airports, hotels, train stations, and cruise terminals. The bag you can barely lift soon becomes the thing you think about most.
Here’s what seasoned travelers eventually learn. You need far less than you think. The advice is to pack versatile clothing, comfortable walking shoes, and only what you’ll realistically use. Old city centers and small hotels don’t always have elevators, so every extra pound gets carried by you, one step at a time.
But the next mistake costs real money before you even reach the gate.
#11 – The $80 Card Many Retirees Never Pick Up
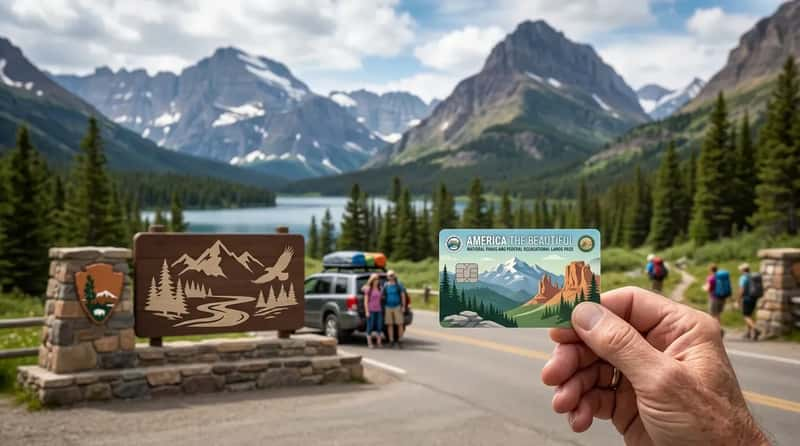
Plenty of road-tripping retirees pay full price at the park gate for years. U.S. citizens and permanent residents aged 62 and older can buy an annual national parks pass for $20 or a lifetime version for $80. The eligibility age is 62, not 65, so some people wait three extra years for a pass they already qualify for.
The pass covers entry to more than 2,000 federal recreation sites. That includes lakes and reservoirs run by the Army Corps of Engineers. At per-vehicle fee sites it admits the pass holder plus passengers in one vehicle, and it can take 50% off some amenity fees like camping. It generally doesn’t cover special permit fees or concessioner charges, and you can’t buy it as a gift because the recipient has to show proof of eligibility.
Still, park fees are small compared with the costs nobody writes into the trip budget.
#10 – Resort Fees, Tips and the Costs Nobody Budgeted
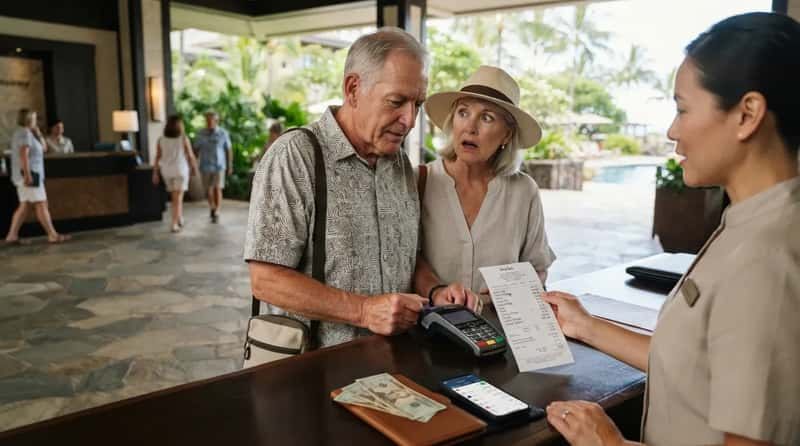
The nightly rate on the booking page is rarely the real price. One retiree who writes about travel says she missed resort fees, tips, and transportation costs while planning. She had no idea how fast those “little” costs add up. Her fix was a full budget that includes insurance, food, and activities, with room left over for surprises.
Prices keep moving too. Data cited in one retirement-travel analysis showed some travel costs, including airfare, fuel, and accommodation, rising faster than broader inflation. Money that comfortably covers a holiday today may not stretch nearly as far in the future. That matters most for anyone pricing a trip years ahead on old numbers. Check current rates before you commit.
Worth Knowing
- Resort fees often sit on top of the advertised nightly rate, so look at the final total before you book.
- Tips for drivers, guides, and hotel staff can add up fast over a multi-week trip.
- Airport transfers, taxis, and rail tickets are easy line items to forget.
- Insurance, food, and activities belong in the budget from day one, with a cushion for surprises.
Meanwhile, one small item in your carry-on can cause trouble that no budget fixes.
#9 – The Prescription Bottles in the Checked Bag
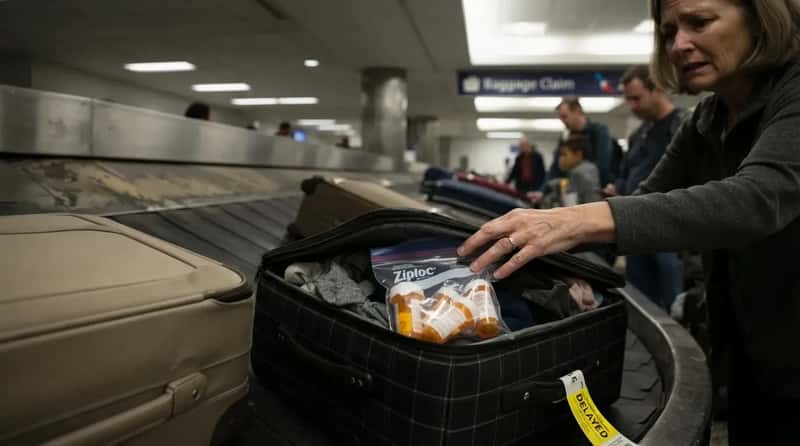
It sounds too obvious to be a mistake, and that’s exactly why it keeps happening. Keeping medications in your carry-on feels like common sense in hindsight, and it becomes a disaster when ignored. Checked luggage gets lost, delayed, or sent to the wrong city.
Your bag may catch up in a day or two. Your blood pressure pills don’t have that kind of patience. Replacing medication abroad is harder than most retirees expect, because Medicare Part D prescription drug plans do not cover drugs purchased outside the United States. A lost refill can turn into a pharmacy hunt, a language barrier, and a bill you pay entirely yourself. Pack a little extra in case your return flight is delayed, and keep it all in your own bag.
Next up is a mistake that starts months before you leave, and it has nothing to do with packing.
#8 – The Walking Tour That Ended on a Hotel Bed by 2 p.m.
Travel is more physical than the brochure photos suggest. Airport terminals can be enormous, and historic districts often mean miles of uneven pavement. Museums, national parks, and guided tours can keep you on your feet for hours.
Day one is when many first-time retiree travelers find out their legs weren’t ready. The fix isn’t a marathon, since you don’t need to train hard, but keeping a reasonable level of activity beforehand makes a real difference. Aging does limit some travel activities. One retired couple even suggests saving things like mountain climbing and long snorkeling sessions for when you’re younger. Choosing trips that match your stamina is smart planning, not giving up.
But there’s an itinerary habit that wears out even the fittest retirees.
#7 – Five Cities in Seven Days: The Itinerary That Backfires
The classic first-trip blitz looks great on paper. Travelers plan five cities in seven days, schedule every hour, and race from one attraction to the next. Some tour operators now argue that this is exactly backwards for retirees. One says travel shouldn’t feel like work.
Retirees who’ve done it describe the same pattern. The first big trip often has too many destinations, too many overnight moves, and too many cities rushed through like checkboxes. The old two-week vacation window is gone, so speed no longer helps you. Fewer stops and longer stays are often what people end up remembering.
And sometimes the dream destination itself turns out to be the problem.
#6 – The “Dream Town” That Looked Different After Two Weeks
A great vacation spot is not always a great place to live. Kiplinger warns about retirees who head to a supposed dream destination and find it’s closer to a nightmare. The pace is too slow, everyone is a stranger, and endless golf and beach walks get old fast. The first trip is often where that realization starts.
There’s even a nickname for people who reverse course. “Halfback retirees” head to the Deep South, don’t like it, and move halfway back toward their old home in the north. Kiplinger’s advice is to spend extended vacation time at the destination before you retire, to get a feel for the people and the lifestyle. A first trip is a cheap way to test that idea.
Then there’s a mistake that can turn a trip awkward in the first five minutes.
#5 – The Etiquette Slip-Ups That Change How Locals Treat You
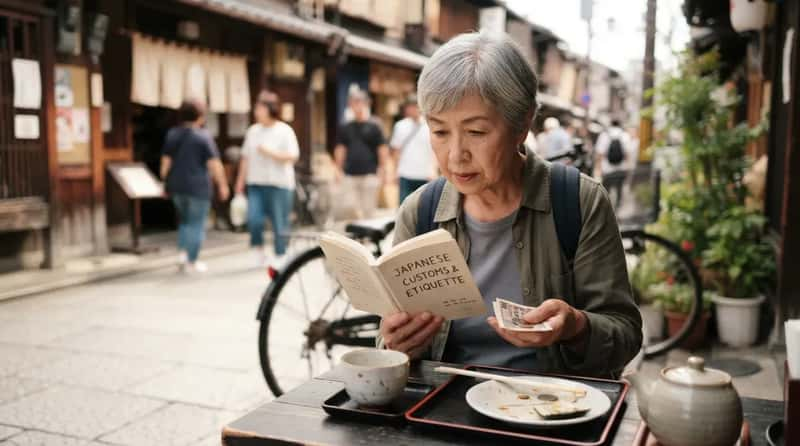
Some travelers believe they shouldn’t have to adjust to anyone. Retirees who’ve learned otherwise tend to disagree. One new retiree admits local traditions didn’t interest her at first. She learned that even small misunderstandings can lead to embarrassing or offensive moments.
Tipping is the classic trap, since norms vary widely from country to country. Her advice is to research local customs, tipping habits, and a few simple phrases in the local language. It’s respectful, and it often gets locals to treat you better. A few evenings of reading before you fly can change the whole feel of a trip.
Fast Facts
- Tipping rules differ by country. Some places expect little or none, while others add a service charge to the bill.
- Four phrases go a long way: hello, please, thank you, and excuse me.
- Many churches, temples, and mosques ask visitors to cover shoulders and knees.
- Meal times vary too. Dinner in Spain, for example, often doesn’t get going until after 9 p.m.
That brings us to a safety net many retirees buy too cheaply.
#4 – The Cheap Travel Insurance That Fails When You Need It
Insurance feels optional right up until it isn’t. One retiree says she took it lightly when she was younger, but retirees are more likely to face medical issues or trip interruptions. Her warning is that cheap coverage can backfire. She recommends a policy that covers overseas medical care and trip cancellation.
The cost of going without can be steep. One insurer estimates a hospital stay in Europe at $10,000 to $50,000 and an emergency evacuation to the U.S. at $25,000 to $250,000. Original Medicare generally does not pay for medical evacuation from another country. Those figures come from a company that sells the product, so treat them as ballpark numbers and read every policy’s exclusions.
And the card in your wallet is the next surprise.
#3 – The Medicare Card That Means Nothing Overseas
This is the one that catches the most retirees off guard. Original Medicare doesn’t cover healthcare outside the United States. That includes Canada, Mexico, and Europe: if you need care there, Parts A and B generally won’t pay. Medicare Advantage plans typically don’t cover care abroad either, though some include limited emergency coverage with terms that vary widely.
The exceptions are narrow and oddly specific. Medicare may cover a Canadian hospital if you’re on the most direct route between Alaska and the lower 48 and it’s closer than a U.S. facility. Another exception covers care on a ship within U.S. territorial waters. The State Department also advises travelers to check their health insurance before leaving.
Yet the most painful mistake isn’t about coverage. It’s about money, and when you spend it.
#2 – Spending Like Every Trip Is the Last One
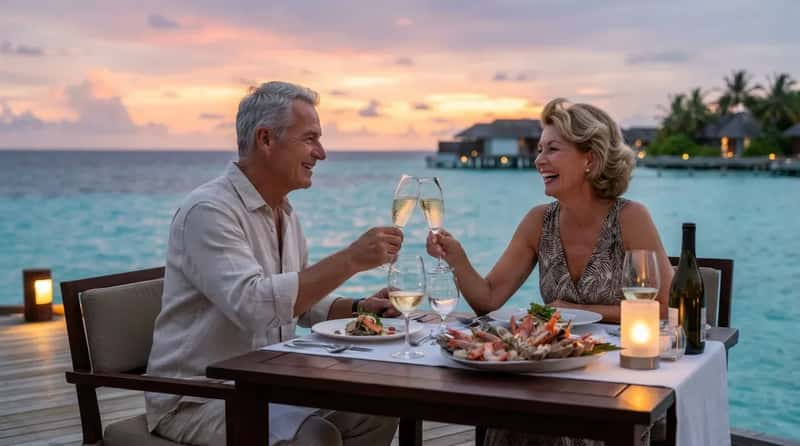
The early years of retirement are sometimes called the “go-go years.” Retirees are generally healthier, more active, and more willing to spend on experiences they postponed for decades. That excitement is completely understandable. But spending too much early in retirement can create problems later.
The danger is bad timing. Large withdrawals in the first years after leaving work are risky, because if markets fall at the same time, a portfolio may struggle to recover. That’s not an argument against going. It means a big trip should be priced against your whole retirement plan, not just this year’s balance. A financial adviser can run that math in an afternoon.
Quick Compare
- Splurge first: Big early withdrawals feel great now, but a market dip at the same moment can leave a portfolio struggling to recover.
- Pace it out: Spreading bigger trips over several years gives your savings room to breathe.
- Plan it whole: Price the dream trip against your full retirement plan, then have an adviser run the numbers.
Still, the most common regret has nothing to do with overspending.
#1 – Waiting for “Someday”
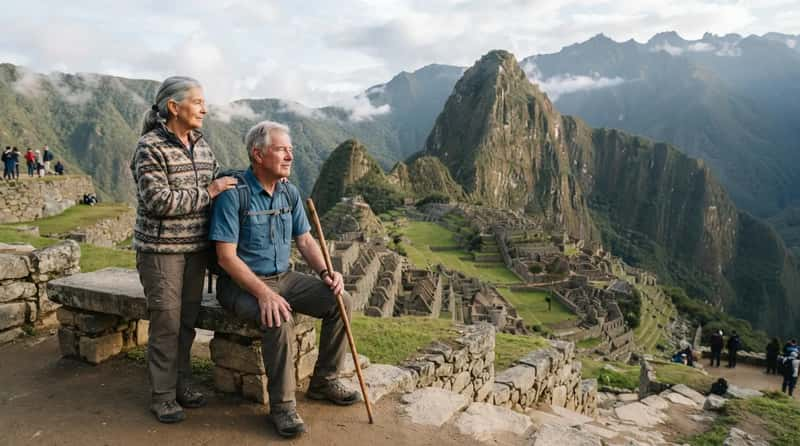
Cautious savers hate hearing this, but the loudest regret isn’t spending too much. One financial advisory firm says retirees rarely wish they’d saved more after retiring. More often they regret waiting. Many plan to travel “someday,” and health problems often become the limit before money does.
The firm gives a hypothetical example. A couple delays international travel for eight years over market worries. By the time they feel financially comfortable, one spouse has mobility challenges that make those trips much harder. It’s an illustration, not a survey, but it matches what other writers on this topic say. For many people, the first ten years of retirement are the healthiest and most active.
Most of the mistakes on this list are small and fixable. Carry the medication yourself, skip the extra suitcase, and leave breathing room in the itinerary. The costly ones are bigger: Medicare generally won’t follow you abroad, evacuation can run into six figures by one insurer’s estimate, and big early withdrawals carry real risk.
But the suitcase will always be lighter than the regret. The trip you plan carefully and actually take beats the perfect one that stays on the calendar as “someday.”