Everyone quotes the same number when talk turns to retirement travel: eleven grand a year, tuck it away, done. But the real spending data from actual retirees tells a much messier story, where some couples travel constantly on a shoestring while others blow through six figures chasing a single bucket-list cruise.
The gap between what financial articles claim and what retirees actually spend at the airport, on the cruise ship, and in the RV is bigger than most people realize. Here’s what the numbers actually say.
The “Average” Number Everyone Quotes Is Almost Meaningless
You’ve probably seen the headline stat that gets recycled everywhere: no matter if it’s a road trip or a European vacation, the average retiree spends about $11,000 on travel. It sounds precise. It sounds like a solid planning target. It’s also nearly double what government data actually shows for most retirees.
The Bureau of Labor Statistics Consumer Expenditure Survey puts average annual travel spending for U.S. households headed by someone 65 to 74 at roughly $4,000 to $7,000. That’s a massive gap from the number floating around in retirement blogs. The truth is there’s no single “average” – there’s a huge range depending on whether you’re talking about a quiet year at home or the year you finally book that trip to Italy.
Quick Compare
- The viral number: about $11,000 a year, quoted almost everywhere.
- The government number: roughly $4,000 to $7,000 for ages 65 to 74.
- The real story: no flat average – spending swings hard between quiet years and splurge years.
The Real Baseline Most Retirees Actually Live On
Strip away the flashy bucket-list years, and a clearer pattern shows up. Retirees can plan on spending around $5,000 a year on travel for the next 10 to 15 years of retirement in a typical, non-splurge year. That’s the boring baseline – regional trips, visiting family, a long weekend here and there.
The bigger number only shows up in specific years. According to Investopedia, the average retiree can spend about $10,000 for a big European vacation in one year. So the real formula isn’t one flat number – it’s a low baseline most years, punctuated by one or two expensive splurge years. Most retirement calculators completely miss this uneven pattern.
Boomers Just Blew the Travel Budget Wide Open
If you think retirees are cutting back because of inflation, the data says the opposite is happening. Travel budgets are soaring more than 30% to $5,915 per person across all age groups heading into this year. Baby boomers aren’t just keeping pace – they’re driving the surge.
Baby boomers expect to spend $12,462 on travel, 52% more than in 2024. That’s not a typo. Boomers increased their travel spending by more than half in a single year, which reshapes what a “normal” trip fund even looks like for this generation compared to the outdated $5,000-a-year assumption.
A Single Bucket-List Trip Can Cost More Than a Year of Groceries
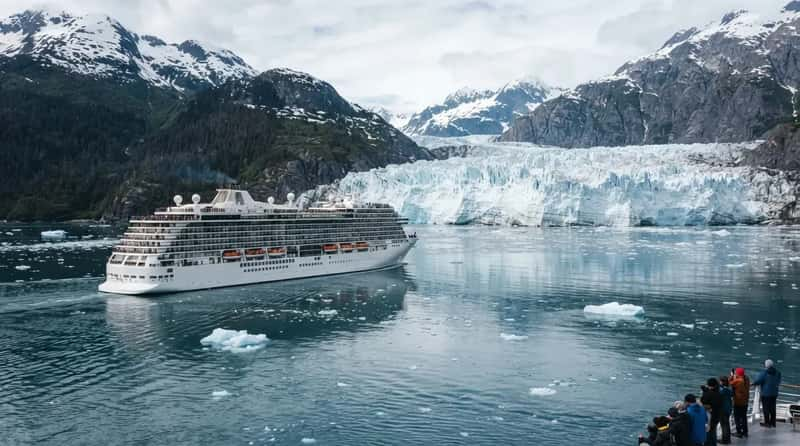
Alaska is the classic retirement dream trip, and the pricing swings wildly depending on how you book it. The cost of an Alaska cruise in 2025 ranges from $600 to $10,000 per person, depending on cabin category, itinerary length, and cruise line. That’s a sixteen-fold difference for essentially the same glaciers and whales.
The base fare is only part of the story, though. Travelers should budget an additional $1,000 to $1,500 per person for shore excursions to get the most out of an Alaskan cruise. Add flights, pre-cruise hotel nights, and gratuities, and a “budget” Alaska trip for two can quietly cross $6,000 before anyone sets foot on a glacier.
At a Glance
- Base cruise fare: $600 to $10,000 per person.
- Shore excursions: add $1,000 to $1,500 per person.
- Flights, hotels, and gratuities: often push a “budget” trip for two past $6,000 total.
The Snowbird Dream Isn’t as Cheap as It Used to Be
One retired sales director tested the classic snowbird plan the year he retired. When he retired in 2022, he and his partner spent roughly $5,000 on a 28-day stay at a two-bedroom home near Huntington Beach, California. It felt like a smart, sustainable way to spend winter.
Costs caught up fast. This year, they spent $3,100 for a one-bedroom suite in Phoenix – around 62% of what they spent on accommodation back in 2022, but for only a nine-day stay. Same dollars, drastically less winter. The couple now works with an annual travel budget of around $7,000, and they’re far from alone – rising costs are quietly shrinking the “affordable” snowbird lifestyle for an entire generation.
The Hidden Line Items That Blow Up a Travel Budget
Retirees who plan carefully still get ambushed by the same add-ons every time. Beyond the base fare, cruise lines tack on port fees and taxes, and shore excursions like glacier hikes or helicopter rides typically run between $50 and $500 per excursion.
Then there’s onboard spending. Specialty dining can cost $20 to $50 per meal, and beverage packages run $50 to $80 per day. Multiply that across a seven-night cruise for two people, and the “extras” alone can rival the cost of the cabin itself. Nobody budgets for the drink package until they’re staring at the final bill.
Fast Facts
- Shore excursions: $50 to $500 per person, per excursion.
- Specialty dining: $20 to $50 per meal.
- Beverage packages: $50 to $80 per day.
- Over a seven-night cruise for two, extras alone can rival the cabin price.
The Family Trip Trap: When “Together Time” Costs More Than Solo Travel
Multigenerational trips sound wholesome and budget-friendly – split the cost across three generations, right? Not quite. Grandparents spent an average of $5,205 on multigenerational family travel in 2024, and that’s just the grandparents’ share.
It ranks among the higher-spend travel categories in retirement, mostly because grandparents tend to cover flights, activity tickets, and extra bedrooms for grandkids without splitting costs evenly. It’s often the single most expensive “family” line item in a retiree’s entire year – a truth many grandparents never quite admit out loud.
Some Retirees Travel Constantly for Almost Nothing
Not every retirement trip fund needs six figures. One retired couple in their 60s takes two international trips a year and openly rejects the standard $12,000-per-trip budgeting math other travelers use. They don’t spend nearly that amount, instead watching for airfare and frequent flier mile sales – once booking a flight for just $400 cash total for two people round-trip.
They keep and churn airline credit cards to rack up miles for when flight prices spike, flying economy but choosing seats and checking bags for free thanks to those cards. It’s a strategy most financial articles never mention: the biggest lever in a retirement trip fund isn’t savings – it’s points.
The $80 Pass Most Retirees Never Bother Buying
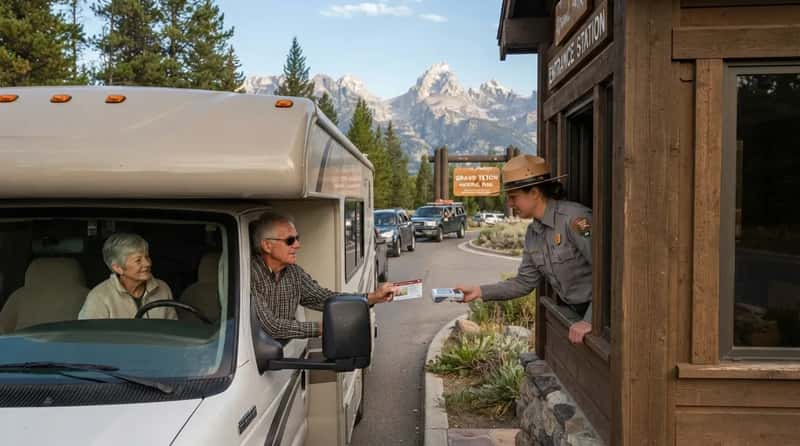
For retirees planning national park road trips instead of cruises, there’s a shortcut hiding in plain sight. The annual “America the Beautiful Pass” costs $80 and covers entry to all fee-charging national parks and other federal recreation sites – for an entire vehicle of passengers.
Seniors get an even better deal. They can buy the Senior Pass for $20 a year or $80 for a lifetime pass, available to U.S. citizens ages 62 and up. For a couple planning even three or four park visits a year, that lifetime pass pays for itself almost immediately – yet most people never look it up before their first trip.
Worth Knowing
- America the Beautiful Pass: $80 a year, covers an entire vehicle.
- Senior Annual Pass: $20 a year, ages 62 and up.
- Senior Lifetime Pass: $80 one-time, never buy a park pass again.
Your Travel Budget Should Actually Shrink as You Age – Most People Plan It Backwards
Here’s the part most retirement calculators get wrong: they assume flat spending for thirty straight years. Real data shows travel spending falls off a cliff with age. Research shows that 75-year-olds spend 19% less than 65-year-olds, and the drop only accelerates from there.
85-year-olds tend to spend 34% less than 65-year-olds, largely because people in their 80s travel far less, if at all, compared to 65-year-olds. That means the biggest trip fund isn’t needed at age 85 – it’s needed right now, in the first decade of retirement, while the legs and the passport are both still willing.
So What’s the Real Number You Actually Need?
Put the pieces together and a realistic trip fund looks less like one flat figure and more like a layered plan: roughly $5,000 to $7,000 for a normal year, spiking to $10,000 to $15,000 for a true bucket-list trip every few years, front-loaded into the first decade of retirement. Cost genuinely matters here – on average, retirees weren’t expecting to spend more on their trips than the year before, and cost was the most commonly cited travel barrier in recent surveys.
Zoom out even further and the lifetime scale becomes clear. One national estimate calculated a lifetime cost of $180,621 based on a yearly $2,867 trip from ages 22 to 85 – a modest, non-retiree-specific baseline. In a Fifth Third Bank survey, 81% of pre-retirees and retirees said travel was their top priority, which is exactly why the fund deserves its own line item, separate from everyday retirement expenses.
Fast Facts
- Typical year: $5,000 to $7,000.
- Bucket-list year: $10,000 to $15,000, roughly every few years.
- Best strategy: front-load the big spending into the first decade of retirement.
The Bottom Line
The retirement trip fund nobody talks about honestly isn’t one number – it’s a shrinking curve that peaks hard in the first ten years and fades fast after that. Most retirees don’t need $11,000 a year forever. They need $5,000 most years, a real splurge every few years, and the discipline to spend the big money early, while they still can.
The couples getting the most out of retirement travel aren’t the ones with the biggest budgets. They’re the ones who figured out where the real costs hide – and spent boldly before the window started closing.