Travel insurance sounds simple on paper. You pay a small fee, something goes wrong, and the company pays you back. In practice, the fine print is where things get complicated, and most travelers only discover the gaps in their coverage after they’ve already filed a claim and gotten a denial letter in return.
The details that actually matter rarely show up in the marketing copy on comparison sites. They’re buried in the certificate of insurance, the document almost nobody reads before clicking “purchase.” Here’s what tends to surprise people the most, and why it’s worth understanding before you ever need to use the policy.
Pre-existing conditions can quietly void your coverage
Most travelers assume a “comprehensive” policy covers whatever health issue comes up on a trip. It doesn’t automatically cover conditions you already had. Insurers use something called a lookback period, a window before your purchase date during which they examine your medical history to decide if a condition counts as pre-existing, and that window usually ranges anywhere from 60 to 180 days.
If anything changed during that stretch, a new prescription, a dosage adjustment, a visit to a specialist, it can be treated as a red flag. If you had symptoms, received treatment, had a change in medication, or were diagnosed with a condition during the lookback period, it would typically be excluded from coverage unless you qualify for a pre-existing condition waiver. The workaround exists, but only if you act fast and buy the right plan at the right time.
The waiver that saves you has a strict deadline
There is a fix for the pre-existing condition problem, and it’s called a pre-existing condition exclusion waiver. It removes the standard exclusion, but only if you meet a short list of requirements, and timing is the one people miss most often. To qualify for pre-existing condition travel insurance coverage, you typically must purchase your travel insurance policy 14-21 days after your initial trip deposit date.
Beyond the purchase window, you generally need to insure the full non-refundable cost of the trip and be medically fit to travel on the day you buy the policy. Miss any one of those conditions and the waiver simply doesn’t apply, no matter how minor the health issue turns out to be. As one insurer glossary puts it plainly, waivers are time-sensitive benefits, and if you miss the purchase window, they’re gone.
Medical evacuation costs far more than people expect
This is the number that changes minds once people actually see it. Emergency transport abroad is not a minor line item, it’s often the single biggest expense in a serious travel medical emergency. According to the CDC and State Department guidance cited by insurers, emergency medical evacuations to the USA can cost upwards of $200,000, depending on your location and the severity of your condition.
Even a relatively short helicopter transport within North America is not cheap. The national average for an emergency helicopter ride is about $40,000, according to medical travel service Flying Angels. Trek somewhere remote and the price climbs fast, with real-world estimates from a mountain rescue in Nepal running from a fall while trekking in the Upper Mustang, a remote part of Nepal, needing a medevac helicopter, possible cost $150,000-$200,000, or more.
Your regular health insurance almost never follows you abroad
A lot of travelers skip insurance because they assume their existing health plan has them covered. It usually doesn’t, especially once you leave the country. The truth is your health plans, including Medicare, will most likely offer little to no coverage if you’re traveling outside the US.
Even domestically, standard health coverage has limits that surprise people. About two-thirds of medical flights in 2017 for people with private insurance are still out-of-network, according to the U.S. General Accounting Office, meaning you’re on the hook for most or all of that bill, unless you have medical evacuation insurance. That gap between “I have insurance” and “my insurance covers this specific situation” is exactly where financial disasters happen.
Cancel For Any Reason sounds better than it actually is
Cancel for Any Reason, often shortened to CFAR, is marketed as the ultimate flexibility upgrade. It is genuinely useful, but the name oversells it a little. It has to be purchased early, it has a partial reimbursement rate, and it costs meaningfully more than a standard policy.
According to CDC travel health guidance, comprehensive policies can cost up to 8% when cancellation for a list of reasons is met and up to 15% of the cost of the trip for cancellation for any reason. On top of the higher price, most CFAR add-ons only reimburse a portion of your trip cost rather than the full amount, so read the percentage carefully before assuming you’re fully covered.
Standard trip cancellation only covers a specific list of reasons
Without the CFAR upgrade, a standard trip cancellation benefit only pays out for reasons explicitly named in the policy. Getting cold feet, a work schedule change, or simply changing your mind about the destination typically isn’t on that list. The policy documents spell out covered reasons in detail, and anything outside that list is treated as uncovered no matter how legitimate it feels to you.
This is part of why insurers keep pushing the CFAR upgrade so heavily. It exists specifically to fill the gaps that a standard list-based policy leaves open, covering situations the base plan was never designed to handle in the first place.
Credit card travel protection is not a substitute for a real policy
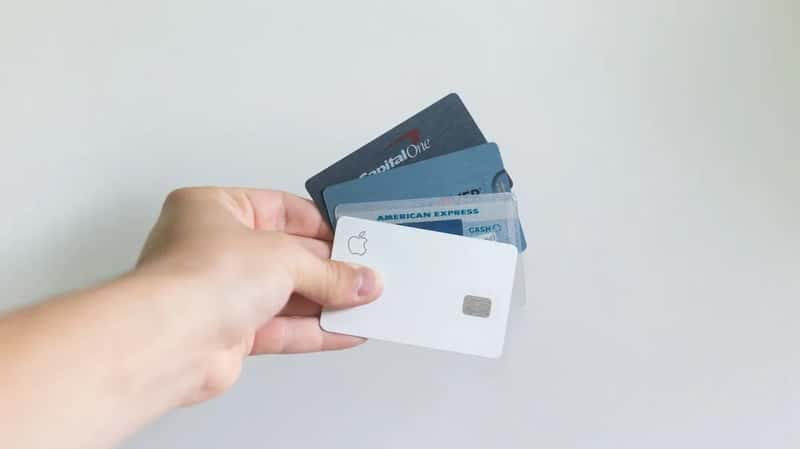
Many travelers assume the travel protection bundled with a premium credit card is equivalent to a purchased policy. It rarely is. Credit card benefits tend to have lower coverage limits, narrower definitions of what counts as a covered event, and almost no meaningful medical evacuation coverage.
CDC guidance notes plainly that credit card companies may offer travel protection benefits under specific conditions, language that hints at just how conditional those benefits usually are. If your card’s protection was never designed around medical evacuation or serious illness abroad, it likely won’t hold up the way a dedicated travel medical or comprehensive policy would.
Filing a claim requires paperwork you probably don’t have yet
Insurers don’t take your word for it when a medical claim comes in tied to a health condition. They ask for documentation, and a lot of it. Typical requests include medical records from your doctor or specialist showing consistent treatment with no significant changes in medication, dosage, or symptoms, physician’s notes confirming stability, and prescription history.
If the paperwork doesn’t line up, or if a traveler never realized they needed to keep it in the first place, claims stall or get denied outright. This is one of the quieter reasons people feel blindsided after a trip goes wrong. It’s not that the coverage didn’t exist, it’s that proving eligibility for it after the fact turns out to be its own project.
Adventure activities can fall outside your policy without you realizing it
Skiing, diving, hiking at altitude, motorbike riding, these activities carry their own risk profile, and standard travel policies don’t always treat them as automatically covered. Insurance guidance recommends travelers heading into higher-risk activities look for specific upgrades rather than assuming the base plan has them covered. Travelers engaging in activities such as hiking, skiing, diving, or traveling in isolated or offshore areas may require evacuation by air rather than ground transport, and it’s generally advisable to carry higher medical evacuation limits, often $250,000 or more, to account for the added complexity and cost of remote evacuations.
That’s a meaningfully higher number than the coverage baked into a basic budget policy. If your itinerary includes anything more adventurous than sightseeing, it’s worth checking the sports and activity exclusions section of the policy specifically, rather than assuming general medical coverage extends automatically to every situation you might encounter.
Annual plans and single-trip plans solve different problems
Frequent travelers often default to annual multi-trip plans because the math looks better over several trips a year. That convenience comes with a tradeoff worth knowing about. Exclusion waivers are also not available in annual or multi-trip travel insurance plans, so to access pre-existing condition coverage, you must purchase a single-trip policy and meet all the eligibility requirements.
That single detail changes the calculation for anyone managing an ongoing health condition. An annual plan might be cheaper and more convenient for someone healthy and traveling often, but a traveler with a recent diagnosis or medication change may actually need the flexibility of a single-trip policy purchased early enough to qualify for the waiver.
Final thoughts
Travel insurance works exactly as advertised most of the time, but the exceptions are rarely random. They cluster around a handful of predictable spots: the lookback period, the CFAR fine print, evacuation limits that seemed generous until you compare them to real costs, and paperwork requirements nobody mentions until a claim is already underway.
None of this means skip the policy. It means read the certificate of insurance before you need it, not after. The difference between a smooth reimbursement and a frustrating denial usually comes down to details that were sitting in the document the whole time, just not the parts anyone highlights when they’re trying to sell you the plan.