Maybe your retired brother or sister posts beach photos every few months, yet drives an old sedan and clips coupons. It’s natural to wonder how the numbers add up. Sometimes the answer is simple thrift. Sometimes it’s a larger nest egg than anyone realizes.
None of the signs below proves anything on its own, and it’s not our business to audit a sibling’s bank balance. Plenty of modest-income retirees travel well with planning, points and discounts. Still, a handful of patterns show up often enough in research on wealth and retirement travel that they’re worth knowing about, if only for curiosity and for your own planning.
1. Their everyday life looks ordinary while their passport stays busy
The classic pattern is plain living at home and big trips abroad. Stanley and Danko found that the typical millionaire was a small business owner or professional who lived below their means, invested consistently, and avoided status spending.[1] That research dates from the 1990s, so it’s a rough guide, not a rule. Even so, the idea that quiet spending can hide real savings still holds up.
Look at where the money doesn’t go. Driving older cars, wearing affordable clothing, and living in modest homes are common among the wealthy[2], according to one summary of the book. A sibling who skips the new kitchen and the luxury SUV but never skips a trip may simply be choosing experiences over things. If that choice is sustained for years, it often points to a comfortable cushion.
2. They take long, slow trips instead of quick getaways
Retirees with real financial confidence tend to stay put longer. In a July 2026 Boldin survey of retirement savers, half of respondents expected to take several extended trips, and 40% pictured spending weeks or even months in a single destination.[3] That’s a survey of people already planning their retirement carefully, not all retirees. Even so, it shows what travel looks like when money feels less tight.
Staying longer can be cost-smart too, which is why it isn’t proof of wealth. Long-stay bookings of a week or more can cut nightly costs by up to 32%[4], according to one retirement travel guide. The telling detail is the total. A sibling who regularly spends a month or more away, yet never seems to fret about the household budget back home, probably has solid income or savings behind the scenes.
3. They travel off-peak and never seem rushed to book
Flexibility is a quiet luxury. Retirees are free from the school calendar and the workweek, so they can often fly on cheaper days, usually a Tuesday or Wednesday.[5] Many frugal travelers do this on purpose, so it isn’t a wealth signal by itself.
The sign is what happens when plans change. Someone who can rebook a flight, extend a stay or leave on short notice without drama has a cushion that many households lack. Cost is the thing that most often boxes people in. Cost is the biggest barrier to travel for 45 percent of adults 50 and older[6], so a sibling who treats price changes as a shrug is in a smaller group.
4. They pay for the family trips others only talk about
Multigenerational travel is one of the pricier categories in retirement. Grandparents spent an average of $5,205 on multigenerational family travel in 2024, according to the U.S. Family Travel Survey 2025.[7] That’s a lot to add on top of personal trips.
If your sibling quietly covers a rental house for the whole clan, or treats the grandkids to a cruise, take note. Family is a big driver of older adults’ travel. More than half (56%) of respondents in AARP’s 2025 study said spending time with family or friends was a top motivator.[8] Still, generosity at that scale usually means the money isn’t tight.
5. They treat travel as a planned line item, not a splurge
People with strong finances tend to budget for the fun parts of retirement ahead of time. In the Boldin survey, 89% of members who prioritize travel had factored it into their plan in some form, compared with just 58% of a broader panel of affluent adults.[7] Those are subscribers of a planning tool, so they’re likely more organized than average.
The signal in real life is a certain calm. Your sibling may talk about “this year’s trip fund” the way others talk about a utility bill. That kind of structure often comes from having modeled the numbers in advance, and it separates a sustainable travel habit from an expensive one that leaves a retiree anxious later.
6. Their yearly travel total clearly beats the typical retiree’s
It helps to know what normal looks like. AARP reports that adults 50 and older anticipated travel expenses of $6,847 in 2025, compared with $6,659 in 2024.[6] One roundup citing Bureau of Labor Statistics data puts average annual travel spending for households headed by someone 65 to 74 at roughly $4,000 to $7,000.[9]
So if your sibling regularly takes a couple of international trips plus a cruise, the total may land well above those averages. Be careful with this one, since you rarely see the true cost. A good deal or a points redemption can make a big trip cheap. Still, sustained spending far above the norm, year after year, usually needs resources behind it.
7. They’ve mastered rewards, and they pay the balance in full
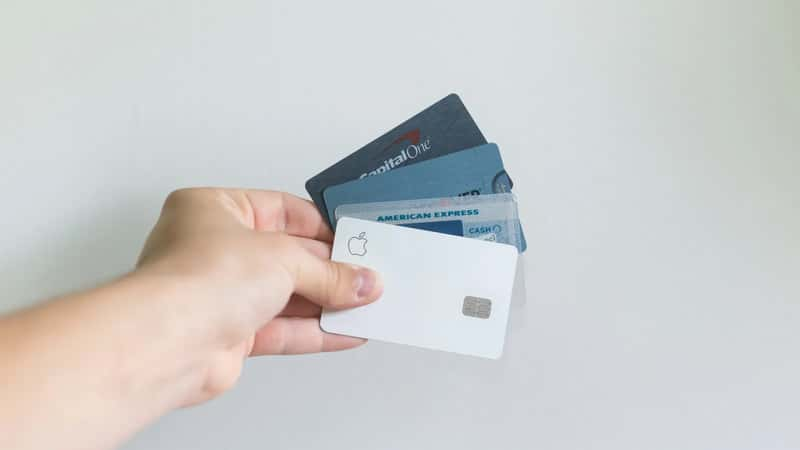
Points and miles are a legitimate way to travel on less. Many travel credit cards offer large sign-up bonuses that can cover flights or hotels.[10] The catch is discipline. The same guide advises to always pay your balance in full.[10]
Some perks also reward people who already hold large balances. For example, one card review notes that an average daily balance of between $100,000 and $999,999 across Bank of America accounts and Merrill investments earns a 50% rewards bonus.[11] That doesn’t mean your sibling has that, only that premium travel tiers often favor those with assets. A sibling who talks fluently about transfer partners and lounge access is either a skilled optimizer or well funded, and sometimes both.
8. They track every dollar and rarely talk about money
Quiet wealth often comes with careful bookkeeping. Wealthy households in the book carefully track spending on food, clothing, shelter and other categories.[2] One excerpt notes that for every 100 millionaires who don’t budget, about 120 do.[12] So the sibling who knows what everything costs may be better off than the one who spends freely.
Privacy fits the same pattern. Another summary says such people tend to live among middle-class families, keeping their wealth mostly under wraps.[12] If your sibling changes the subject when money comes up, it isn’t proof of anything. Yet in combination with other signs here, it’s a familiar pattern.
9. Rising costs and market swings don’t seem to rattle them
Many retirees feel squeezed. Forty-five percent of retirees say their overall expenses are higher than anticipated, according to both AARP and the 2025 Employee Benefit Research Institute’s Retirement Confidence Survey.[13] Travel is usually the first thing to go when that happens.
In the Boldin survey, more than two-thirds of subscribers said they would probably or definitely reduce spending if markets declined early in retirement, and luxury goods and travel were the discretionary expense most likely to be reduced.[3] A sibling who keeps booking trips through volatile years, with no talk of “cutting back,” likely has a bigger buffer than most. That steadiness is probably the most reliable sign on this list.
Taken together, these signs describe a certain kind of retiree: low-key at home, flexible about timing, organized about money and generous with family. Any one of them has an innocent explanation, from clever deal-hunting to a lifetime of careful saving. The more of them that line up, the likelier it is that the modest exterior is hiding a healthy balance sheet.
Whatever the truth, there’s something to learn. The habits that fund a quiet life of travel, like steady saving, planning ahead and not chasing status, are open to anyone. Your sibling’s secret may not be a secret fortune at all, just years of choosing the boarding pass over the showroom.