Many travelers assume a standard travel insurance policy will handle any mishap during a cruise, yet gaps in coverage frequently leave passengers responsible for substantial medical bills or lost deposits. Onboard treatment and emergency evacuations at sea carry costs that routine policies often exclude unless cruise-specific protection is added. This distinction matters because cruise lines require advance payment and medical services operate independently of land-based systems. ([1])
Medical Treatment at Sea Carries Distinct Risks
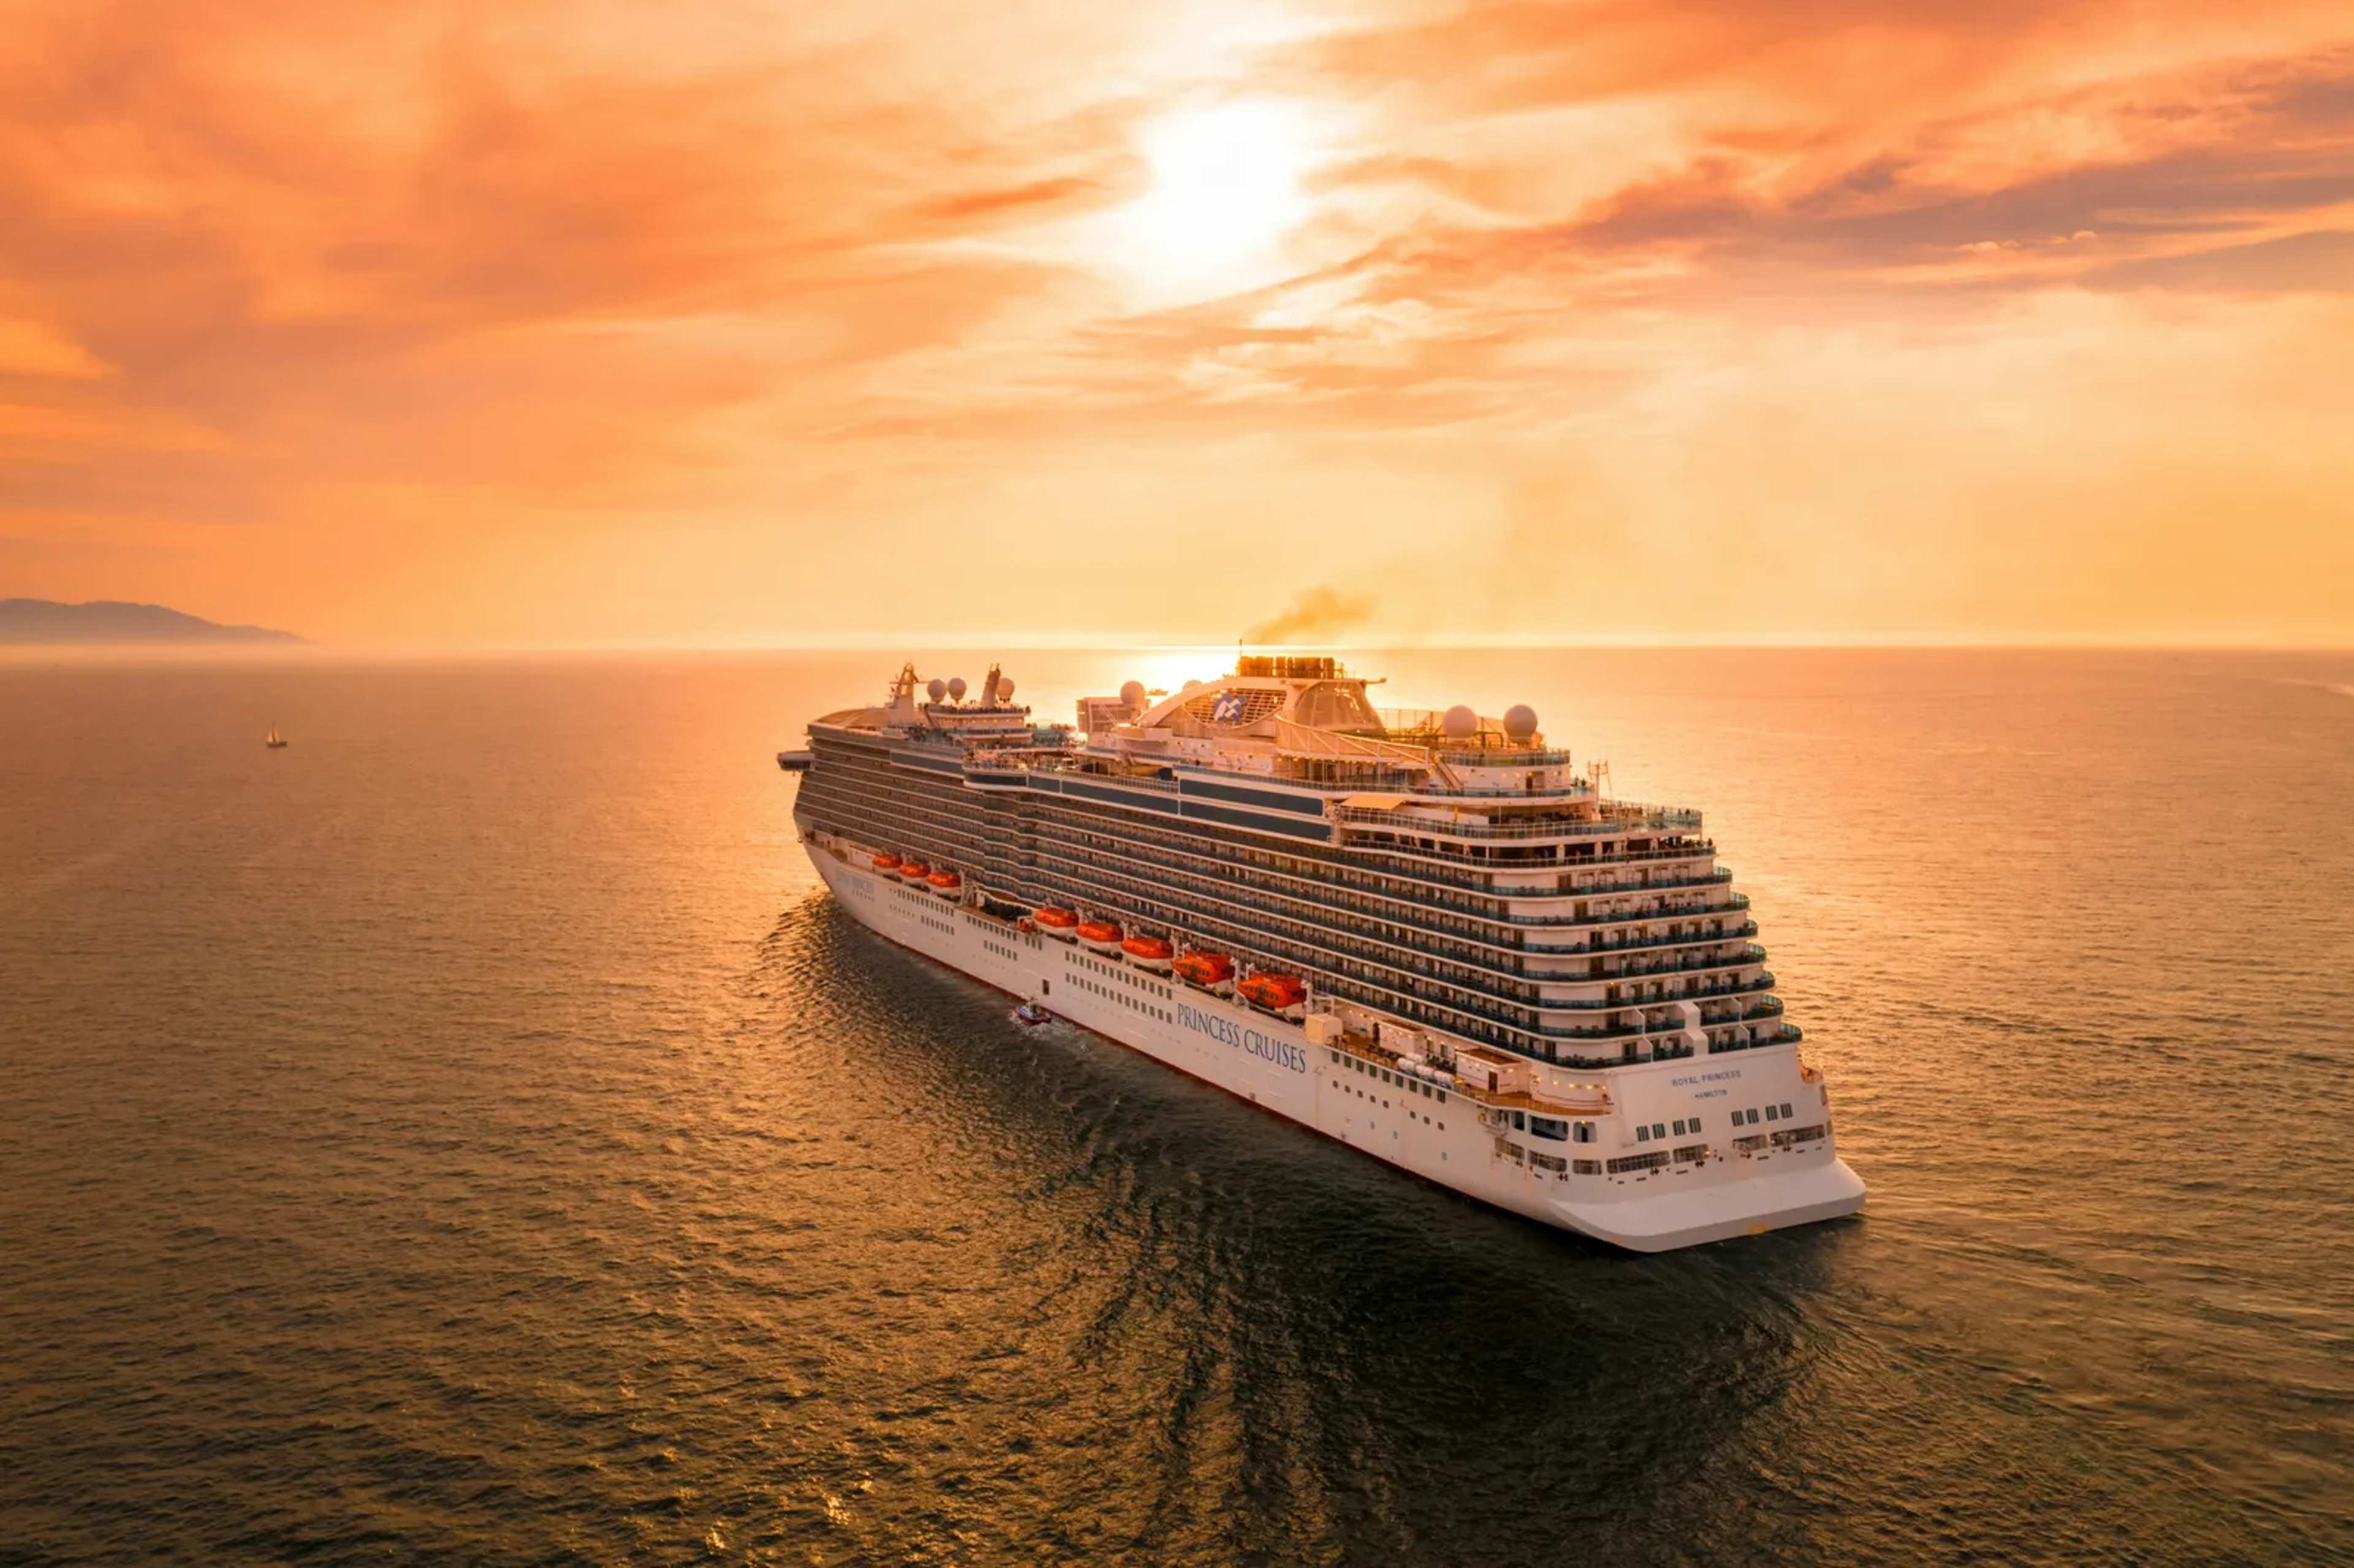
Illness or injury on a cruise ship can require immediate care that passengers must pay for upfront. Evacuations by helicopter or specialized vessel add further expense, sometimes reaching six figures depending on location and urgency. Travelers from countries with universal healthcare systems may find those benefits do not extend to vessels at sea, even in domestic waters. Policies without explicit cruise provisions leave individuals settling charges directly with the provider before any reimbursement process begins.
Budgeting for potential out-of-pocket costs becomes essential when coverage is uncertain. Review of policy wording reveals whether limits apply to maritime medical events or whether evacuation is addressed at all. Different cruise types, such as river versus ocean voyages, can influence the scope of available protection as well.
Cruise Coverage Typically Requires an Explicit Add-On
Insurance providers structure most policies around common land-based travel, treating cruises as a separate category that demands additional selection. The added risk stems from the isolated nature of medical facilities and the logistics of returning passengers to shore. Activities like white-water rafting or extreme sports illustrate a similar pattern, where higher potential claims lead companies to offer coverage only through targeted upgrades.
Shoppers who overlook the cruise option during purchase often discover the omission only after an incident occurs. Policies vary by destination and vessel type, so confirmation at the point of sale prevents later disputes. Early selection of the appropriate add-on aligns protection with the full itinerary rather than leaving portions exposed.
Cancellation and Shore Excursion Protections Demand Attention
Cruise operators usually require full payment well in advance, often 75 to 120 days before departure, to secure logistics and staffing. Standard cancellation coverage may not extend to these prepaid amounts unless the policy explicitly includes cruise travel. Passengers facing sudden illness or schedule changes risk forfeiting significant sums without the right endorsement.
Shore excursions introduce further variables, including snorkeling, quad biking, or wildlife encounters that may fall outside basic onboard coverage. Policies must address both shipboard incidents and land-based activities to avoid gaps during port calls. Purchasing coverage at the time of booking, rather than days before sailing, helps maintain continuity across all elements of the trip.
Practical Steps to Verify Protection Before Departure
Travelers can reduce exposure by following a structured review process when selecting a policy. The following points highlight key areas that require confirmation:
- Confirm cruise coverage appears as an active component rather than an optional extra.
- Check stated limits on medical expenses and evacuation services to ensure they align with potential costs.
- Examine whether shore excursions receive the same protection as time spent on the vessel.
- Verify that cancellation benefits match the full prepaid amount of the cruise.
- Declare any pre-existing medical conditions at purchase to avoid later exclusions.
- Store digital copies of policy documents on a mobile device for immediate reference.
Consulting official resources such as government travel advisories provides additional context on regional requirements and recommended coverage levels. Product disclosure statements from insurers offer detailed terms that clarify exactly what is included.
What matters now: Cruise passengers who review policies at the booking stage rather than after an incident occurs can avoid unexpected financial responsibility for medical care or lost deposits.
Selecting the right endorsements before travel begins ensures that coverage matches the realities of a cruise itinerary. This approach protects against both onboard emergencies and disruptions that arise before departure.